Gem Forest One Minute Scalping Strategy
The Gem Forest One Minute Scalping Strategy is a quantitative trading strategy for short-term trading. It combines multiple indicators to identify market oscillation characteristics within a 1-minute timeframe and…
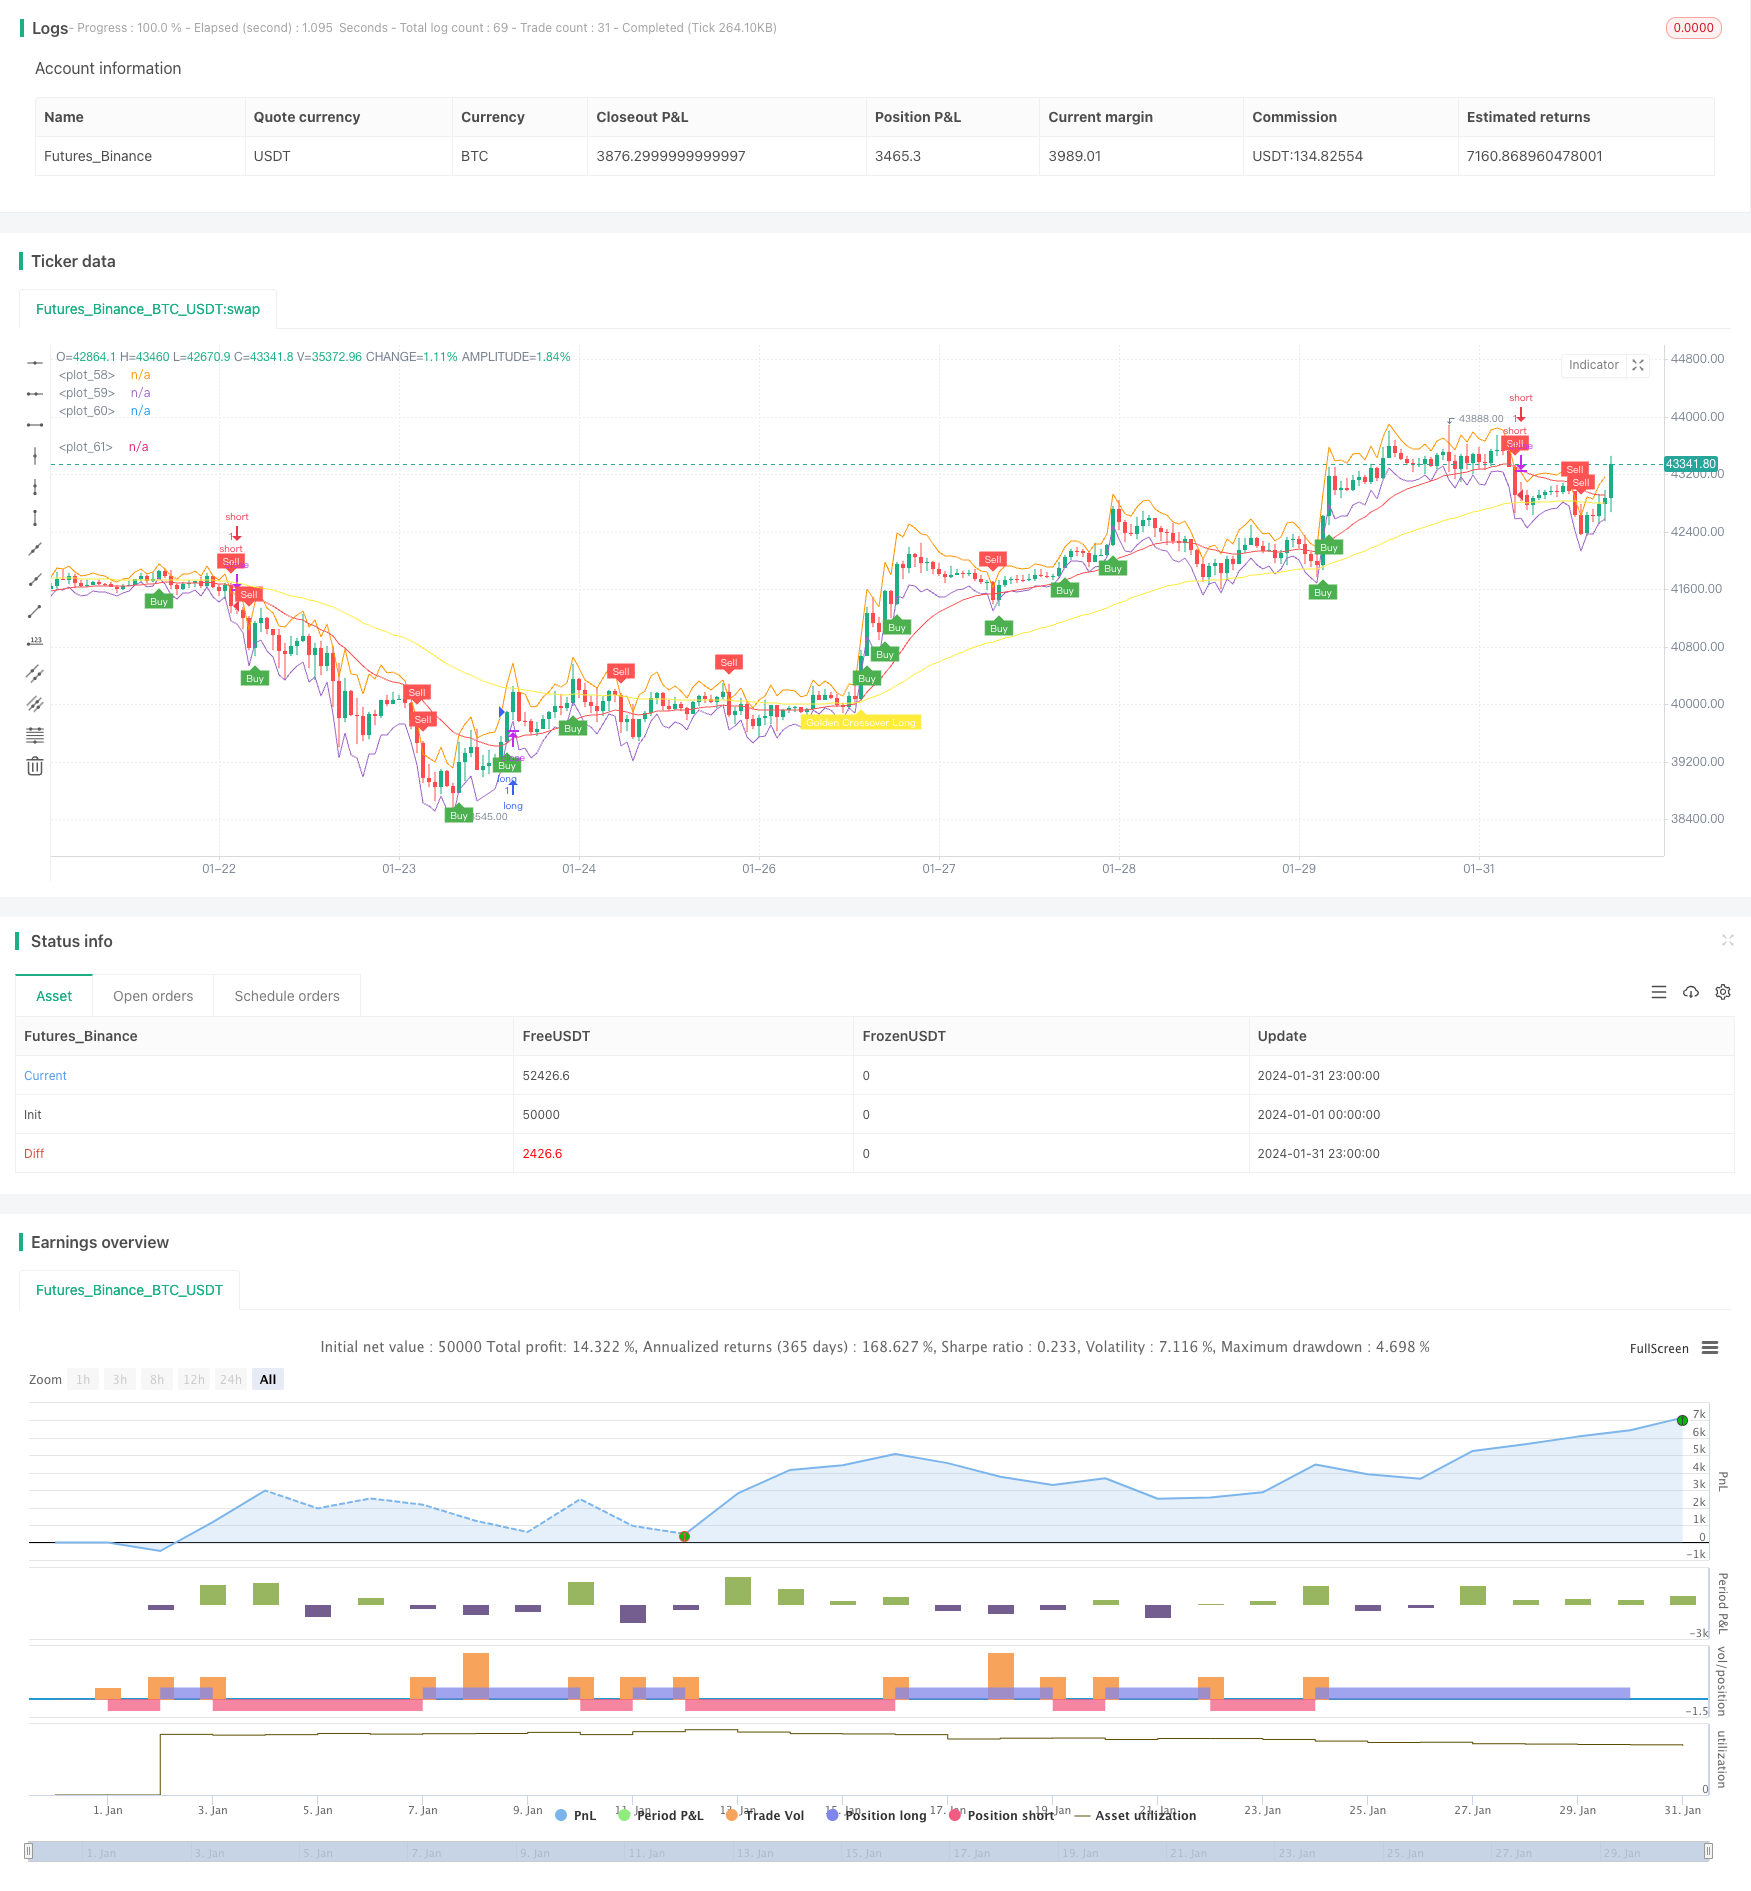
Overview
The Gem Forest One Minute Scalping Strategy is a quantitative trading strategy for short-term trading. It combines multiple indicators to identify market oscillation characteristics within a 1-minute timeframe and switch between long and short positions for ultra-short scalping.
Strategy Logic
- ATR indicator builds upper and lower bands to determine price oscillation range
- Fast and slow EMA crossovers generate trading signals
- Dual RSI indicators confirm crossover signals
- Entry and exit points are determined by combining indicator signals and price levels
When price is below the lower band, fast and slow EMA golden cross happens, fast RSI crosses above slow RSI, a buy signal is generated; When price is above upper band, fast and slow EMA dead cross happens, fast RSI crosses below slow RSI, a sell signal is generated. After entry, stop loss and take profit are used for exit.
Advantage Analysis
- Multiple indicators combined improves reliability
- High operation frequency provides greater profit potential
- Smaller drawdowns, better stability
- Capable of ultra-short scalping within 1-min or shorter timeframe
Risk Analysis
- Higher requirements for network and hardware due to high frequency
- Over-trading and capital scattering risks
- False signals from poor indicator configuration
- Vulnerable to stop loss in volatile market conditions
These risks can be managed by optimizing parameters, adjusting stops, limiting max daily trades, choosing proper products etc.
Optimization Directions
- Test impact of different ATR periods
- Try different EMA types or replace one EMA
- Adjust RSI periods or test other oscillators like KDJ, Stochastics etc
- Improve entry logic with more factors like trends
- Optimize stops for better risk-reward ratio
Conclusion
This strategy fully considers the characteristics of ultra-short quantitative trading. Reasonable indicator settings, multiple confirmations and combinations ensure high reliability. With strict risk control, it has considerable profit potential and suits investors with sufficient computing power and psychological quality.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 14 | ATR Period |
| v_input_float_1 | true | ATR Multi |
| v_input_string_1 | 0 | ATR Smoothing: WMA | SMA | EMA | RMA |
| v_input_int_2 | 21 | Fast EMA |
| v_input_int_3 | 65 | Slow EMA |
| v_input_int_4 | 25 | Fast RSI Length |
| v_input_int_5 | 100 | Slow RSI Length |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Gem Forest 1 Dakika Scalp", overlay=true)

source = close
atrlen = input.int(14, "ATR Period")
mult = input.float(1, "ATR Multi", step=0.1)
smoothing = input.string(title="ATR Smoothing", defval="WMA", options=["RMA", "SMA", "EMA", "WMA"])

ma_function(source, atrlen) =>
    if smoothing == "RMA"
        ta.rma(source, atrlen)
    else
        if smoothing == "SMA"
            ta.sma(source, atrlen)
        else
            if smoothing == "EMA"
                ta.ema(source, atrlen)
            else
                ta.wma(source, atrlen)

atr_slen = ma_function(ta.tr(true), atrlen)
upper_band = atr_slen * mult + close
lower_band = close - atr_slen * mult

ShortEMAlen = input.int(21, "Fast EMA")
LongEMAlen = input.int(65, "Slow EMA")
shortSMA = ta.ema(close, ShortEMAlen)
longSMA = ta.ema(close, LongEMAlen)
RSILen1 = input.int(25, "Fast RSI Length")
RSILen2 = input.int(100, "Slow RSI Length")
rsi1 = ta.rsi(close, RSILen1)
rsi2 = ta.rsi(close, RSILen2)
atr = ta.atr(atrlen)

RSILong = rsi1 > rsi2
RSIShort = rsi1 < rsi2

longCondition = open < lower_band
shortCondition = open > upper_band
GoldenLong = ta.crossover(shortSMA,longSMA)
Goldenshort = ta.crossover(longSMA,shortSMA)

plotshape(shortCondition, title="Sell Label", text="Sell", location=location.abovebar, style=shape.labeldown, size=size.tiny, color=color.red, textcolor=color.white, transp=0)
plotshape(longCondition, title="Buy Label", text="Buy", location=location.belowbar, style=shape.labelup, size=size.tiny, color=color.green, textcolor=color.white, transp=0)
plotshape(Goldenshort, title="Golden Sell Label", text="Golden Crossover Short", location=location.abovebar, style=shape.labeldown, size=size.tiny, color=color.blue, textcolor=color.white, transp=0)
plotshape(GoldenLong, title="Golden Buy Label", text="Golden Crossover Long", location=location.belowbar, style=shape.labelup, size=size.tiny, color=color.yellow, textcolor=color.white, transp=0)

if (longCondition)
    stopLoss = low - atr * 2
    takeProfit = high + atr * 5
    strategy.entry("long", strategy.long, when = RSILong)

if (shortCondition)
    stopLoss = high + atr * 2
    takeProfit = low - atr * 5
    strategy.entry("short", strategy.short, when = RSIShort)

plot(upper_band)
plot(lower_band)
plot(shortSMA, color = color.red)
plot(longSMA, color = color.yellow)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Gem-Forest-One-Minute-Scalping-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 20Bitcoin and Gold 5 Minute Scalping Strategy 20Pine Script · Scalping · 1h
- Super ScalperPine Script · Scalping · 1m
- Super Scalper 5 Min 15 MinPine Script · Scalping · 5m
- Multi Timeframe Support Resistance Momentum Scalping Strategy with Volatility Adjusted Risk ManagementPine Script · Scalping · 1h
- Stochastic RSI with Auto Buy Scalper StrategyPine Script · Scalping · 1h
- Williams Alligator Scalping StrategyPine Script · Scalping · 4d