Gold VWAP MACD SMO Trading Strategy
The Gold VWAP MACD SMO trading strategy is a complete strategy designed for the gold market using a 12-hour timeframe chart. It combines VWAP monthly, SMO oscillator and MACD histogram to identify trading…
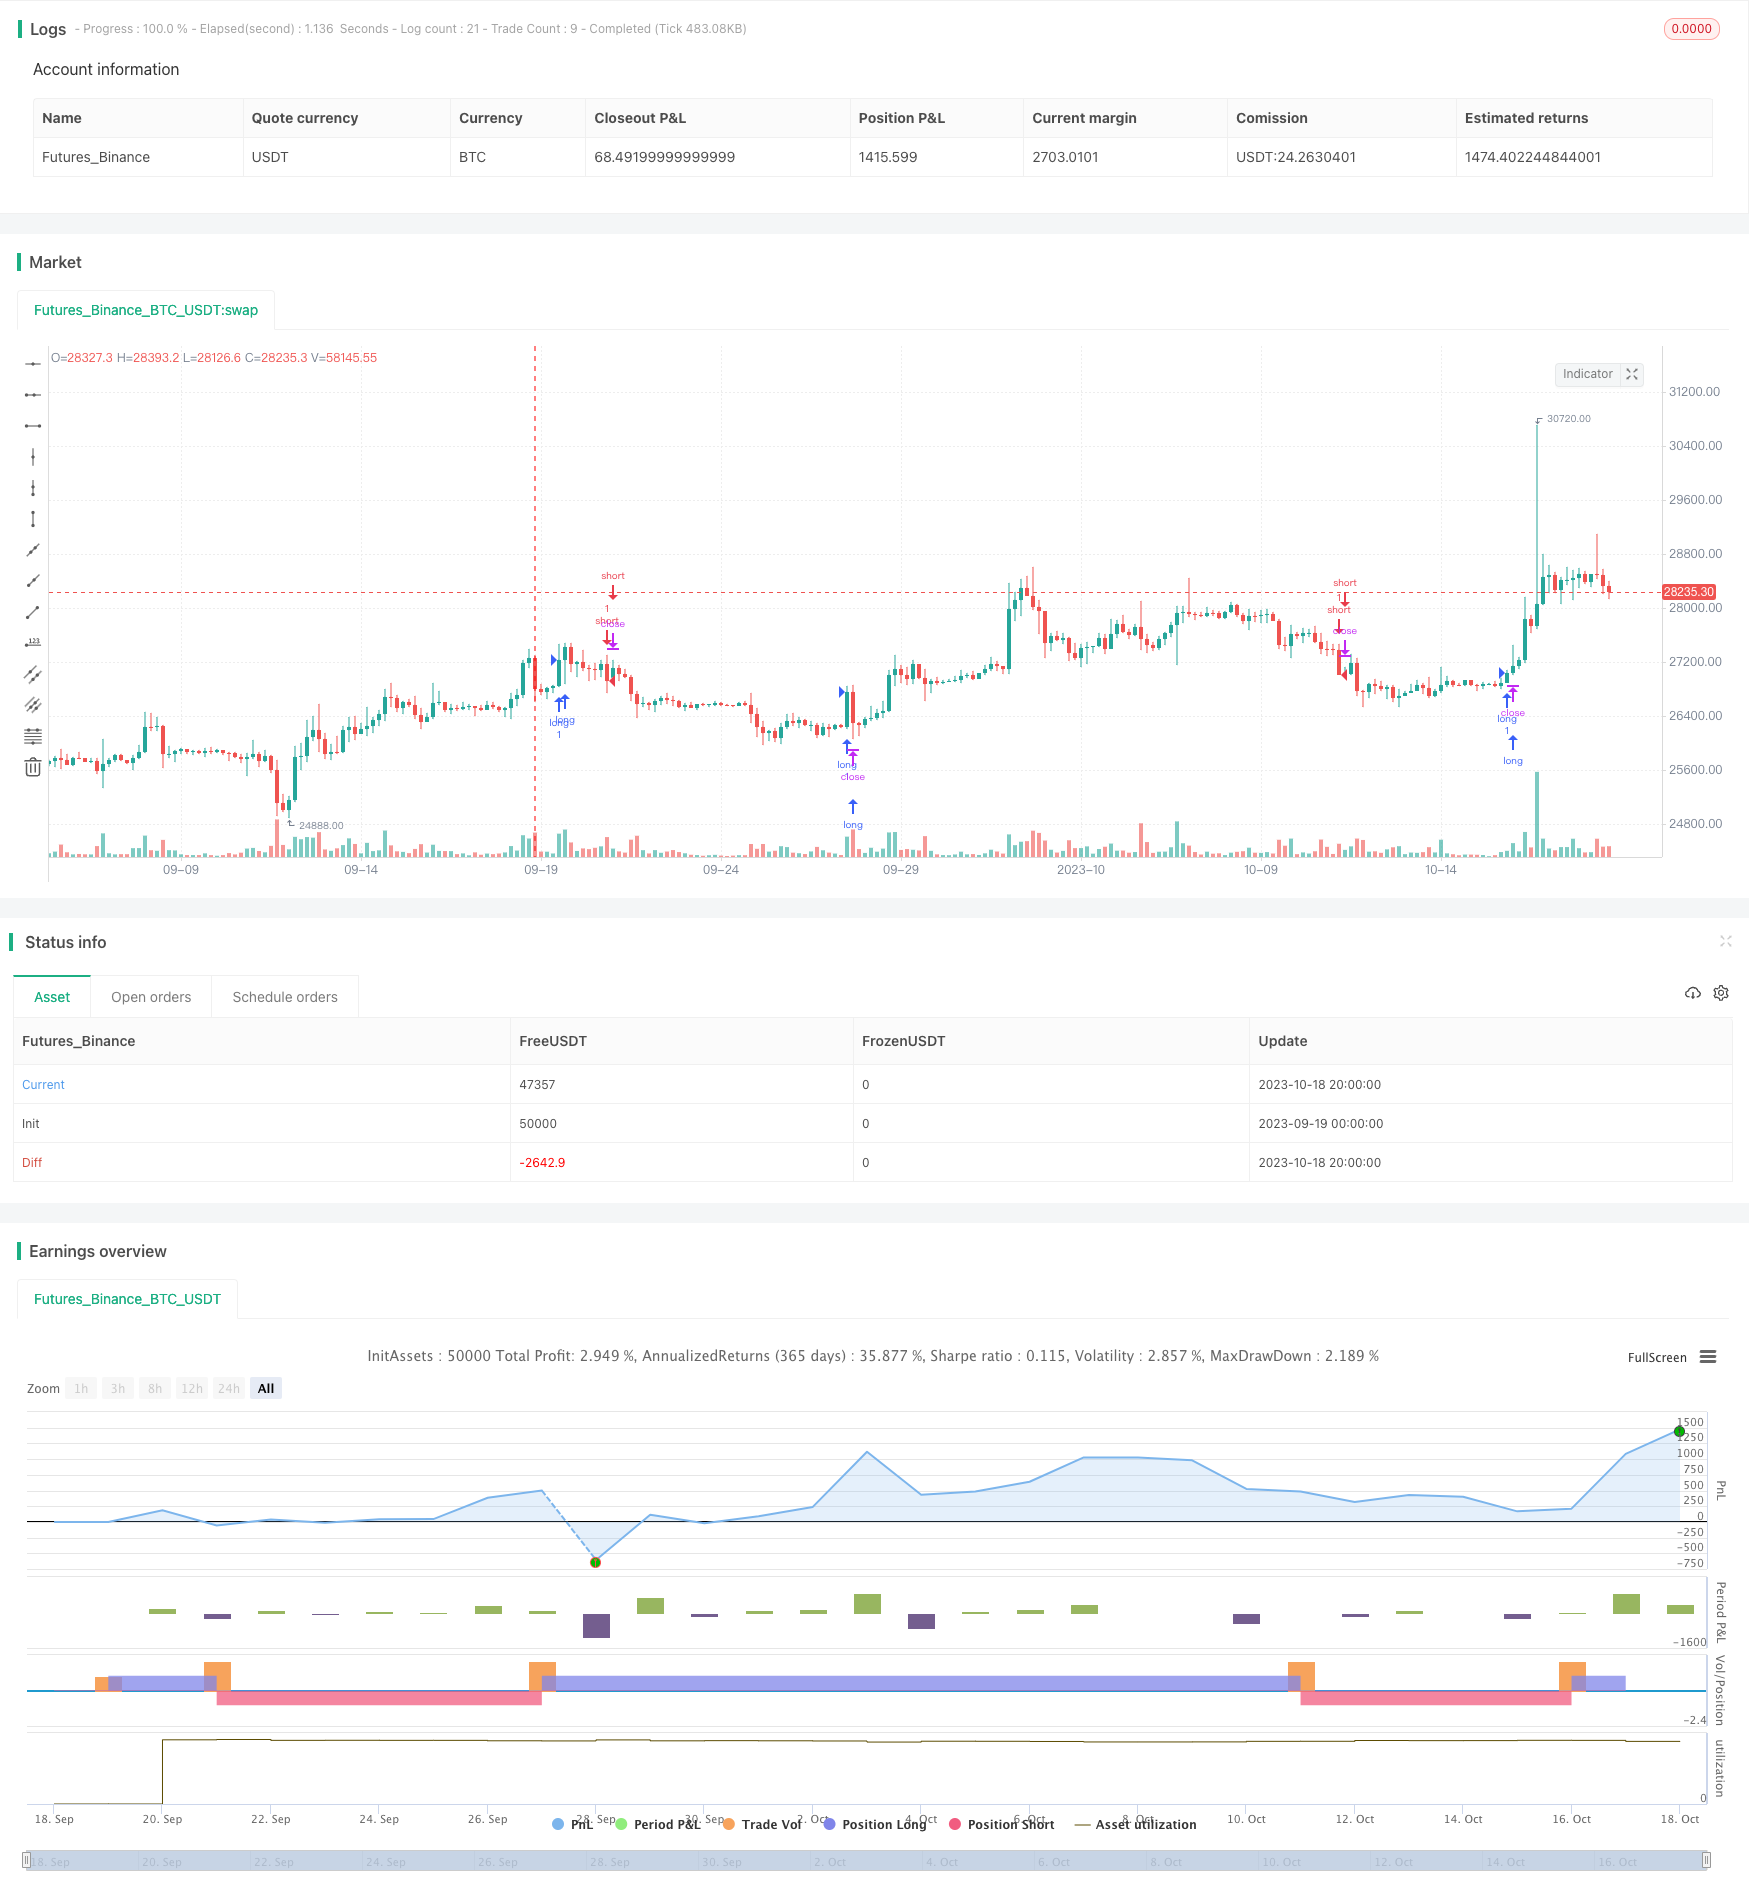
Overview
The Gold VWAP MACD SMO trading strategy is a complete strategy designed for the gold market using a 12-hour timeframe chart. It combines VWAP monthly, SMO oscillator and MACD histogram to identify trading opportunities in the gold market.
Strategy Logic
The strategy uses VWAP monthly as the main trend indicator. VWAP represents the average transaction price, and monthly means the time range for calculating VWAP is the past month. If the current close is above the VWAP monthly, it indicates the current uptrend; if the close is below the VWAP monthly, it means the trend is down.
The SMO oscillator is used to determine the current overbought and oversold situation. It consists of a long cycle component and a short cycle component. When the oscillator is above 0, it indicates overbought conditions, and when below 0, it represents oversold.
The MACD histogram can determine the momentum direction. When the column breaks up, it represents the momentum is strengthening for going long; when the column breaks down, it means the momentum is weakening to consider going short.
According to these three indicators, the specific rules of the trading strategy can be established:
Long entry: when close is above VWAP monthly, MACD histogram breaks up, and SMO oscillator is above 0. Short entry: when close is below VWAP monthly, MACD histogram breaks down, and SMO oscillator is below 0.
Take profit and stop loss are set based on the input percentages.
Advantage Analysis
The strategy combines multiple timeframes and indicators to effectively determine the trend direction and strength, with the following advantages:
- VWAP monthly can determine the primary trend direction to avoid counter trend trading.
- MACD histogram can capture momentum changes in a timely manner.
- SMO oscillator judges overbought and oversold conditions, which is helpful to enter at potential reversal points.
- Multiple indicators combination can verify each other and improve signal reliability.
- Customizable take profit and stop loss percentages to control risks.
Risk Analysis
Although the strategy is designed reasonably, there are still some risks to note:
- VWAP is sensitive to whipsaws, which may generate wrong signals.
- Improper MACD parameters setting increases the probability of false breakouts.
- Improper SMO parameters may also lead to misjudgement of overbought and oversold zones.
- Excessive wide take profit and stop loss settings cannot effectively control single loss.
To control the above risks, VWAP and MACD parameters should be optimized reasonably without too wide ranges. Also, take profit and stop loss percentages should not be too high, and single loss should be controlled around 3%.
Optimization Directions
The strategy can also be optimized in the following aspects:
- Add volume confirmation, such as volume breakout of MA.
- Incorporate volatility indicators like ATR to adjust position sizing based on market volatility.
- Add lighten mechanism at high levels to avoid missing profits.
- Test different take profit and stop loss strategies, like trailing stop loss, adaptive stop loss etc.
- Add model verification module to filter abnormal signals.
Conclusion
The Gold VWAP MACD SMO strategy combines multiple indicators to determine the trend and overbought/oversold conditions, which can effectively capture medium-to-long term opportunities in gold. Although there are some risks, they can be controlled through parameter optimization and risk management. The strategy has very strong scalability and can be optimized modularly based on actual needs. It is a trading system worthy of long-term tracking.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_low | 0 | source: low | high | close | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 12 | Fast Length |
| v_input_3 | 26 | Slow Length |
| v_input_4_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_5 | 9 | Signal Smoothing |
| v_input_6 | 22 | Long Length SMO |
| v_input_7 | 6 | Short Length SMO |
| v_input_8 | 5 | Signal Line Length SMO |
| v_input_9 | 0.085 | Take profit % for long |
| v_input_10 | 0.03 | Stop loss % for long |
| v_input_11 | 0.05 | Take profit % for short |
| v_input_12 | 0.025 | Stop loss % for short |
Source Pine Script
/*backtest
start: 2023-09-19 00:00:00
end: 2023-10-19 00:00:00
period: 4h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © exlux99

//@version=4
// strategy("VWAP Gold strategy", overlay = true, default_qty_type = strategy.percent_of_equity, default_qty_value = 10000, calc_on_every_tick = true, commission_type = strategy.commission.percent, commission_value = 0.005)


source = input(low)


//vwap monthly
timeframeM = time("M")
beginningM = na(timeframeM[1]) or timeframeM > timeframeM[1]

sumsourceM = source * volume
sumVolM = volume
sumsourceM := beginningM ? sumsourceM : sumsourceM + sumsourceM[1]
sumVolM := beginningM ? sumVolM : sumVolM + sumVolM[1]
vwapMonthly= sumsourceM / sumVolM

//macd
fast_length = input(title="Fast Length", type=input.integer, defval=12)
slow_length = input(title="Slow Length", type=input.integer, defval=26)
src = input(title="Source", type=input.source, defval=close)
signal_length = input(title="Signal Smoothing", type=input.integer, minval = 1, maxval = 50, defval = 9)


fast_ma = ema(src, fast_length)
slow_ma = ema(src, slow_length)
macd = fast_ma - slow_ma
signal =  ema(macd, signal_length)
hist = macd - signal


//SMO
longlen = input(22, minval=1, title="Long Length SMO")
shortlen = input(6, minval=1, title="Short Length SMO")
siglen = input(5, minval=1, title="Signal Line Length SMO")
erg = tsi(close, shortlen, longlen)
sig = ema(erg, siglen)
osc = erg - sig


shortCondition =  close < vwapMonthly and hist < hist[1] and osc < 0
longCondition =  close > vwapMonthly and hist> hist[1] and osc > 0

tplong=input(0.085, step=0.005, title="Take profit % for long")
sllong=input(0.03, step=0.005, title="Stop loss % for long")
tpshort=input(0.05, step=0.005, title="Take profit % for short")
slshort=input(0.025, step=0.005, title="Stop loss % for short")

strategy.entry("long",1,when=longCondition)
strategy.entry("short",0,when=shortCondition)

strategy.exit("short_tp/sl", "long", profit=close * tplong / syminfo.mintick, loss=close * sllong / syminfo.mintick, comment='LONG EXIT',  alert_message = 'closeshort')
strategy.exit("short_tp/sl", "short", profit=close * tpshort / syminfo.mintick, loss=close * slshort / syminfo.mintick, comment='SHORT EXIT',  alert_message = 'closeshort')
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Gold-VWAP-MACD-SMO-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Cross Timeframe SuperTrend Breakout StrategyPine Script · Breakout · 1h
- Trend Following Strategy Based on Moving Average BreakoutPine Script · Breakout · 1h
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h
- Dual Moving Average Breakthrough StrategyPine Script · Breakout · 1d
- EMA MACD Quantitative Strategy With Dual Track Running and Leading the Market IndexPine Script · Breakout · 1d