Strategy vault / Trend following
Golden Cross Uptrend Tracking Strategy
This strategy is designed based on the golden cross principle of moving averages. Specifically, it uses two simple moving averages of different periods, namely the 50-period line and the 200-period line. When the…
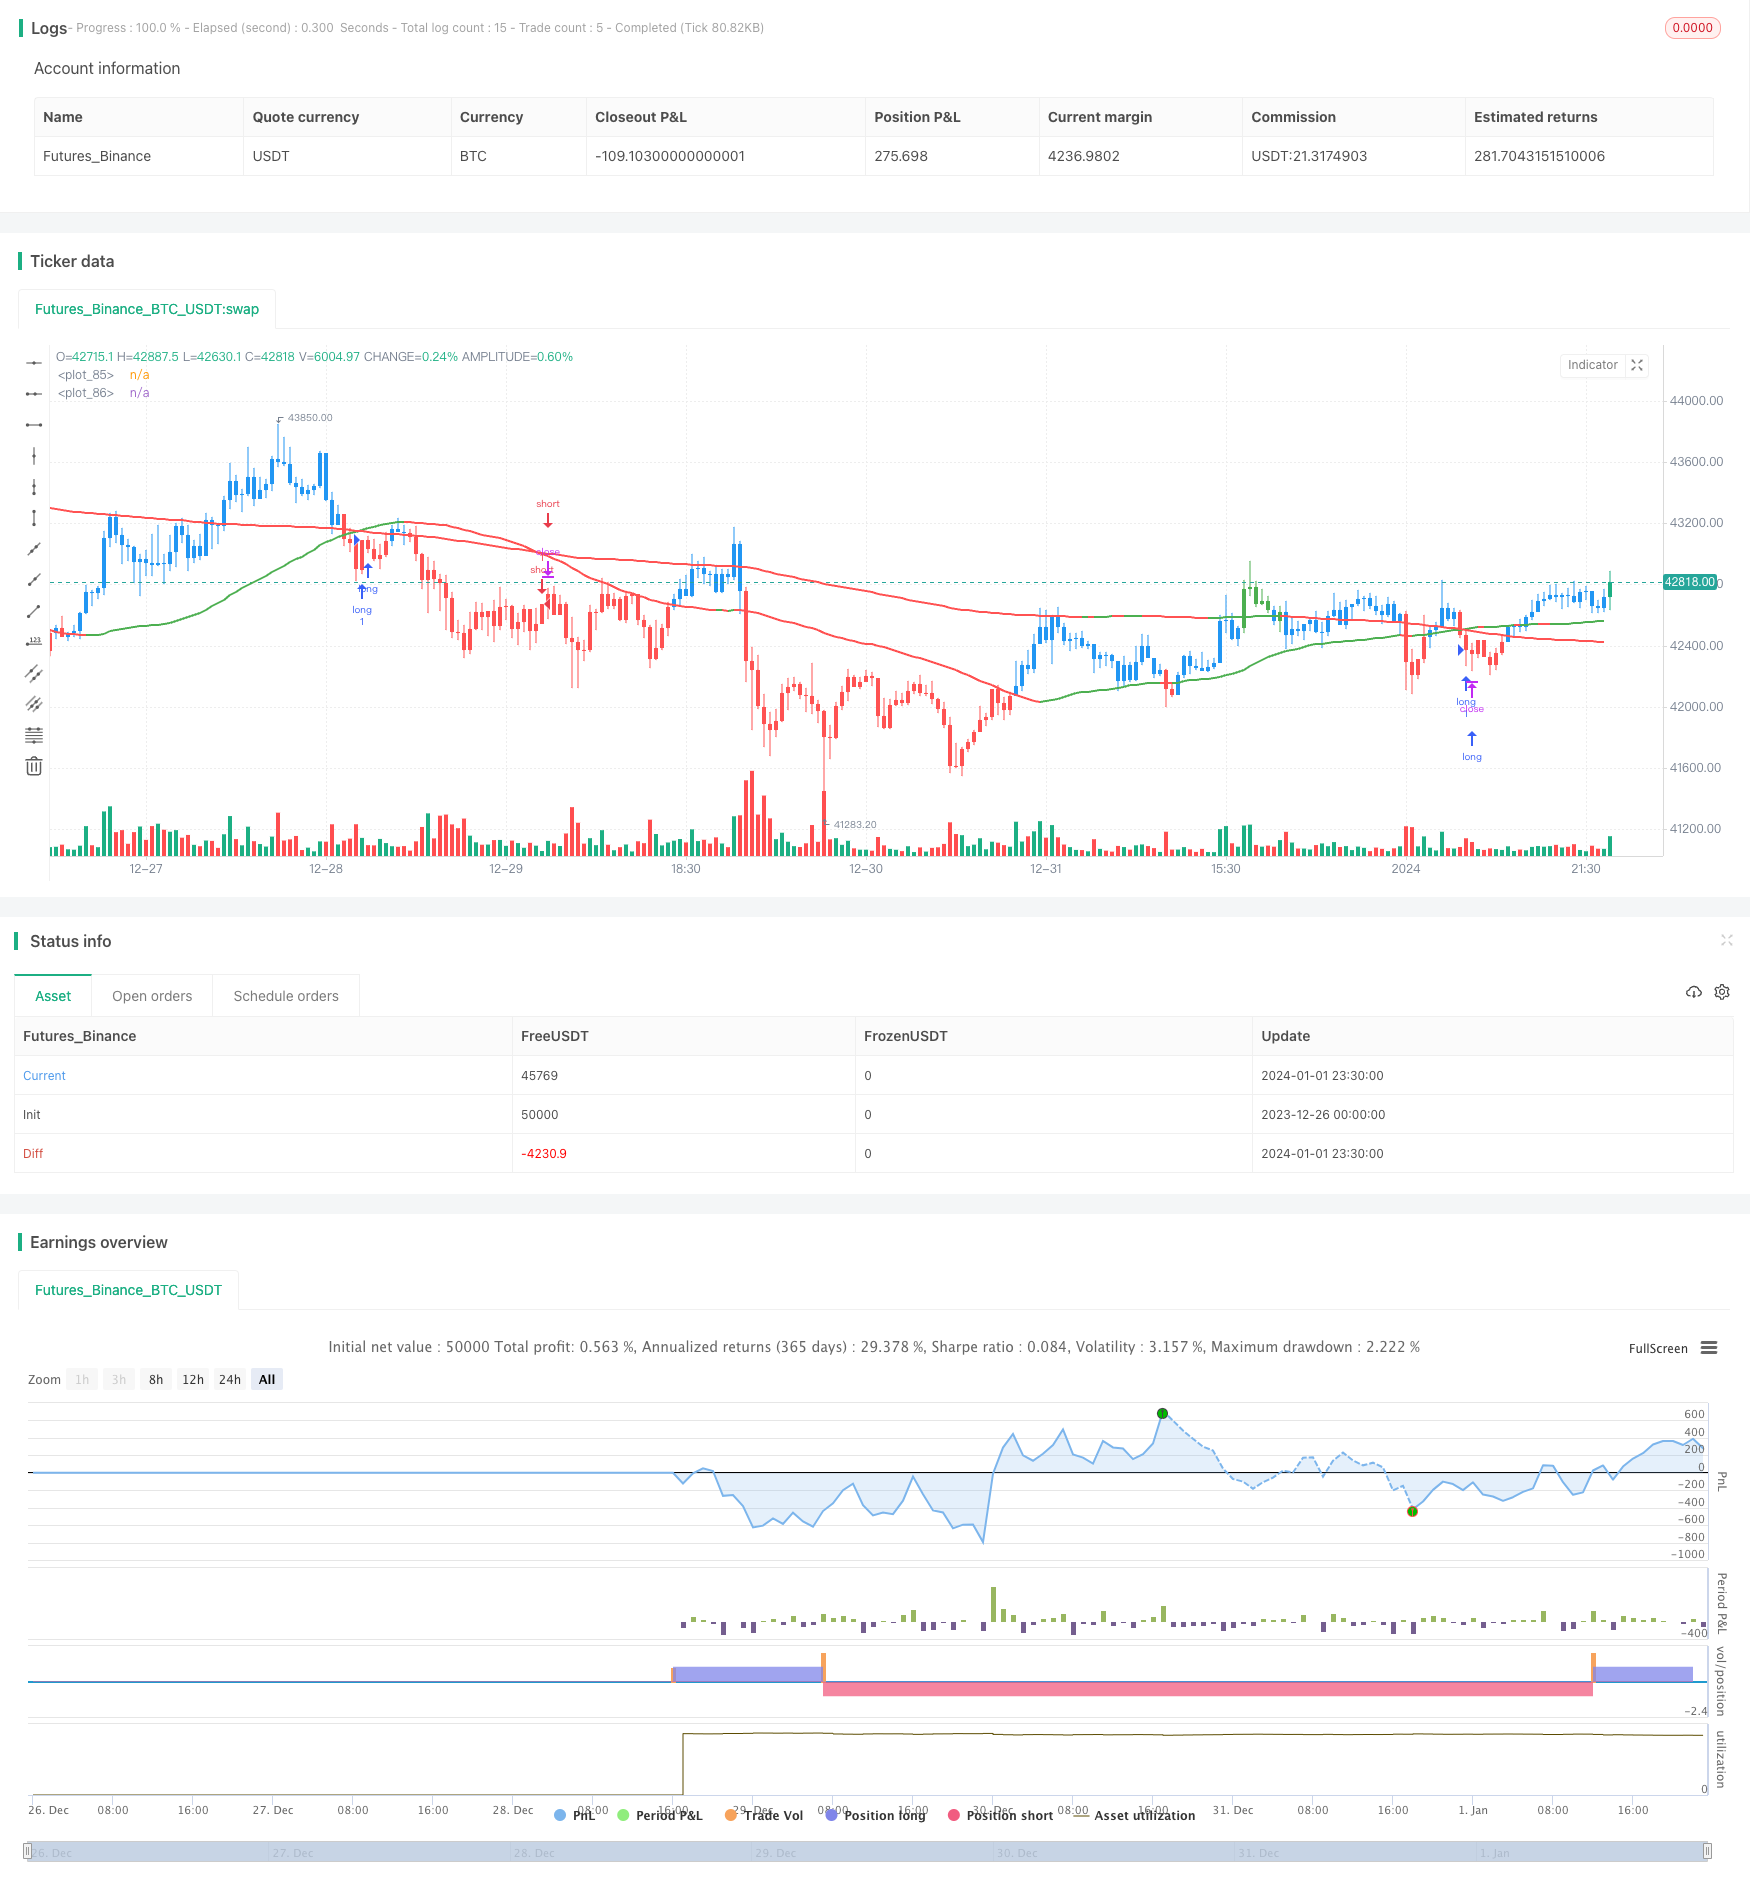
Overview
This strategy is designed based on the golden cross principle of moving averages. Specifically, it uses two simple moving averages of different periods, namely the 50-period line and the 200-period line. When the 50-period line breaks through the 200-period line from below, a buy signal is generated. When the 50-period line breaks through the 200-period line from above, a sell signal is generated.
Strategy Logic
The strategy is written in Pine Script language, with main logic as follows:
- Calculate two SMAs: 50-period SMA and 200-period SMA
- Determine golden cross: when 50-period SMA crosses above 200-period SMA, go long
- Determine death cross: when 50-period SMA crosses below 200-period SMA, close position
The importance of using SMA indicator here is that it can effectively filter out market noise and capture long-term trends. When faster SMA line crosses above slower SMA line, it indicates the short-term uptrend momentum defeats the long-term downtrend, generating a buy signal.
Advantages
The strategy has the following advantages:
- Simple and easy-to-understand principle, easy to implement.
- Reasonable PARAMETERS settings, customizable two SMA periods, adaptable to different markets.
- Written in stable Pine language version, runs efficiently.
- Rich visual settings, easy to use.
Risks and Solutions
The strategy also has some risks:
False breakout may occur, generating wrong signals. Can adjust two SMA parameters to reduce false breakout probability.
Cannot respond to short-term market, only suitable for long-term investors. Can appropriately shorten fast SMA period.
Drawdown may be large. Can set stop loss, or properly adjust position management.
Optimization Directions
The strategy can be further optimized in following aspects:
Add other indicators for filtering, combining multiple buy/sell conditions to reduce false signals.
Add stop loss mechanism. Mandatory stop loss when price breaks certain level.
Optimize position management. Such as pyramiding along the trend, trailing stop loss etc. To control drawdown and pursue higher return.
Parameter optimization. Evaluate the impact of different parameters on return/risk ratio.
Conclusion
In general, this is a typical trend tracking strategy. It utilizes the advantage of SMA to simply and efficiently capture long-term trends. Can customize based on one's style and tuning space. Also need to notice existing deficiencies for further optimization and improvement.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 50 | Fast SMA Period |
| v_input_2 | 200 | Slow SMA Period |
| v_input_3 | 2019 | Backtest Start Year |
| v_input_4 | true | Backtest Start Month |
| v_input_5 | true | Backtest Start Day |
| v_input_6 | 2099 | Backtest Stop Year |
| v_input_7 | 12 | Backtest Stop Month |
| v_input_8 | 31 | Backtest Stop Day |
Source Pine Script
/*backtest
start: 2023-12-26 00:00:00
end: 2024-01-02 00:00:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// @version=4
//
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// www.tradingview.com/u/TradeFab/
// www.tradefab.com
// ___  __        __   __  __       __
//  |  |__)  /\  |  \ |__ |__  /\  |__)
//  |  |  \ /~~\ |__/ |__ |   /~~\ |__)
//
// DISCLAIMER: Futures, stocks and options trading involves substantial risk of loss
// and is not suitable for every investor. You are responsible for all the risks and
// financial resources you use and for the chosen trading system.
// Past performance is not indicative for future results. In making an investment decision,
// traders must rely on their own examination of the entity making the trading decisions!
//
// TradeFab's Golden Cross Strategy.
// The strategy goes long when the faster SMA 50 (the simple moving average of the last 50 bars) crosses
// above the SMA 200. Orders are closed when the SMA 50 crosses below SMA 200. The strategy does not short.
//
VERSION = "1.2"
// 1.2 FB 2020-02-09 converted to Pine version 4
// 1.1 FB 2017-01-15 added short trading
// 1.0 FB 2017-01-13 basic version using SMAs
//
strategy(
   title        = "TFs Golden Cross " + VERSION,
   shorttitle   = "TFs Golden Cross " + VERSION,
   overlay      = true
   )


///////////////////////////////////////////////////////////
// === INPUTS ===
///////////////////////////////////////////////////////////
inFastSmaPeriod     = input(title="Fast SMA Period", type=input.integer, defval=50, minval=1)
inSlowSmaPeriod     = input(title="Slow SMA Period", type=input.integer, defval=200, minval=1)

// backtest period
testStartYear       = input(title="Backtest Start Year",    type=input.integer, defval=2019, minval=2000)
testStartMonth      = input(title="Backtest Start Month",   type=input.integer, defval=1, minval=1, maxval=12)
testStartDay        = input(title="Backtest Start Day",     type=input.integer, defval=1, minval=1, maxval=31)
testStopYear        = input(title="Backtest Stop Year",     type=input.integer, defval=2099, minval=2000)
testStopMonth       = input(title="Backtest Stop Month",    type=input.integer, defval=12, minval=1, maxval=12)
testStopDay         = input(title="Backtest Stop Day",      type=input.integer, defval=31, minval=1, maxval=31)


///////////////////////////////////////////////////////////
// === LOGIC ===
///////////////////////////////////////////////////////////
smaFast = sma(close, inFastSmaPeriod)
smaSlow = sma(close, inSlowSmaPeriod)

bullishCross = crossover (smaFast, smaSlow)
bearishCross = crossunder(smaFast, smaSlow)

// detect valid backtest period
isTestPeriod() => true


///////////////////////////////////////////////////////////
// === POSITION EXECUTION ===
///////////////////////////////////////////////////////////
strategy.entry("long",  strategy.long,  when=bullishCross)
strategy.entry("short", strategy.short, when=bearishCross)


///////////////////////////////////////////////////////////
// === PLOTTING ===
///////////////////////////////////////////////////////////
// background color
nopColor = color.new(color.gray, 50)
bgcolor(not isTestPeriod() ? nopColor : na)

bartrendcolor =
   close > smaFast and
   close > smaSlow and
   change(smaSlow) > 0
       ? color.green
       : close < smaFast and
         close < smaSlow and
         change(smaSlow) < 0
             ? color.red
             : color.blue
barcolor(bartrendcolor)
plot(smaFast, color=change(smaFast) > 0 ? color.green : color.red, linewidth=2)
plot(smaSlow, color=change(smaSlow) > 0 ? color.green : color.red, linewidth=2)

// label
posColor = color.new(color.green, 75)
negColor = color.new(color.red, 75)
dftColor = color.new(color.blue, 75)
posProfit= (strategy.position_size != 0) ? (close * 100 / strategy.position_avg_price - 100) : 0.0
posDir   = (strategy.position_size  > 0) ? "long" : strategy.position_size < 0 ? "short" : "flat"
posCol   = (posProfit > 0) ? posColor : (posProfit < 0) ? negColor : dftColor

var label lb = na
label.delete(lb)
lb := label.new(bar_index, max(high, highest(5)[1]),
   color=posCol,
   text="Pos: "+ posDir +
      "\nPnL: "+tostring(posProfit, "#.##")+"%" +
      "\nClose: "+tostring(close, "#.##"))
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-03. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Golden-Cross-Uptrend-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m