Grid Strategy with Moving Average Lines
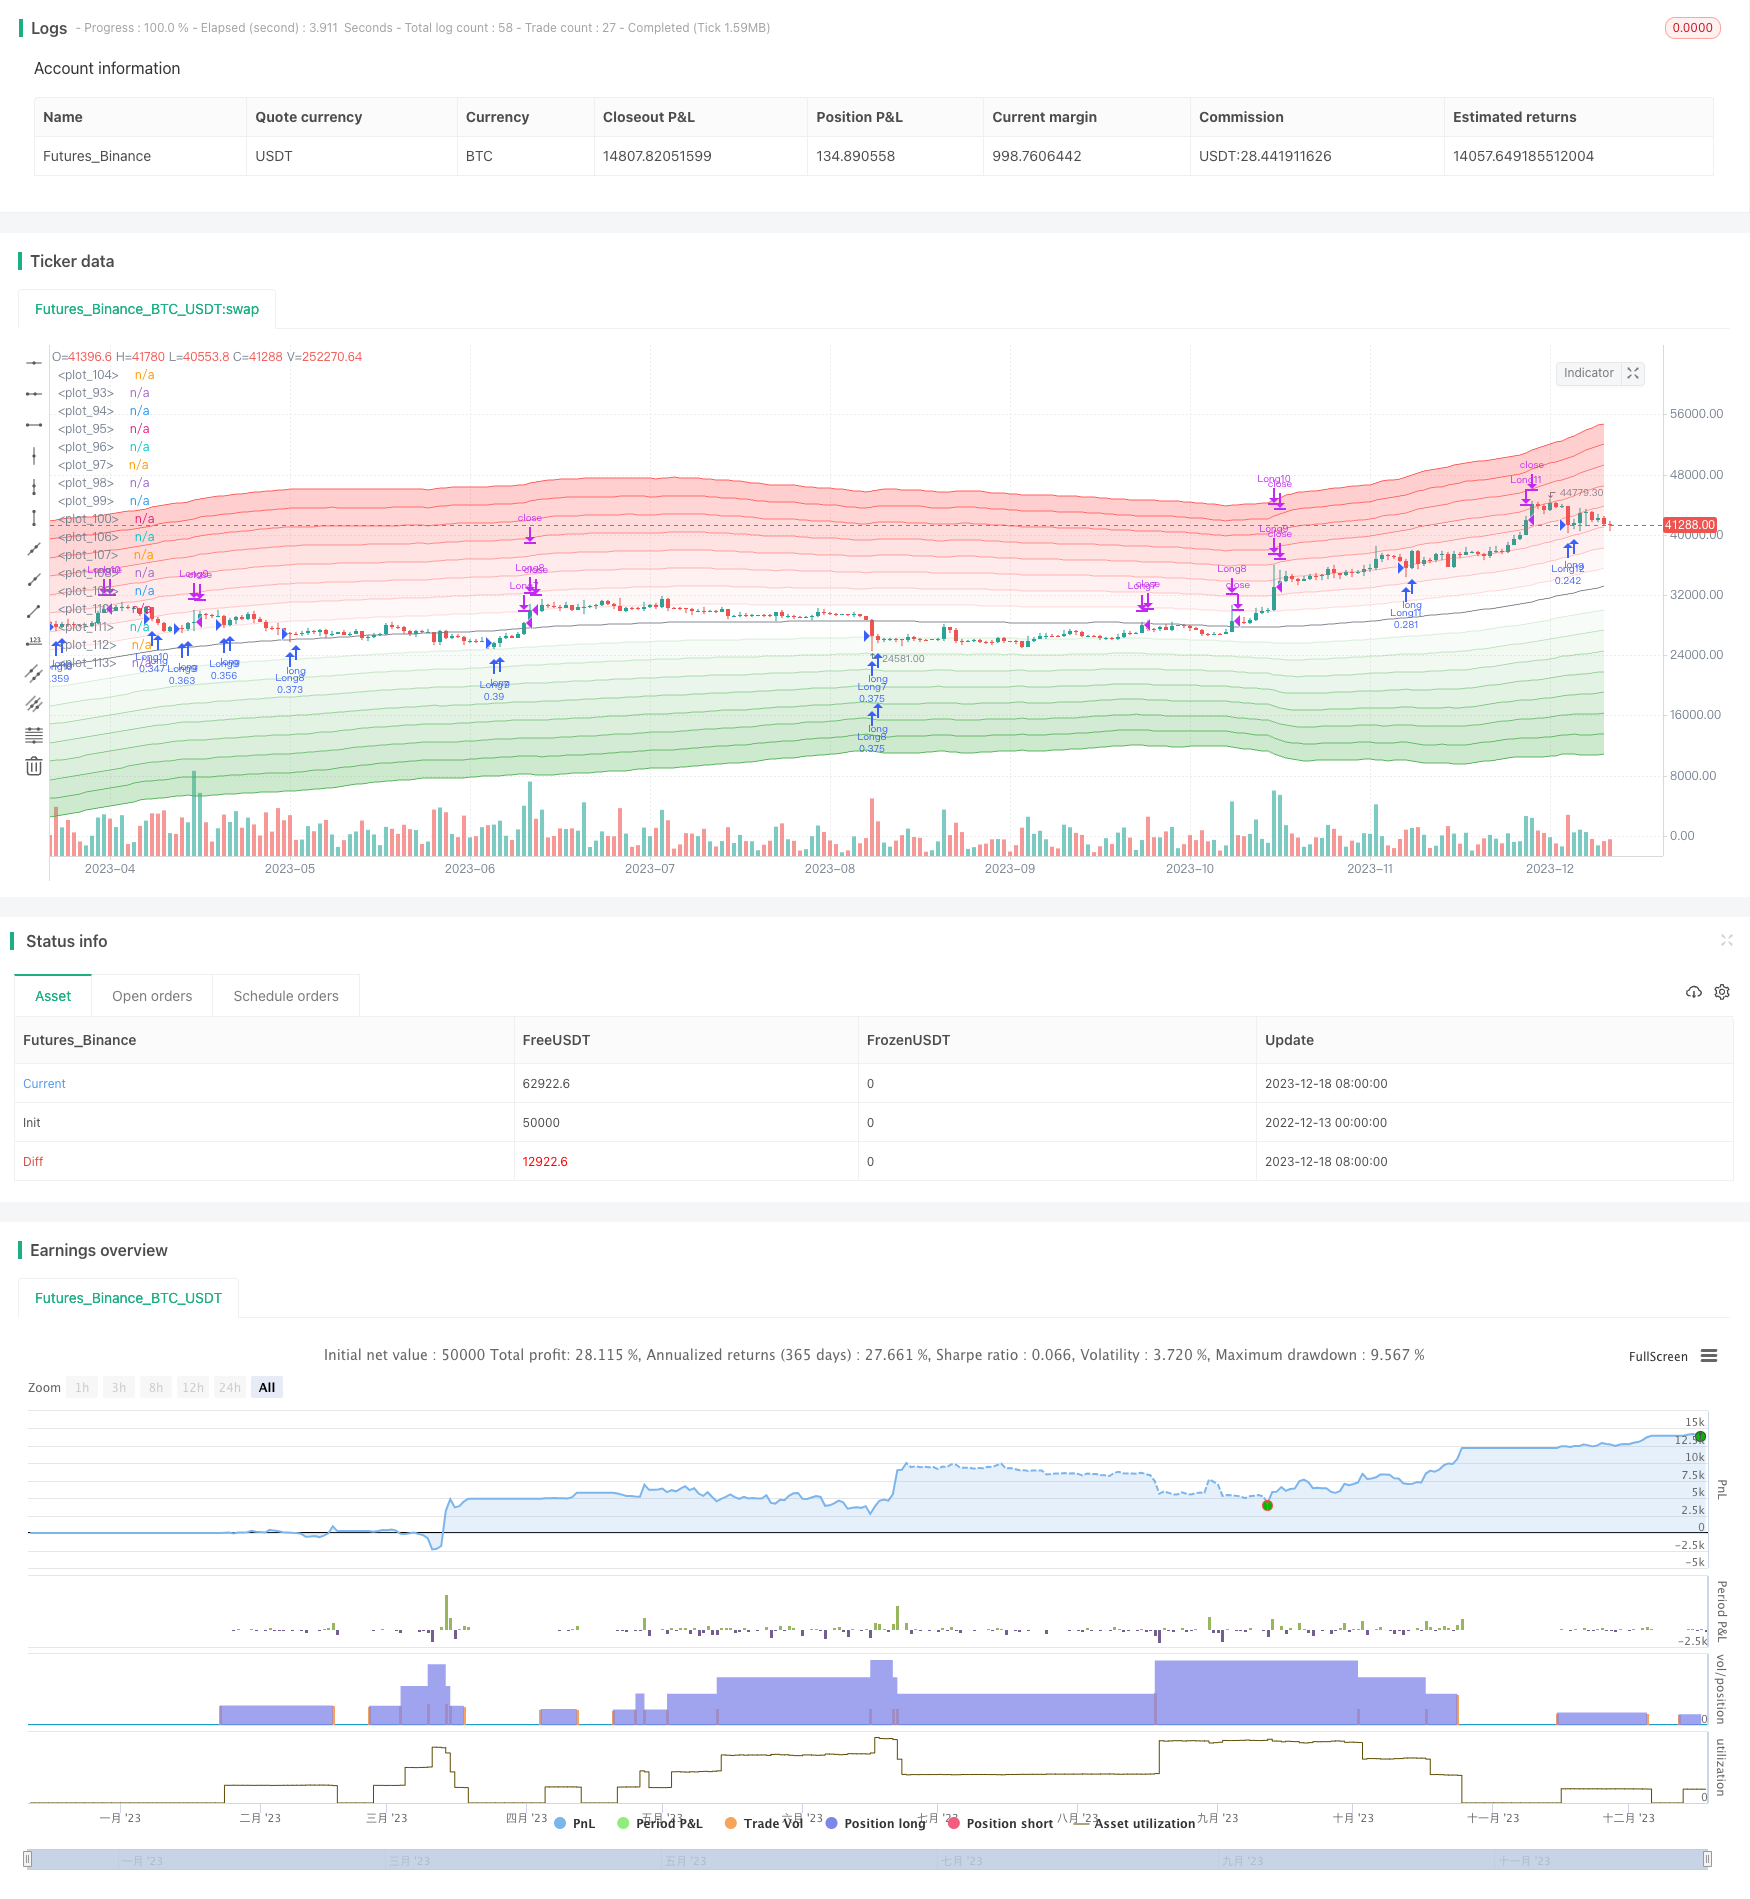
This is a grid trading strategy that utilizes moving average lines dynamically. It draws multiple buy and sell zones above and below the moving average line based on settings of the MA and volatility range. When…
Overview
This is a grid trading strategy that utilizes moving average lines dynamically. It draws multiple buy and sell zones above and below the moving average line based on settings of the MA and volatility range. When price drops into different buy zones, corresponding long orders will be opened. When price goes back into sell zones, opened orders will be closed sequentially. Thus forms a dynamic grid trading mechanism.
Strategy Logic
- Users set parameters for determining major moving average line;
- Multiple buy and sell zones are divided based on ATR and settings;
- When price drops into different buying zones, corresponding long orders are triggered;
- When price moves back into sell zones, orders are closed sequentially;
- A dynamic grid trading system is formed eventually.
Advantages
- Using MA line to determine trend direction avoids trading against major trend;
- ATR parameter considers market volatility, making grid more dynamic;
- Opening orders in batches controls risks;
- Closing orders sequentially avoids cascade stop loss;
- Simple parameters, easy to operate.
Risks
- Significant fluctuation may frequently trigger grid losses;
- In strong trends, stop loss points could be too close leading to quick post-pullback stops;
- Increased transactions from multiple entries produce higher commission fees;
- Not suitable for range-bound or trendless markets.
Risks can be reduced by relaxing grid interval, optimizing ATR parameter, reducing order quantities etc. Different parameter sets could also be used for trending and ranging scenarios.
Optimization Directions
- Spot index indicators can be added to determine bullish/bearish bias;
- Quantitative indicators can be used to select assets with trend characteristics;
- ATR parameters or grid intervals can be adjusted dynamically based on volatility;
- Profit taking mechanism can be added to follow trends.
These further optimizations will make the strategy more dynamic and locally enhanced.
Conclusion
In conclusion, this is an overall mature and simple trend-following grid strategy. It uses moving averages to determine major trends, and establishes dynamic grid mechanism for batched trades. Has certain risk control capabilities. With further quant optimizations, it can become a very practical quant tool.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_string_2 | 0 | Grid Logic: ATR | Percent |
| v_input_int_1 | 100 | (?MA)MA Length |
| v_input_string_1 | 0 | MA Type: SMA | HMA | LSMA | RMA | EMA | WMA |
| v_input_float_1 | 2.5 | (?Parameter)Band Multiplier/Percent |
| v_input_int_2 | 100 | (?parameter)ATR Length |
Source Pine Script
/*backtest
start: 2022-12-13 00:00:00
end: 2023-12-19 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Seungdori_

//@version=5
strategy("Grid Strategy with MA", overlay=true, initial_capital = 100000, default_qty_type = strategy.cash, default_qty_value = 10000, pyramiding = 10, process_orders_on_close = true, commission_type = strategy.commission.percent, commission_value = 0.04)


//Inputs//

length = input.int(defval = 100, title = 'MA Length', group = 'MA')
MA_Type = input.string("SMA", title="MA Type", options=['EMA', 'HMA', 'LSMA', 'RMA', 'SMA', 'WMA'],group = 'MA')

logic = input.string(defval='ATR', title ='Grid Logic', options = ['ATR', 'Percent'])

band_mult = input.float(2.5, step = 0.1, title = 'Band Multiplier/Percent', group = 'Parameter')
atr_len = input.int(defval=100, title = 'ATR Length', group ='parameter')
//Var//

var int order_cond = 0
var bool order_1 = false
var bool order_2 = false
var bool order_3 = false
var bool order_4 = false
var bool order_5 = false
var bool order_6 = false
var bool order_7 = false
var bool order_8 = false
var bool order_9 = false
var bool order_10 = false
var bool order_11 = false
var bool order_12 = false
var bool order_13 = false
var bool order_14 = false
var bool order_15 = false


/////////////////////
//Region : Function//
/////////////////////
getMA(source ,ma_type, length) =>
    maPrice = ta.ema(source, length)
    ema = ta.ema(source, length)
    sma = ta.sma(source, length)
    if ma_type == 'SMA'
        maPrice := ta.sma(source, length)
        maPrice
    if ma_type == 'HMA'
        maPrice := ta.hma(source, length)
        maPrice
    if ma_type == 'WMA'
        maPrice := ta.wma(source, length)
        maPrice
    if ma_type == "RMA"
        maPrice := ta.rma(source, length)
    if ma_type == "LSMA"
        maPrice := ta.linreg(source, length, 0)
    maPrice

main_plot = getMA(ohlc4, MA_Type, length)


atr = ta.atr(length)

premium_zone_1 = logic == 'ATR' ? ta.ema(main_plot + atr*(band_mult*1), 5) : ta.ema((main_plot*(1+band_mult*0.01*1)), 5)
premium_zone_2 = logic == 'ATR' ? ta.ema(main_plot + atr*(band_mult*2), 5) : ta.ema((main_plot*(1+band_mult*0.01*2)), 5)
premium_zone_3 = logic == 'ATR' ? ta.ema(main_plot + atr*(band_mult*3), 5) : ta.ema((main_plot*(1+band_mult*0.01*3)), 5)
premium_zone_4 = logic == 'ATR' ? ta.ema(main_plot + atr*(band_mult*4), 5) : ta.ema((main_plot*(1+band_mult*0.01*4)), 5)
premium_zone_5 = logic == 'ATR' ? ta.ema(main_plot + atr*(band_mult*5), 5) : ta.ema((main_plot*(1+band_mult*0.01*5)), 5)
premium_zone_6 = logic == 'ATR' ? ta.ema(main_plot + atr*(band_mult*6), 5) : ta.ema((main_plot*(1+band_mult*0.01*6)), 5)
premium_zone_7 = logic == 'ATR' ? ta.ema(main_plot + atr*(band_mult*7), 5) : ta.ema((main_plot*(1+band_mult*0.01*7)), 5)
premium_zone_8 = logic == 'ATR' ? ta.ema(main_plot + atr*(band_mult*8), 5) : ta.ema((main_plot*(1+band_mult*0.01*8)), 5)
//premium_zone_9 = ta.rma(main_plot + atr*(band_mult*9), 5)
//premium_zone_10 = ta.rma(main_plot + atr*(band_mult*10), 5)


discount_zone_1 = logic == 'ATR' ? ta.ema(main_plot - atr*(band_mult*1), 5) : ta.ema((main_plot*(1-band_mult*0.01*1)), 5)
discount_zone_2 = logic == 'ATR' ? ta.ema(main_plot - atr*(band_mult*2), 5) : ta.ema((main_plot*(1-band_mult*0.01*2)), 5)
discount_zone_3 = logic == 'ATR' ? ta.ema(main_plot - atr*(band_mult*3), 5) : ta.ema((main_plot*(1-band_mult*0.01*3)), 5)
discount_zone_4 = logic == 'ATR' ? ta.ema(main_plot - atr*(band_mult*4), 5) : ta.ema((main_plot*(1-band_mult*0.01*4)), 5)
discount_zone_5 = logic == 'ATR' ? ta.ema(main_plot - atr*(band_mult*5), 5) : ta.ema((main_plot*(1-band_mult*0.01*5)), 5)
discount_zone_6 = logic == 'ATR' ? ta.ema(main_plot - atr*(band_mult*6), 5) : ta.ema((main_plot*(1-band_mult*0.01*6)), 5)
discount_zone_7 = logic == 'ATR' ? ta.ema(main_plot - atr*(band_mult*7), 5) : ta.ema((main_plot*(1-band_mult*0.01*7)), 5)
discount_zone_8 = logic == 'ATR' ? ta.ema(main_plot - atr*(band_mult*8), 5) : ta.ema((main_plot*(1-band_mult*0.01*8)), 5)
//discount_zon_9 = ta.sma(main_plot - atr*(band_mult*9), 5)
//discount_zone_10 =ta.sma( main_plot - atr*(band_mult*10), 5)

//Region End//

////////////////////
// Region : Plots//
///////////////////

dis_low1 = plot(discount_zone_1, color=color.new(color.green, 80))
dis_low2 = plot(discount_zone_2, color=color.new(color.green, 70))
dis_low3 = plot(discount_zone_3, color=color.new(color.green, 60))
dis_low4 = plot(discount_zone_4, color=color.new(color.green, 50))
dis_low5 = plot(discount_zone_5, color=color.new(color.green, 40))
dis_low6 = plot(discount_zone_6, color=color.new(color.green, 30))
dis_low7 = plot(discount_zone_7, color=color.new(color.green, 20))
dis_low8 = plot(discount_zone_8, color=color.new(color.green, 10))
//dis_low9 = plot(discount_zone_9, color=color.new(color.green, 0))
//dis_low10 = plot(discount_zone_10, color=color.new(color.green, 0))

plot(main_plot, color =color.new(color.gray, 10))

pre_up1 = plot(premium_zone_1, color=color.new(color.red, 80))
pre_up2 = plot(premium_zone_2, color=color.new(color.red, 70))
pre_up3 = plot(premium_zone_3, color=color.new(color.red, 60))
pre_up4 = plot(premium_zone_4, color=color.new(color.red, 50))
pre_up5 = plot(premium_zone_5, color=color.new(color.red, 40))
pre_up6 = plot(premium_zone_6, color=color.new(color.red, 30))
pre_up7 = plot(premium_zone_7, color=color.new(color.red, 20))
pre_up8 = plot(premium_zone_8, color=color.new(color.red, 10))
//pre_up9 = plot(premium_zone_9, color=color.new(color.red, 0))
//pre_up10 = plot(premium_zone_10, color=color.new(color.red, 0))

fill(dis_low1, dis_low2, color=color.new(color.green, 95))
fill(dis_low2, dis_low3, color=color.new(color.green, 90))
fill(dis_low3, dis_low4, color=color.new(color.green, 85))
fill(dis_low4, dis_low5, color=color.new(color.green, 80))
fill(dis_low5, dis_low6, color=color.new(color.green, 75))
fill(dis_low6, dis_low7, color=color.new(color.green, 70))
fill(dis_low7, dis_low8, color=color.new(color.green, 65))
//fill(dis_low8, dis_low9, color=color.new(color.green, 60))
//fill(dis_low9, dis_low10, color=color.new(color.green, 55))

fill(pre_up1, pre_up2, color=color.new(color.red, 95))
fill(pre_up2, pre_up3, color=color.new(color.red, 90))
fill(pre_up3, pre_up4, color=color.new(color.red, 85))
fill(pre_up4, pre_up5, color=color.new(color.red, 80))
fill(pre_up5, pre_up6, color=color.new(color.red, 75))
fill(pre_up6, pre_up7, color=color.new(color.red, 70))
fill(pre_up7, pre_up8, color=color.new(color.red, 65))
//fill(pre_up8, pre_up9, color=color.new(color.red, 60))
//fill(pre_up9, pre_up10, color=color.new(color.red, 55))


//Region End//

///////////////////////
//Region : Strategies//
///////////////////////

//Longs//

longCondition1 = ta.crossunder(low, discount_zone_7)
longCondition2 = ta.crossunder(low, discount_zone_6)
longCondition3 = ta.crossunder(low, discount_zone_5)
longCondition4 = ta.crossunder(low, discount_zone_4)
longCondition5 = ta.crossunder(low, discount_zone_3)
longCondition6 = ta.crossunder(low, discount_zone_2)
longCondition7 = ta.crossunder(low, discount_zone_1)
longCondition8 = ta.crossunder(low, main_plot)
longCondition9 = ta.crossunder(low, premium_zone_1)
longCondition10 = ta.crossunder(low, premium_zone_2)
longCondition11 = ta.crossunder(low, premium_zone_3)
longCondition12 = ta.crossunder(low, premium_zone_4)
longCondition13 = ta.crossunder(low, premium_zone_5)
longCondition14 = ta.crossunder(low, premium_zone_6)
longCondition15 = ta.crossunder(low, premium_zone_7)

if (longCondition1) and order_1 == false
    strategy.entry("Long1", strategy.long)
    order_1 := true
if (longCondition2) and order_2 == false
    strategy.entry("Long2", strategy.long)
    order_2 := true
if (longCondition3) and order_3 == false
    strategy.entry("Long3", strategy.long)
    order_3 := true
if (longCondition4) and order_4 == false
    strategy.entry("Long4", strategy.long)
    order_4 := true
if (longCondition5) and order_5 == false
    strategy.entry("Long5", strategy.long)
    order_5 := true
if (longCondition6) and order_6 == false
    strategy.entry("Long6", strategy.long)
    order_6 := true
if (longCondition7) and order_7 == false
    strategy.entry("Long7", strategy.long)
    order_7 := true
if (longCondition8) and order_8 == false
    strategy.entry("Long8", strategy.long)
    order_8 := true
if (longCondition9) and order_9 == false
    strategy.entry("Long9", strategy.long)
    order_9 := true
if (longCondition10) and order_10 == false
    strategy.entry("Long10", strategy.long)
    order_10 := true
if (longCondition11) and order_11 == false
    strategy.entry("Long11", strategy.long)
    order_11 := true
if (longCondition12) and order_12 == false
    strategy.entry("Long12", strategy.long)
    order_12 := true
if (longCondition13) and order_13 == false
    strategy.entry("Long13", strategy.long)
    order_13 := true
if (longCondition14) and order_14 == false
    strategy.entry("Long14", strategy.long)
    order_14 := true
if (longCondition15) and order_15 == false
    strategy.entry("Long14", strategy.long)
    order_15 := true

//Close//

shortCondition1 = ta.crossover(high, discount_zone_6)
shortCondition2 = ta.crossover(high, discount_zone_5)
shortCondition3 = ta.crossover(high, discount_zone_4)
shortCondition4 = ta.crossover(high, discount_zone_3)
shortCondition5 = ta.crossover(high, discount_zone_2)
shortCondition6 = ta.crossover(high, discount_zone_1)
shortCondition7 = ta.crossover(high, main_plot)
shortCondition8 = ta.crossover(high, premium_zone_1)
shortCondition9 = ta.crossover(high, premium_zone_2)
shortCondition10 = ta.crossover(high, premium_zone_3)
shortCondition11 = ta.crossover(high, premium_zone_4)
shortCondition12 = ta.crossover(high, premium_zone_5)
shortCondition13 = ta.crossover(high, premium_zone_6)
shortCondition14 = ta.crossover(high, premium_zone_7)
shortCondition15 = ta.crossover(high, premium_zone_8)

if (shortCondition1) and order_1 == true
    strategy.close("Long1")
    order_1 := false
if (shortCondition2) and order_2 == true
    strategy.close("Long2")
    order_2 := false
if (shortCondition3) and order_3 == true
    strategy.close("Long3")
    order_3 := false
if (shortCondition4) and order_4 == true
    strategy.close("Long4")
    order_4 := false
if (shortCondition5) and order_5 == true
    strategy.close("Long5")
    order_5 := false
if (shortCondition6) and order_6 == true
    strategy.close("Long6")
    order_6 := false
if (shortCondition7) and order_7 == true
    strategy.close("Long7")
    order_7 := false
if (shortCondition8) and order_8 == true
    strategy.close("Long8")
    order_8 := false
if (shortCondition9) and order_9 == true
    strategy.close("Long9")
    order_9 := false
if (shortCondition10) and order_10 == true
    strategy.close("Long10")
    order_10 := false
if (shortCondition11) and order_11 == true
    strategy.close("Long11")
    order_11 := false
if (shortCondition12) and order_12 == true
    strategy.close("Long12")
    order_12 := false
if (shortCondition13) and order_13 == true
    strategy.close("Long13")
    order_13 := false
if (shortCondition14) and order_14 == true
    strategy.close("Long14")
    order_14 := false
if (shortCondition15) and order_15 == true
    strategy.close("Long15")
    order_15 := false
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a grid bot with inventory caps and order deduplication from strategies/Grid-Strategy-with-Moving-Average-Lines.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Fibonacci Grid Tracking Trend StrategyPine Script · Grid · 1h
- Advanced Bollinger Band Moving Average Grid Trend Tracking StrategyPine Script · Grid · 1h
- Assassins Grid B A Dynamic Grid Trading StrategyPine Script · Grid · 1d
- Multi Zone MA100 Price Retracement Smart Grid Trading StrategyPine Script · Grid · 1d
- Short term Trading Strategy Based on SMA and EMAPine Script · Grid · 1d
- Profit Grid Strategy With OscillationPine Script · Grid · 1d