Strategy vault / Machine learning
High Low Cryptocurrency Strategy Based on Multiple Indicators
This strategy is a high/low level strategy suitable for cryptocurrency markets. It integrates MACD, PSAR, ATR, Elliott Wave and other multiple indicators for trading at higher timeframes like 1 hour, 4 hours or 1…
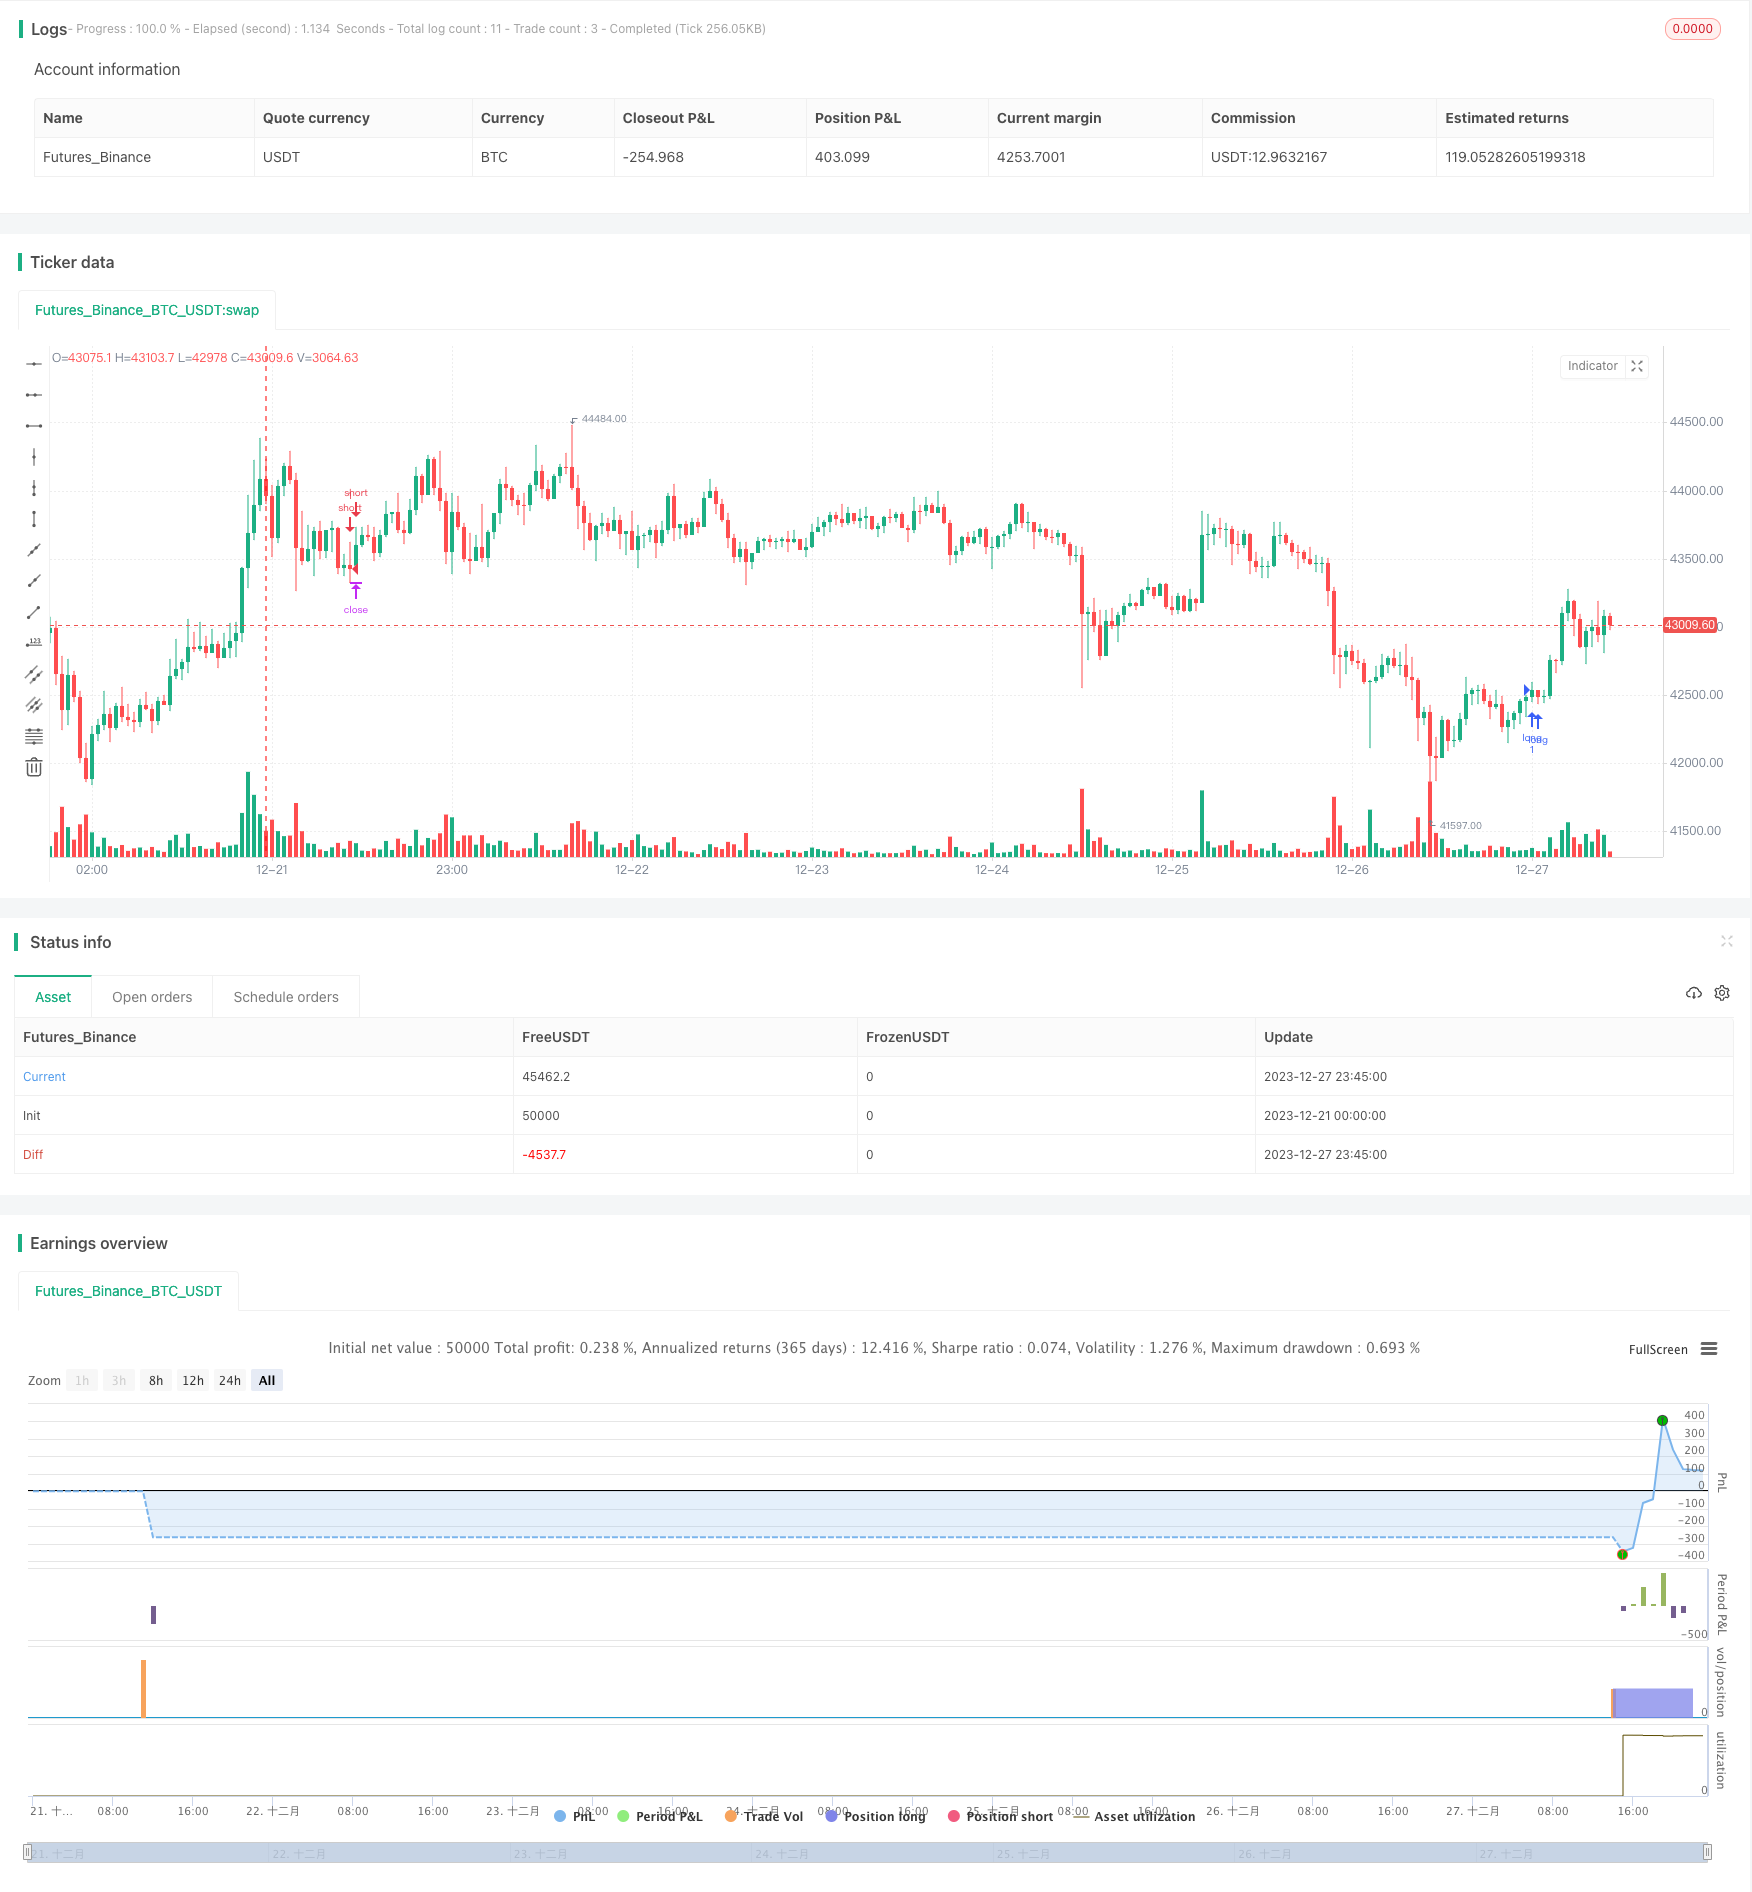
Overview
This strategy is a high/low level strategy suitable for cryptocurrency markets. It integrates MACD, PSAR, ATR, Elliott Wave and other multiple indicators for trading at higher timeframes like 1 hour, 4 hours or 1 day. The advantage of this strategy lies in the high risk reward ratio with average profit factor ranging from 1.5 to 2.5.
Strategy Logic
The trading signals of this strategy come from the price high/low levels and composite judgments of multiple indicators. The specific logic is:
Judge if there is a high/low level range formed by successive higher highs or lower lows on the price chart.
Check the histogram level of MACD.
Check PSAR indicator for trend direction.
Check trend direction based on ATR and MA.
Confirm trend direction with Elliott Wave indicator.
If all the 5 conditions point to the same direction, long or short signals are generated.
Advantages
High risk reward ratio up to 1:30.
High average profit factor, usually between 1.5-2.5.
Combination of multiple indicators helps filter false breakouts effectively.
Risks
Relatively low win rate around 10%-20%.
Potential drawdown and whipsaw risks exist.
Indicator performance could be impacted by market regimes.
Need decent psychological endurance.
Corresponding Measures:
Increase capital to balance the win rate.
Set strict stop loss for each trade.
Adjust parameters based on different markets.
Strengthen psychology and control position sizing.
Optimization Directions
Test parameters based on different cryptos and markets.
Add stop loss and take profit to optimize money management.
Increase win rate with machine learning methods.
Add social sentiment filter for trading signals.
Consider confirmation across multiple timeframes.
Conclusion
In conclusion, this is an aggressive high risk high return cryptocurrency trading strategy. Its advantage lies in the high risk reward ratio and profit factor. The main risks come from the relatively low win rate which requires strong psychology. The future optimization directions could be parameter tuning, money management, increasing win rate and so on. Overall this strategy has practical value for cryptocurrency traders seeking high profits.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 12 | Fast Length |
| v_input_2 | 26 | Slow Length |
| v_input_3_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_4 | 9 | Signal Smoothing |
| v_input_5 | true | Simple MA(Oscillator) |
| v_input_6 | false | Simple MA(Signal Line) |
| v_input_7 | 0.02 | start |
| v_input_8 | 0.02 | increment |
| v_input_9 | 0.2 | maximum |
| v_input_10 | 20 | CCI |
| v_input_11 | 5 | ATR |
| v_input_12 | true | ATR Multiplier |
| v_input_13 | true | original coloring |
| v_input_14_close | 0 | source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_15 | 5 | sma1length |
| v_input_16 | 35 | sma2length |
| v_input_17 | true | Show Dif as percent of current Candle |
| v_input_18 | 0.15 | tp |
| v_input_19 | 0.005 | sl |
Source Pine Script
/*backtest
start: 2023-12-21 00:00:00
end: 2023-12-28 00:00:00
period: 45m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © SoftKill21

//@version=4
strategy("Crypto strategy high/low", overlay=true)
fast_length = input(title="Fast Length", type=input.integer, defval=12)
slow_length = input(title="Slow Length", type=input.integer, defval=26)
src = input(title="Source", type=input.source, defval=close)
signal_length = input(title="Signal Smoothing", type=input.integer, minval = 1, maxval = 50, defval = 9)
sma_source = input(title="Simple MA(Oscillator)", type=input.bool, defval=true)
sma_signal = input(title="Simple MA(Signal Line)", type=input.bool, defval=false)
//sar
start = input(0.02)
increment = input(0.02)
maximum = input(0.2)
var bool uptrend = na
var float EP = na
var float SAR = na
var float AF = start
var float nextBarSAR = na
if bar_index > 0
	firstTrendBar = false
	SAR := nextBarSAR
	if bar_index == 1
		float prevSAR = na
		float prevEP = na
		lowPrev = low[1]
		highPrev = high[1]
		closeCur = close
		closePrev = close[1]
		if closeCur > closePrev
			uptrend := true
			EP := high
			prevSAR := lowPrev
			prevEP := high
		else
			uptrend := false
			EP := low
			prevSAR := highPrev
			prevEP := low
		firstTrendBar := true
		SAR := prevSAR + start * (prevEP - prevSAR)
	if uptrend
		if SAR > low
			firstTrendBar := true
			uptrend := false
			SAR := max(EP, high)
			EP := low
			AF := start
	else
		if SAR < high
			firstTrendBar := true
			uptrend := true
			SAR := min(EP, low)
			EP := high
			AF := start
	if not firstTrendBar
		if uptrend
			if high > EP
				EP := high
				AF := min(AF + increment, maximum)
		else
			if low < EP
				EP := low
				AF := min(AF + increment, maximum)
	if uptrend
		SAR := min(SAR, low[1])
		if bar_index > 1
			SAR := min(SAR, low[2])
	else
		SAR := max(SAR, high[1])
		if bar_index > 1
			SAR := max(SAR, high[2])
	nextBarSAR := SAR + AF * (EP - SAR)


// Calculating
fast_ma = sma_source ? sma(src, fast_length) : ema(src, fast_length)
slow_ma = sma_source ? sma(src, slow_length) : ema(src, slow_length)
macd = fast_ma - slow_ma
signal = sma_signal ? sma(macd, signal_length) : ema(macd, signal_length)
hist = macd - signal

CCI = input(20)
ATR = input(5)
Multiplier=input(1,title='ATR Multiplier')
original=input(true,title='original coloring')
thisCCI = cci(close, CCI)
lastCCI = nz(thisCCI[1])
bufferDn= high + Multiplier * sma(tr,ATR)
bufferUp= low - Multiplier * sma(tr,ATR)
if (thisCCI >= 0 and lastCCI < 0)
    bufferUp := bufferDn[1]
if (thisCCI <= 0 and lastCCI > 0)
    bufferDn := bufferUp[1]

if (thisCCI >= 0)
    if (bufferUp < bufferUp[1])
        bufferUp := bufferUp[1]
else
    if (thisCCI <= 0)
        if (bufferDn > bufferDn[1])
            bufferDn := bufferDn[1]
x=0.0
x:=thisCCI >= 0 ?bufferUp:thisCCI <= 0 ?bufferDn:x[1]
swap=0.0

swap:=x>x[1]?1:x<x[1]?-1:swap[1]

swap2=swap==1?color.lime:color.red
swap3=thisCCI >=0 ?color.lime:color.red
swap4=original?swap3:swap2

//elliot wave
srce = input(close, title="source")
sma1length = input(5)
sma2length = input(35)
UsePercent = input(title="Show Dif as percent of current Candle", type=input.bool, defval=true)
smadif=iff(UsePercent,(sma(srce, sma1length) - sma(srce, sma2length)) / srce * 100, sma(srce, sma1length) - sma(srce, sma2length))
col=smadif <= 0 ? color.red : color.green

longC = high > high[1] and high[1] > high[2] and close[2] > high[3] and hist > 0 and uptrend and smadif < 0 and swap4==color.lime
//longC = high > high[1] and high[1] > high[2] and high[2] > high[3] and high[3] > high[4] and close[4] > high[5]
shortC = low < low[1] and low[1] < low[2] and close[2] < low[3] and hist < 0 and not uptrend and  smadif > 0 and swap4==color.red
//shortC = low < low[1] and low[1] < low[2] and low[2] < low[3] and low[3] < low[4] and close[4] < low[5]

tp=input(0.15, title="tp")
sl=input(0.005, title="sl")


strategy.entry("long",1,when=longC)
strategy.entry("short",0,when=shortC)

strategy.exit("x_long", "long" ,loss = close * sl / syminfo.mintick, profit = close * tp / syminfo.mintick , alert_message = "closelong")
//strategy.entry("short",0, when= loss = close * sl / syminfo.mintick)

strategy.exit("x_short", "short" , loss = close * sl / syminfo.mintick, profit  = close * tp / syminfo.mintick,alert_message = "closeshort")
//strategy.entry("long",1, when = loss = close * sl / syminfo.mintick)

//strategy.close("long",when= hist < 0)
//strategy.close("short", when= hist > 0)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/High-Low-Cryptocurrency-Strategy-Based-on-Multiple-Indicators.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Triple Moving Average Combined with MACD Quantitative StrategyPine Script · Machine learning · 1d
- ADX EFI 50 Moving Average Channel Pullback StrategyPine Script · Machine learning · 1h
- Multi indicator Combination StrategyPine Script · Machine learning · 1d
- Multi factor Quantitative Trading Strategy 430013Pine Script · Machine learning
- Multi Indicator Dynamic Adaptive Quantitative Trading StrategyPine Script · Machine learning · 1h
- kNN based Trend Following StrategyPine Script · Machine learning · 1h