HMA Momentum Breakthrough Strategy
This strategy uses the HMA (Hull Moving Average) indicator and technical analysis of K-line to realize momentum judgment and breakthrough operations on prices. 1. HMA Indicator Principle The HMA indicator was created…
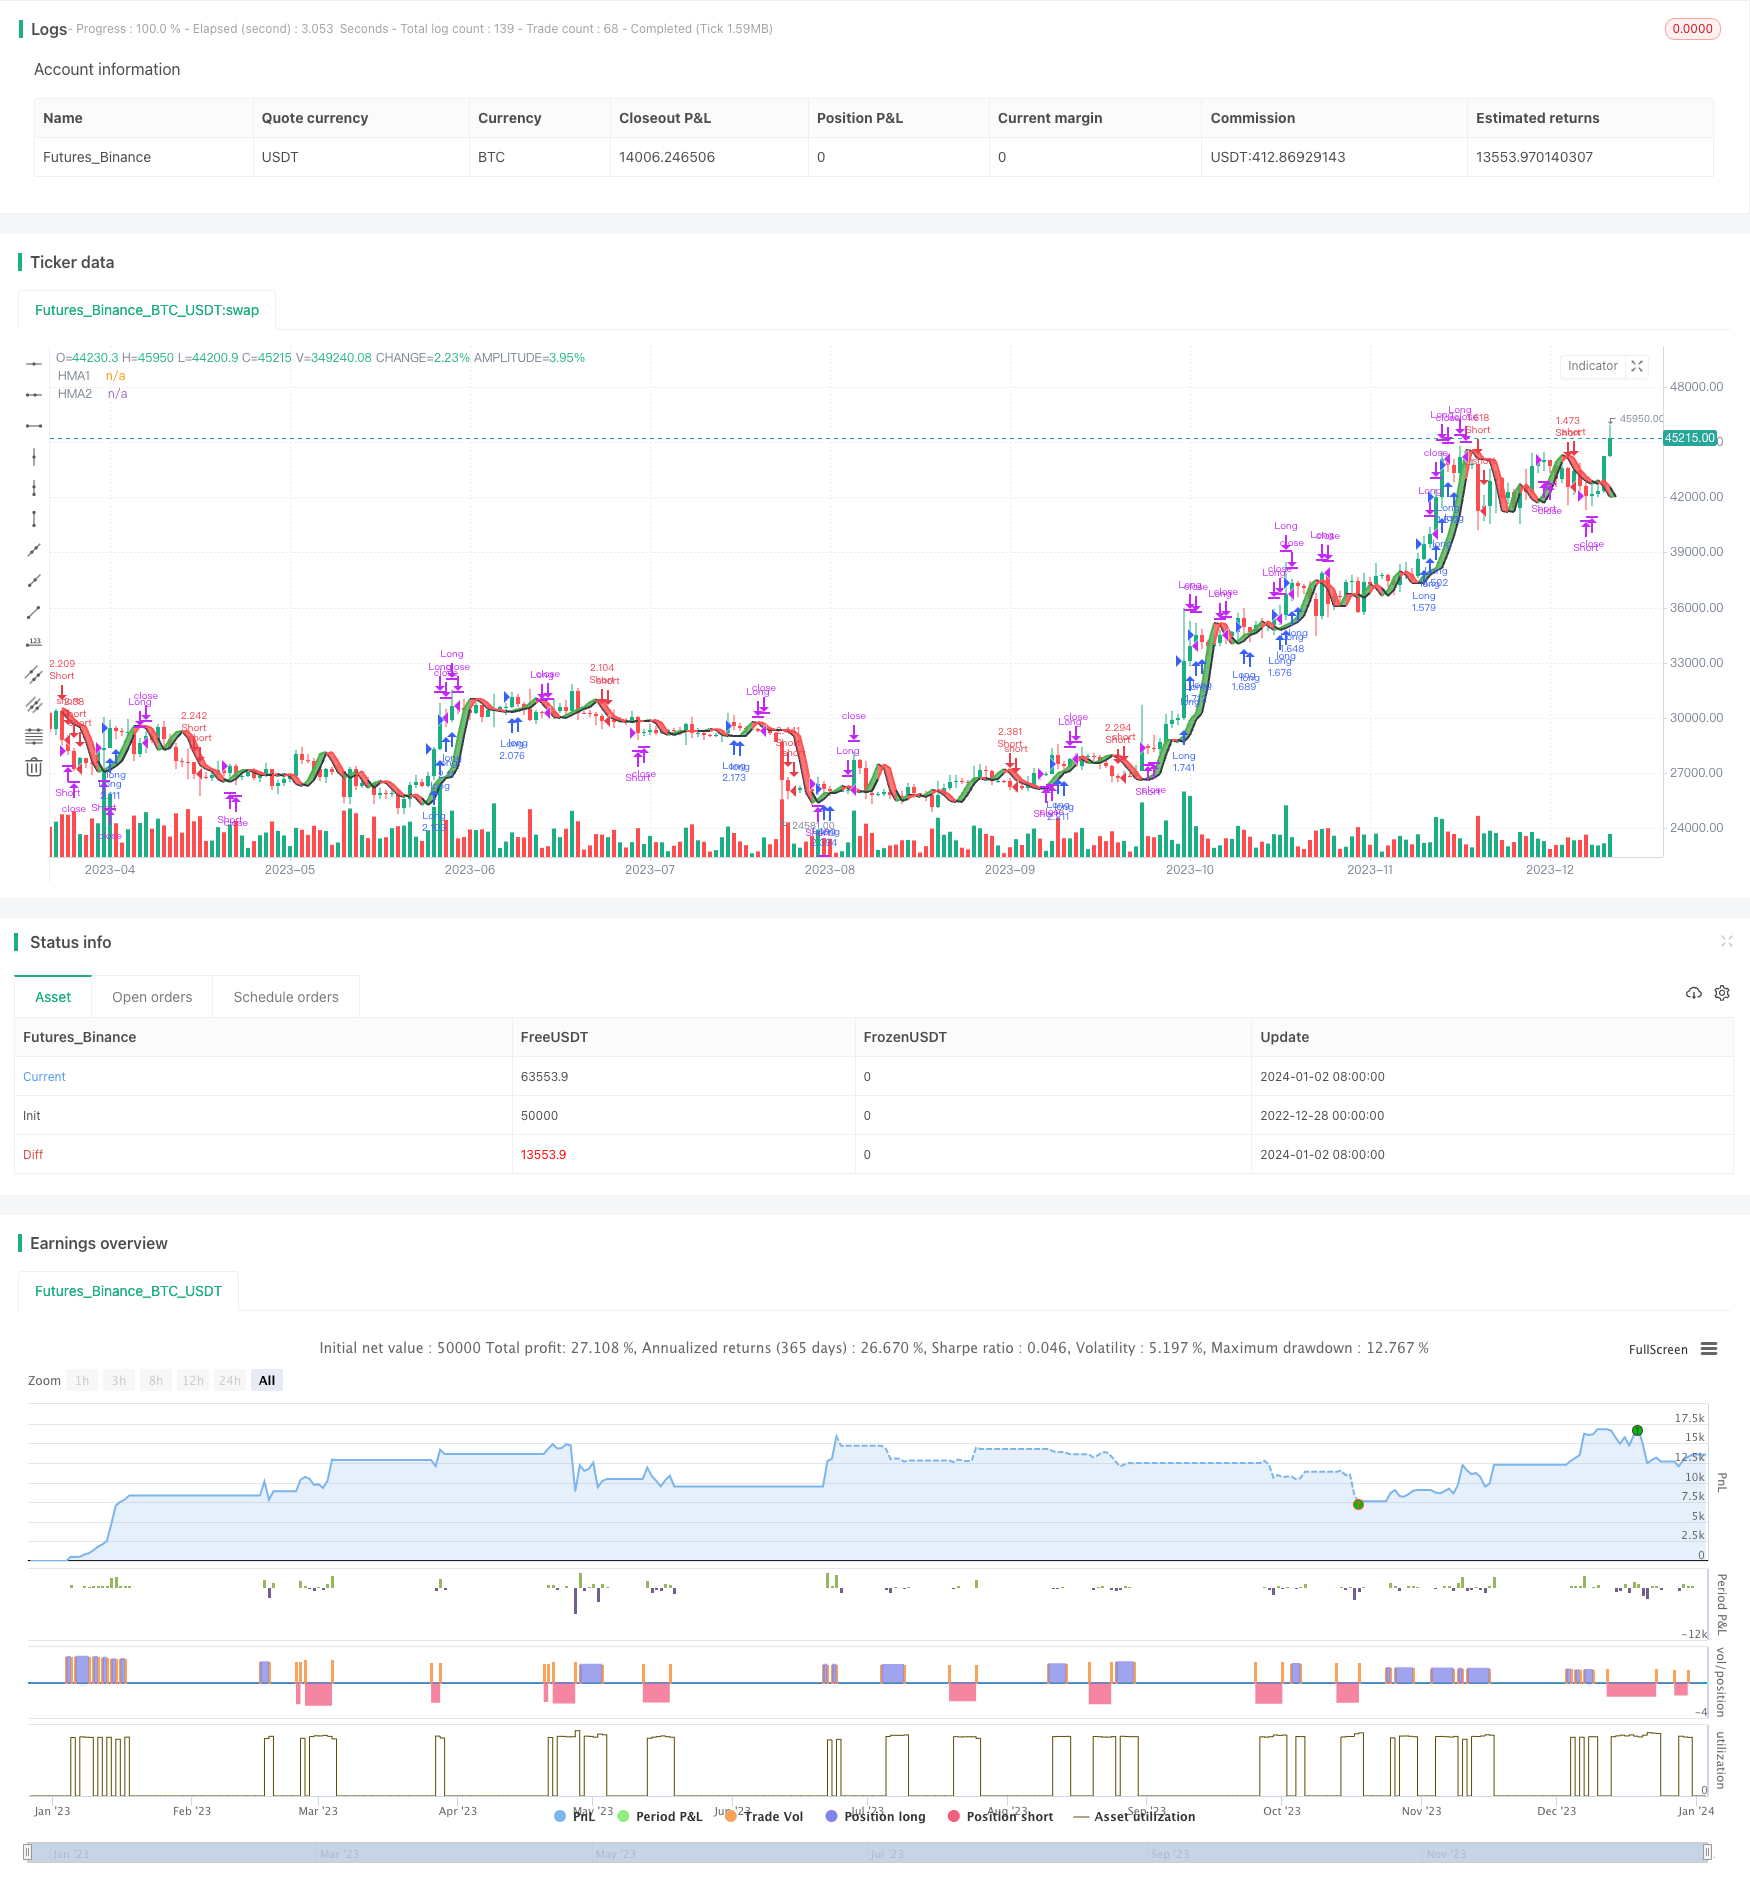
II. Strategy Overview
This strategy uses the HMA (Hull Moving Average) indicator and technical analysis of K-line to realize momentum judgment and breakthrough operations on prices.
III. Strategy Principle
- HMA Indicator Principle
The HMA indicator was created by Alan Hull in 2005 to create a moving average that is both sensitive and smooth. Its calculation method is:
(1) Calculate the Double Smoothing average DMA of half cycle
(2) Calculate the full cycle average SMA
(3) Calculate the difference DIFF between DMA and SMA
(4) Calculate the SQRT(period) cycle average line of DIFF to get HMA
- Trading Strategy
The strategy uses the upward and downward breakthroughs of the HMA indicator as signals, combined with the breakthrough of the entity part of the K-line, to generate buy and sell signals. At the same time, set stop loss and take profit principles to monitor the profit and loss situation in real time to protect profits.
IV. Advantages of Strategy
The "convergence" characteristic of the HMA indicator makes it extremely sensitive to price changes while maintaining the smoothness of the moving average to avoid false signals.
The double breakthrough mechanism improves the reliability of signals and avoids being trapped.
Dynamic stop loss and profit protection optimize risk and return.
Fully automated trading simplifies operations.
V. Risks of Strategy
In violent market fluctuations, the probability of stop loss being hit is greater.
High trading frequency increases commission costs.
Improper parameter settings can generate a lot of false signals.
Solutions
Optimize stop loss and take profit conditions and set reasonable retracements.
Adjust trading frequency to reduce commission impact.
Test and optimize HMA cycle and breakthrough conditions to determine optimal parameters.
VI. Optimization Directions of Strategy
Incorporate trend judgment indicators to avoid countertrend trading.
Increase automatic judgment of data source switching to adapt to more market environments.
Increase machine learning algorithms to achieve automatic parameter optimization.
Deploy on server to achieve 24-hour live trading verification.
VII. Summary
The HMA momentum breakout strategy utilizes the unique advantages of the Hull moving average to accurately capture market momentum. The dual breakout filtration mechanism improves signal quality, and dynamic stop profit and stop loss protect income. This strategy is easy to use, effective, and a very practical quantitative trading tool that is worth promoting.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 5 | HullMA |
| v_input_2 | -10000 | Stop Loss in $ |
| v_input_3 | 500 | Target Point in $ |
| v_input_4_ohlc4 | 0 | Price data: ohlc4 | high | low | open | hl2 | hlc3 | hlcc4 | close |
Source Pine Script
/*backtest
start: 2022-12-28 00:00:00
end: 2024-01-03 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
//SeaSide420
strategy("Hull Moving Average and Daily Candle Crossover", shorttitle="Hull&D", overlay=true, default_qty_type=strategy.percent_of_equity, max_bars_back=720, default_qty_value=100, calc_on_order_fills= true, calc_on_every_tick=true, pyramiding=0)
// settings----------------------
q=input(title="HullMA",defval=5)
SL = input(defval=-10000.00, title="Stop Loss in $", type=float, step=1)
TP = input(defval=500.00, title="Target Point in $", type=float, step=1)
price=input(ohlc4,title="Price data")
ot=1
p=price[1]
// Daily candle crossover---------
dt = 0.0010
Daily=(p-p[1])/p[1]
//--------------------------------
// Hull MA's----------------------
n2ma=2*wma(p,round(q/2))
nma=wma(p,q)
diff=n2ma-nma
sqn=round(sqrt(q))
n2ma1=2*wma(p[1],round(q/2))
nma1=wma(p[1], q)
diff1=n2ma1-nma1
sqn1=round(sqrt(q))
n1=wma(diff,sqn)
n2=wma(diff1,sqn)
//---------------------------------
// Plotting------------------------
z1e=n1>n2?green:black
z2e=n1>n2?black:red
z3e=n1>n2?green:red
n1e=plot(n1, title="HMA1", color=z1e, linewidth=2, offset=2)
n2e=plot(n2, title="HMA2", color=z2e, linewidth=2, offset=2)
fill(n1e, n2e, color=z3e, transp=80)
// Order controls-------------------
closelong = n1<n2 and n1[1]<n2[1] and n1[2]<n2[2] or strategy.openprofit<SL or strategy.openprofit>TP
if (closelong)
    strategy.close("Long")
closeshort = n1>n2 and n1[1]>n2[1] and n1[2]>n2[2] or strategy.openprofit<SL or strategy.openprofit>TP
if (closeshort)
    strategy.close("Short")
longCondition = n1>n2 and n1[1]>n2[1] and n1[2]>n2[2] and strategy.opentrades<ot and Daily>dt and close>n1
if (longCondition)
    strategy.entry("Long",strategy.long)
shortCondition = n1<n2 and n1[1]<n2[1] and n1[2]<n2[2] and strategy.opentrades<ot and Daily<dt and close<n1
if (shortCondition)
    strategy.entry("Short",strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/HMA-Momentum-Breakthrough-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- Adaptive Trading Strategy Based on ADX IndicatorPine Script · Breakout · 1d
- Average Line Breakthrough StrategyPine Script · Breakout · 1d
- BB Breakout StrategyPine Script · Breakout · 1d