Hull Suite Strategy
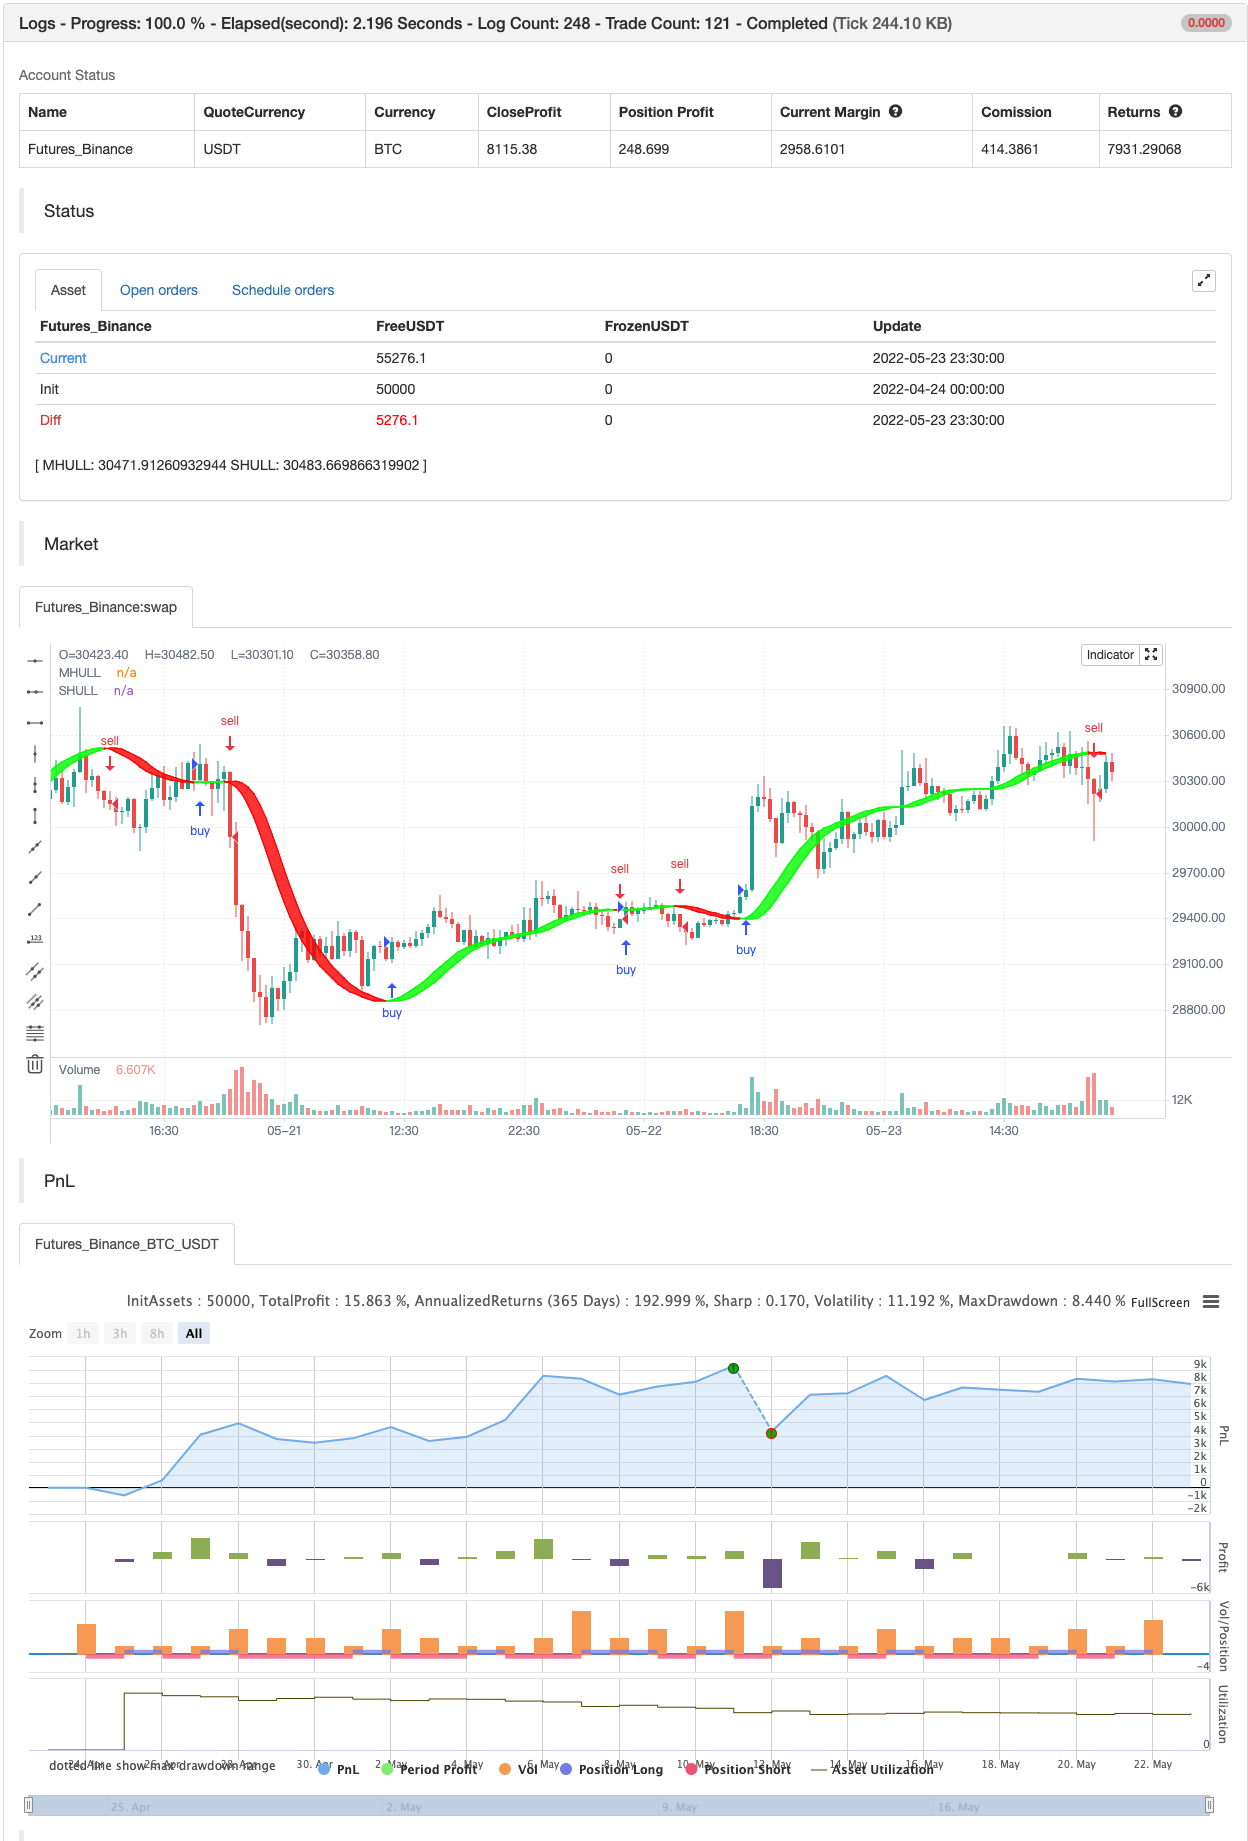
Converted the hull suite into a strategy script for easy backtesting and added ability to specify a time periods to backtest over. backtest
Converted the hull suite into a strategy script for easy backtesting and added ability to specify a time periods to backtest over.
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0 | Strategy Direction: long | short | all |
| v_input_2 | 2016 | Backtest Start Year |
| v_input_3 | true | Backtest Start Month |
| v_input_4 | true | Backtest Start Day |
| v_input_5 | 2030 | Backtest Stop Year |
| v_input_6 | 12 | Backtest Stop Month |
| v_input_7 | 30 | Backtest Stop Day |
| v_input_8_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_9 | 0 | Hull Variation: Hma | Thma | Ehma |
| v_input_10 | 55 | Length(180-200 for floating S/R , 55 for swing entry) |
| v_input_11 | true | Color Hull according to trend? |
| v_input_12 | false | Color candles based on Hull's Trend? |
| v_input_13 | true | Show as a Band? |
| v_input_14 | true | Line Thickness |
| v_input_15 | 40 | Band Transparency |
Source Pine Script
/*backtest
start: 2022-04-24 00:00:00
end: 2022-05-23 23:59:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
//Basic Hull Ma Pack tinkered by InSilico
//Converted to Strategy by DashTrader
strategy("Hull Suite Strategy", overlay=true, pyramiding=1, default_qty_type= strategy.percent_of_equity, default_qty_value = 100, calc_on_order_fills=false, slippage=0,commission_type=strategy.commission.percent,commission_value=0)
strat_dir_input = input(title="Strategy Direction", defval="long", options=["long", "short", "all"])
// strat_dir_value = strat_dir_input == "long" ? strategy.direction.long : strat_dir_input == "short" ? strategy.direction.short : strategy.direction.all
// strategy.risk.allow_entry_in(strat_dir_value)
//////////////////////////////////////////////////////////////////////
// Testing Start dates
testStartYear = input(2016, "Backtest Start Year")
testStartMonth = input(1, "Backtest Start Month")
testStartDay = input(1, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)
//Stop date if you want to use a specific range of dates
testStopYear = input(2030, "Backtest Stop Year")
testStopMonth = input(12, "Backtest Stop Month")
testStopDay = input(30, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)


testPeriod() => true
// Component Code Stop
//////////////////////////////////////////////////////////////////////
//INPUT
src = input(close, title="Source")
modeSwitch = input("Hma", title="Hull Variation", options=["Hma", "Thma", "Ehma"])
length = input(55, title="Length(180-200 for floating S/R , 55 for swing entry)")
switchColor = input(true, "Color Hull according to trend?")
candleCol = input(false,title="Color candles based on Hull's Trend?")
visualSwitch  = input(true, title="Show as a Band?")
thicknesSwitch = input(1, title="Line Thickness")
transpSwitch = input(40, title="Band Transparency",step=5)

//FUNCTIONS
//HMA
HMA(_src, _length) =>  wma(2 * wma(_src, _length / 2) - wma(_src, _length), round(sqrt(_length)))
//EHMA
EHMA(_src, _length) =>  ema(2 * ema(_src, _length / 2) - ema(_src, _length), round(sqrt(_length)))
//THMA
THMA(_src, _length) =>  wma(wma(_src,_length / 3) * 3 - wma(_src, _length / 2) - wma(_src, _length), _length)

//SWITCH
Mode(modeSwitch, src, len) =>
      modeSwitch == "Hma"  ? HMA(src, len) :
      modeSwitch == "Ehma" ? EHMA(src, len) :
      modeSwitch == "Thma" ? THMA(src, len/2) : na

//OUT
HULL = Mode(modeSwitch, src, length)
MHULL = HULL[0]
SHULL = HULL[2]

//COLOR
hullColor = switchColor ? (HULL > HULL[2] ? #00ff00 : #ff0000) : #ff9800

//PLOT
///< Frame
Fi1 = plot(MHULL, title="MHULL", color=hullColor, linewidth=thicknesSwitch, transp=50)
Fi2 = plot(visualSwitch ? SHULL : na, title="SHULL", color=hullColor, linewidth=thicknesSwitch, transp=50)
///< Ending Filler
fill(Fi1, Fi2, title="Band Filler", color=hullColor, transp=transpSwitch)
///BARCOLOR
barcolor(color = candleCol ? (switchColor ? hullColor : na) : na)


if HULL[0] > HULL[2] and testPeriod()
    strategy.entry("buy", strategy.long)
if HULL[0] < HULL[2] and testPeriod()
strategy.entry("sell", strategy.short)Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Hull-Suite-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.