Hybrid Trading Strategy Based on Volatility Breakout and Multiple Technical Indicators
This strategy is a hybrid trading system based on multiple technical indicators, combining Volume Weighted Average Price (VWAP), Time Weighted Average Price (TWAP), volatility breakout, and pattern recognition…
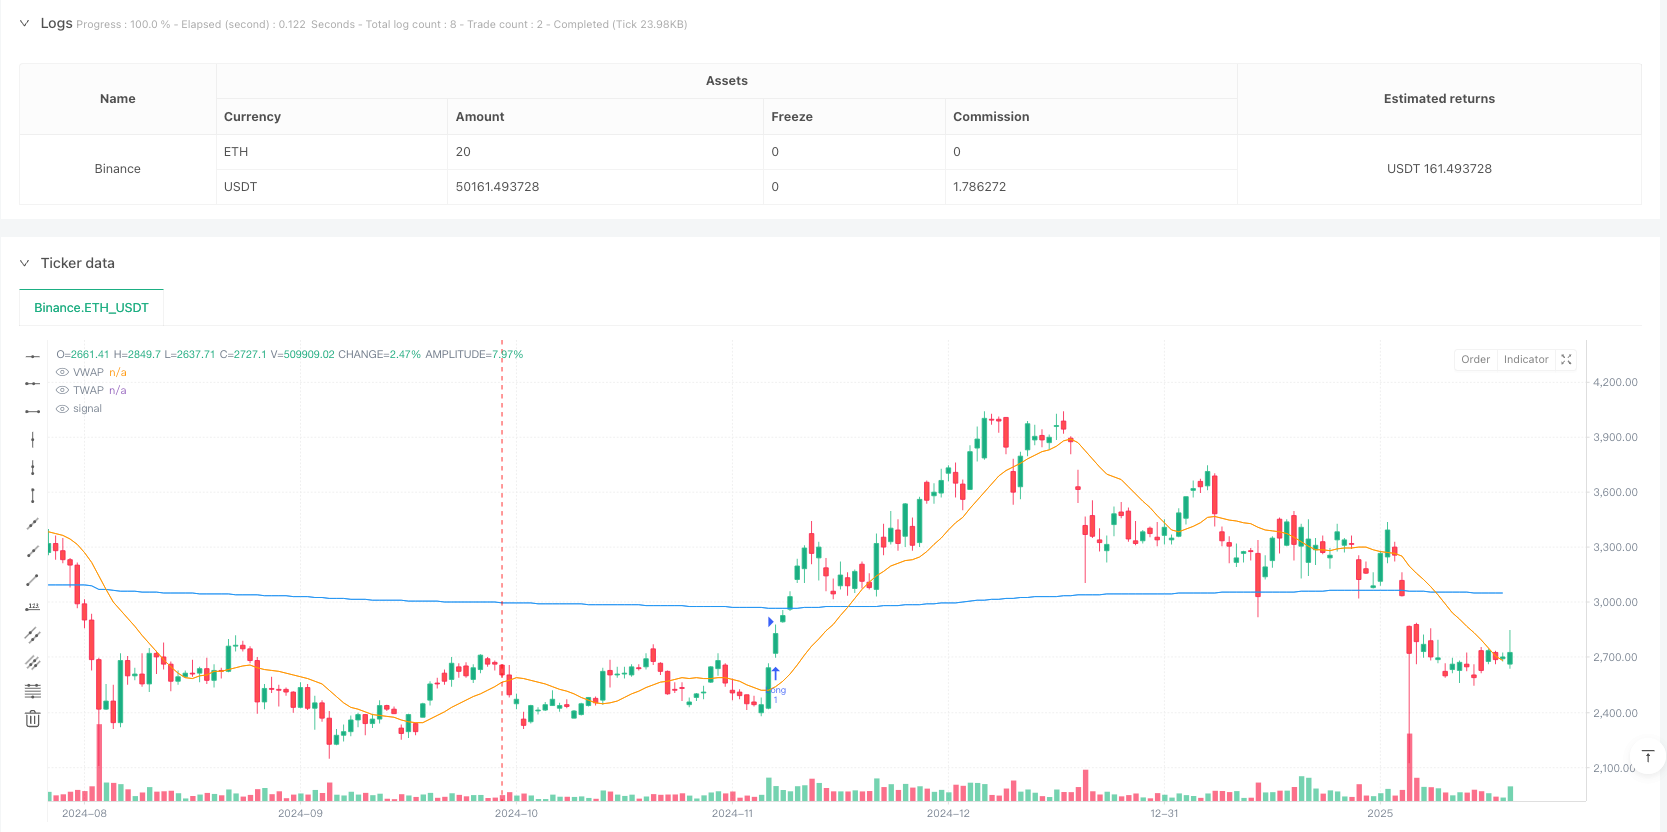
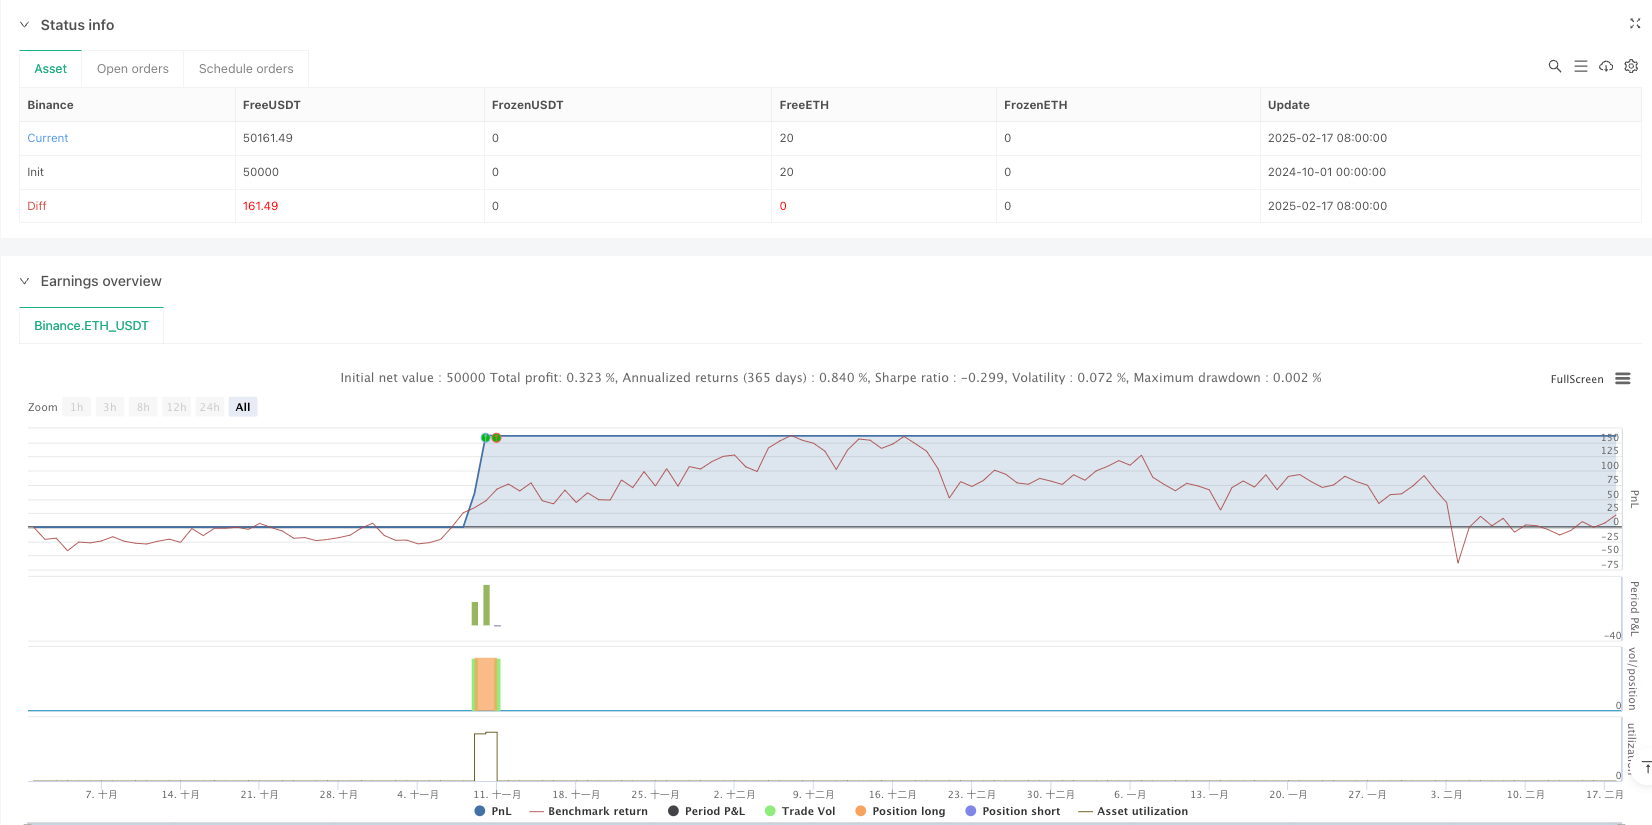
Overview
This strategy is a hybrid trading system based on multiple technical indicators, combining Volume Weighted Average Price (VWAP), Time Weighted Average Price (TWAP), volatility breakout, and pattern recognition analysis methods. The strategy determines market entry and exit timing by integrating signals from multiple technical indicators while incorporating volume confirmation to enhance trading reliability.
Strategy Principles
The core logic of the strategy is based on the following key components:
- Using VWAP and TWAP dual moving average system as price trend reference
- Volatility breakout judgment through Bollinger Bands combined with ATR indicator
- Simple head and shoulders and triangle pattern recognition
- Using volume as a necessary condition for trade confirmation
- Setting dynamic take-profit and stop-loss levels based on ATR
The system generates long signals when price breaks above the Bollinger Band upper band, technical patterns appear, and high volume is present. When price loses breakthrough momentum and technical patterns appear, the system closes existing positions. The take-profit is set at entry price plus 2 times ATR, and stop-loss is set at entry price minus 1.5 times ATR.
Strategy Advantages
- Multi-dimensional signal confirmation mechanism significantly improves trading reliability
- Dynamic take-profit and stop-loss settings adapt to market volatility
- Volume confirmation effectively filters false breakouts
- VWAP and TWAP dual moving averages provide more stable price reference
- Clear strategy logic facilitates subsequent optimization and adjustment
Strategy Risks
- Multiple condition confirmation may lead to missed trading opportunities
- May generate frequent false breakout signals in ranging markets
- Simplified pattern recognition processing may lead to misjudgments
- High volume confirmation conditions may not be suitable for low liquidity markets
- Fixed multiple ATR take-profit and stop-loss settings may not suit all market environments
Strategy Optimization Directions
- Introduce market environment recognition mechanism to dynamically adjust strategy parameters under different market conditions
- Improve pattern recognition algorithm to support more technical patterns
- Optimize volume confirmation thresholds to adapt to different market liquidity characteristics
- Add trend strength filter to improve trading signal quality
- Develop smarter take-profit and stop-loss mechanisms that can dynamically adjust based on market characteristics
Summary
This is a comprehensive trading strategy that integrates multiple technical analysis dimensions, using multiple signal confirmations to improve trading reliability. The core advantage of the strategy lies in its multi-dimensional analysis method and strict trading conditions, which help reduce the risk of false signals. Although there are aspects that need optimization, the overall framework has good scalability and adaptability. Through continuous optimization and adjustment, this strategy has the potential to maintain stable performance in different market environments.
Source Pine Script
/*backtest
start: 2024-10-01 00:00:00
end: 2025-02-18 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Binance","currency":"ETH_USDT"}]
*/

//@version=6
strategy("Hybrid Money Making Trading Strategy", overlay=true)

// VWAP Calculation
cumulative_vp = ta.cum(volume * close)
cumulative_vol = ta.cum(volume)
vwap = cumulative_vp / cumulative_vol
plot(vwap, title="VWAP", color=color.blue)

// TWAP Calculation
twap = ta.sma((high + low + close) / 3, 14)
plot(twap, title="TWAP", color=color.orange)

// Volatility Breakout
atr = ta.atr(14)
bb_upper = ta.sma(close, 20) + 2 * ta.stdev(close, 20)
bb_lower = ta.sma(close, 20) - 2 * ta.stdev(close, 20)
volatility_breakout = close > bb_upper

// Pattern Recognition (Basic Example)
head_shoulders = ta.crossover(close, ta.sma(close, 50))
triangle_pattern = ta.crossover(ta.sma(close, 10), ta.sma(close, 50))
pattern_signal = head_shoulders or triangle_pattern

// Volume Confirmation (Require high volume for entry)
vol_avg = ta.sma(volume, 20)
high_volume = volume > 1.5 * vol_avg

// Buy/Sell Signal Conditions
buy_signal = volatility_breakout and pattern_signal and high_volume
sell_signal = not volatility_breakout and pattern_signal

// Track Latest Signal
var float last_signal_price = na
var string last_signal_type = ""
if buy_signal
    last_signal_price := close
    last_signal_type := "BUY"
if sell_signal
    last_signal_price := close
    last_signal_type := "SELL"

// Strategy Entry & Exit
if buy_signal
    strategy.entry("Long", strategy.long)
    strategy.exit("TakeProfit", from_entry="Long", stop=close - 1.5 * atr, limit=close + 2 * atr)
if sell_signal
    strategy.close("Long")
Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Hybrid-Trading-Strategy-Based-on-Volatility-Breakout-and-Multiple-Technical-Indicators.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h
- Multi factor Intelligent Trading StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trading StrategyPine Script · Breakout · 2h
- Dynamic Buying Selling Volume Breakout StrategyPine Script · Breakout · 1d
- Enhanced Bollinger Breakout Quantitative Strategy with Momentum Filter Integration SystemPine Script · Breakout · 2d
- High Precision RSI and Bollinger Bands Breakout Strategy with Optimized Risk Reward RatioPine Script · Breakout · 1h