Ichimoku Balance Line Strategy
The Ichimoku Balance Line strategy is a trend following strategy that determines trend direction by calculating moving averages combined with the Ichimoku Kinko Hyo indicator for low-risk trend trading.
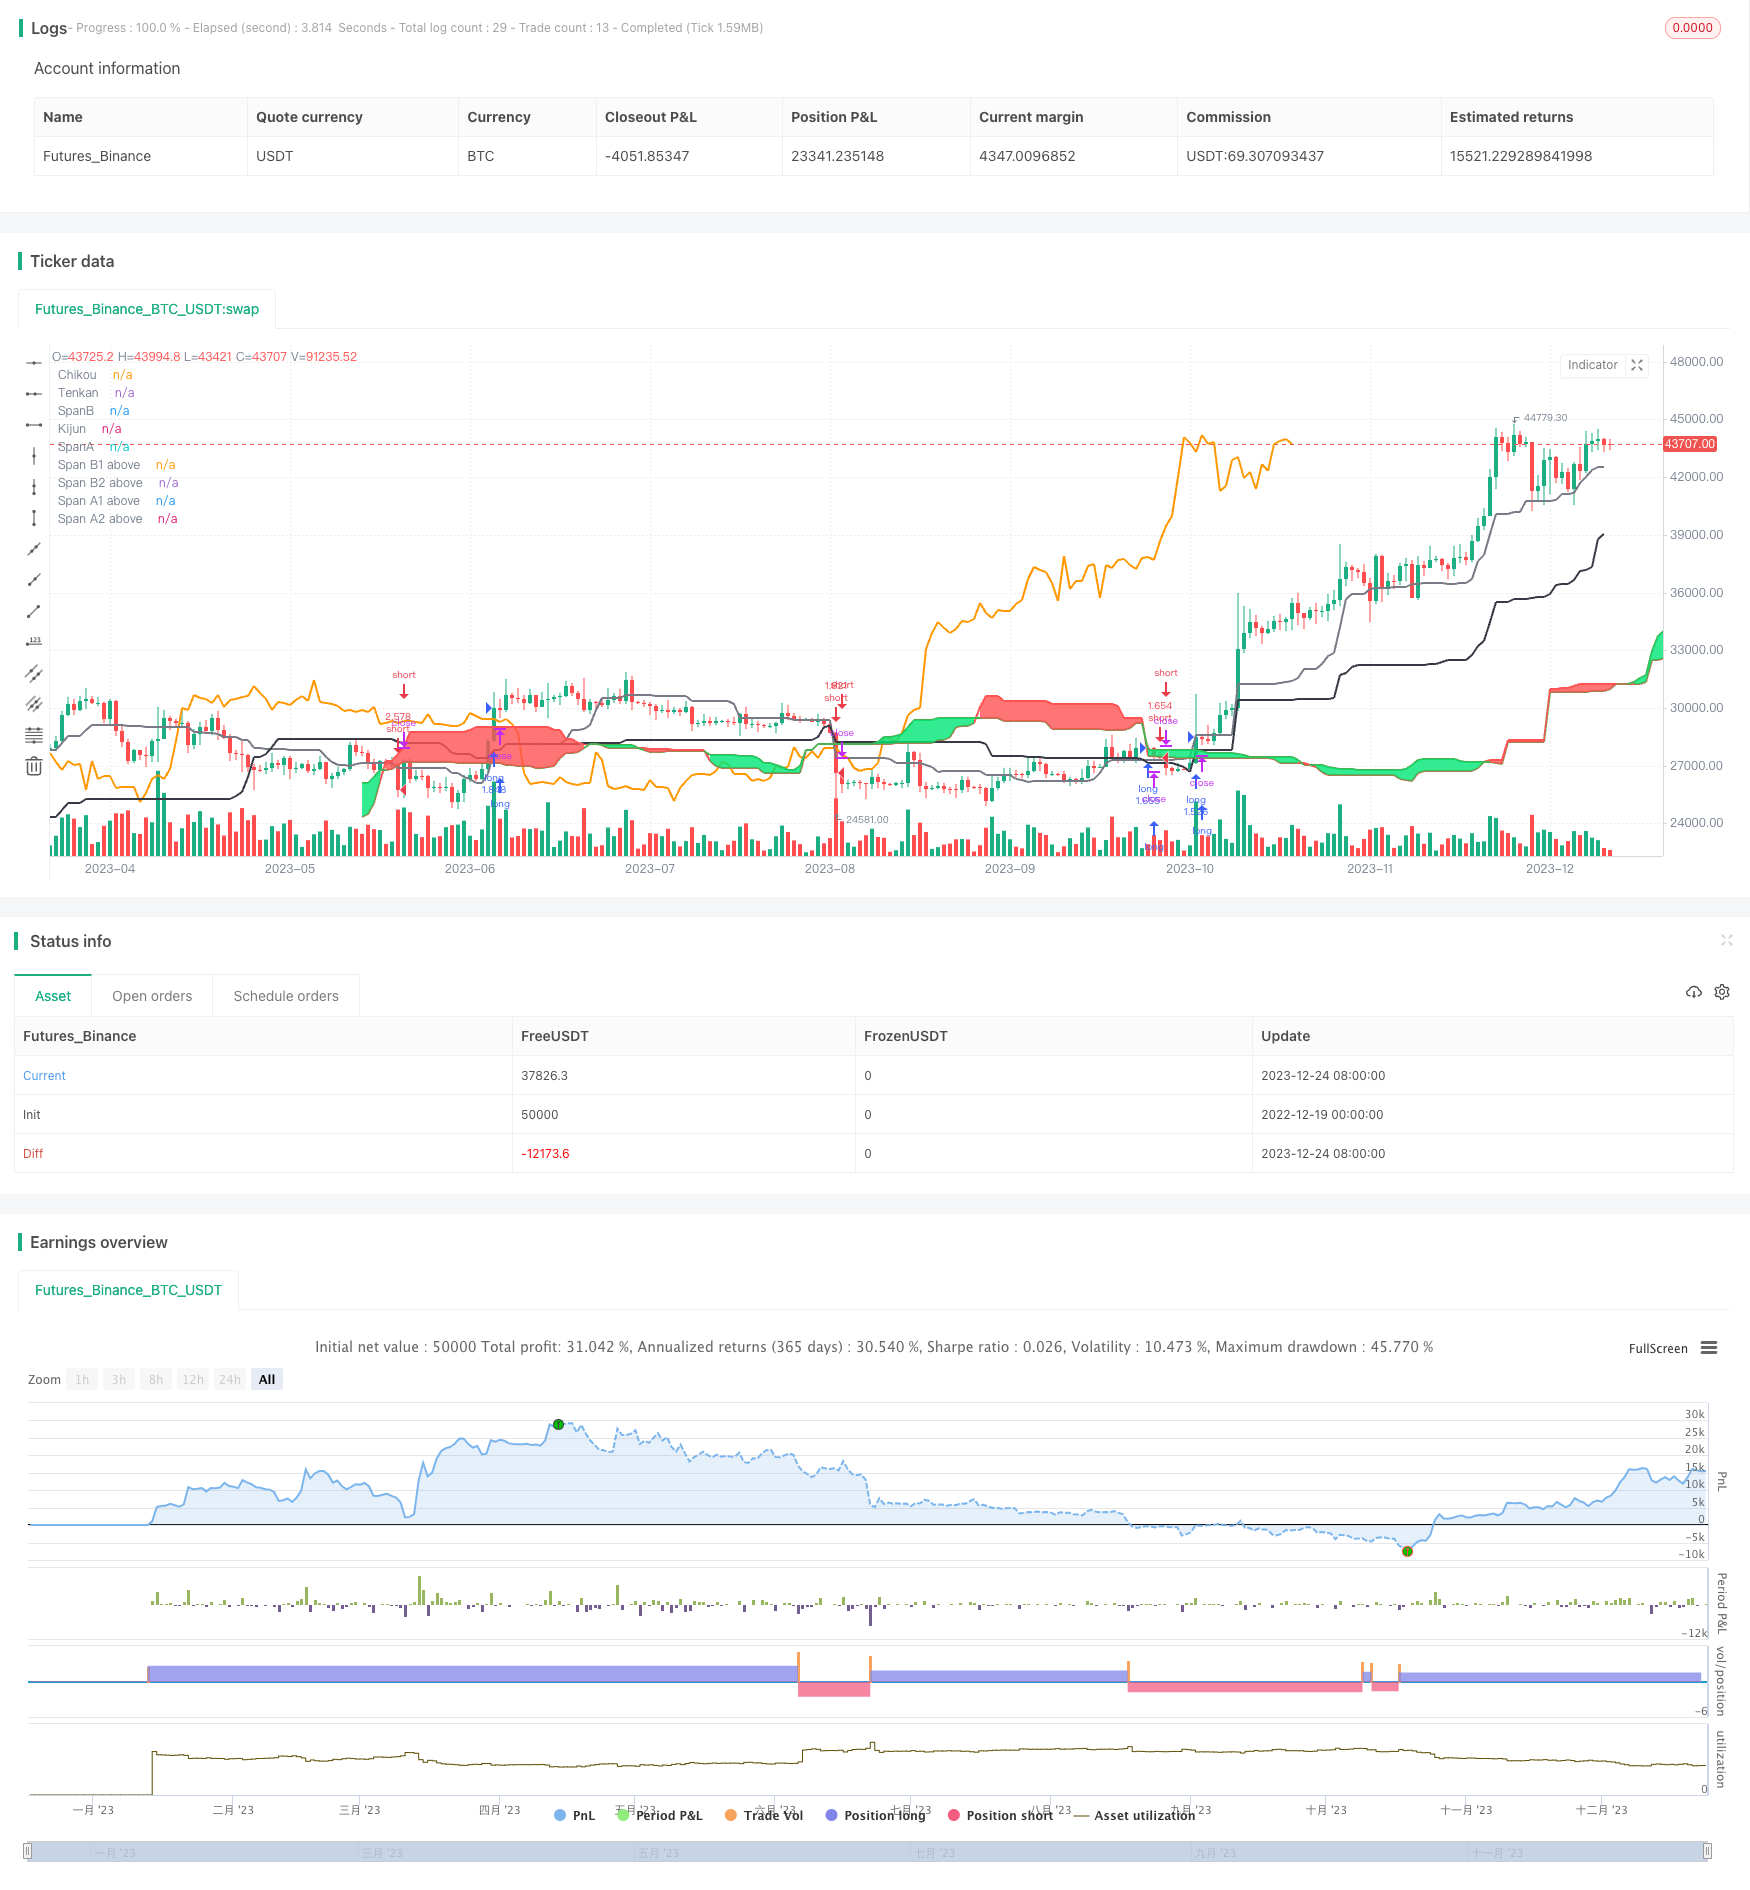
Overview
The Ichimoku Balance Line strategy is a trend following strategy that determines trend direction by calculating moving averages combined with the Ichimoku Kinko Hyo indicator for low-risk trend trading.
Strategy Principle
The strategy mainly uses the Ichimoku Kinko Hyo indicator to determine the trend direction. Ichimoku Kinko Hyo, also known as "Ichimoku Cloud", consists of the Tenkan-sen (Conversion Line), Kijun-sen (Base Line), Senkou Span A (Leading Span A), and Senkou Span B (Leading Span B). It forms an equilibrium zone between the front and back called the "Kumo Cloud". When price is above the cloud, it signals an upward trend. A breach below the cloud signals a downward trend.
The strategy combines the price relationship with moving averages to determine the trend direction. It generates a buy signal when the price crosses above the Base Line and Conversion Line. A sell signal is generated when the price breaks below the cloud. This combination helps to filter false breakouts and lock in the trend direction.
Advantage Analysis
- Uses Ichimoku Kinko Hyo to determine the trend and avoid false breakouts in ranging markets
- Customizable moving average parameters for optimization across periods
- Combination with moving averages helps to effectively lock in trend direction
- Cloud bands allow low-risk trend trading
Risk Analysis
- Prone to generating false signals in choppy market conditions
- Improper parameter settings may lead to overly frequent or delayed trade signals
- Manual judgement of trend direction and parameter adjustment required
Optimization Directions
The strategy can be optimized in several ways:
- Optimize Ichimoku parameters to suit more timeframes
- Incorporate stop loss to limit losses per trade
- Add indicators to gauge strong and weak trends to avoid whipsaws
- Add more entry conditions to avoid opening positions in extreme market conditions
Conclusion
In conclusion, the Ichimoku Balance Line Strategy uses the Ichimoku Cloud to determine trend direction, locks in trends effectively, and generates trade signals by combining price relationship with moving averages, allowing low-risk trend trading. The strategy can be adapted to different market environments through parameter tuning and optimizations, making it worthwhile for investors to research and utilize.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2016 | Backtest Start Year |
| v_input_2 | true | Backtest Start Month |
| v_input_3 | true | Backtest Start Day |
| v_input_4 | 2019 | Backtest Stop Year |
| v_input_5 | 12 | Backtest Stop Month |
| v_input_6 | 31 | Backtest Stop Day |
| v_input_7 | 18 | Tenkan |
| v_input_8 | 60 | Kijun |
| v_input_9 | 30 | Senkou B |
| v_input_10 | 52 | Senkou A |
| v_input_11 | 52 | Span Offset |
| v_input_12 | true | Show Tenkan |
| v_input_13 | true | Show Kijun |
| v_input_14 | true | Show Span A |
| v_input_15 | true | Show Span B |
| v_input_16 | true | Show Chikou |
Source Pine Script
/*backtest
start: 2022-12-19 00:00:00
end: 2023-12-25 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
// Credit for the initial code to nathanhoffer - I simply added the ability to select a time period
//
strategy("Cloud Breakout", overlay=true, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=100, commission_type=strategy.commission.percent, commission_value=0.0)

/////////////// Component Code Start ///////////////
testStartYear = input(2016, "Backtest Start Year")
testStartMonth = input(1, "Backtest Start Month")
testStartDay = input(1, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay, 0, 0)

testStopYear = input(2019, "Backtest Stop Year")
testStopMonth = input(12, "Backtest Stop Month")
testStopDay = input(31, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay, 0, 0)

testPeriod() => true

Ten = input(18, minval=1, title="Tenkan")
Kij = input(60, minval=1, title="Kijun")
LeadSpan = input(30, minval=1, title="Senkou B")
Displace = input(52, minval=1, title="Senkou A")
SpanOffset = input(52, minval=1, title="Span Offset")

sts = input(true, title="Show Tenkan")
sks = input(true, title="Show Kijun")
ssa = input(true, title="Show Span A")
ssb = input(true, title="Show Span B")
sc = input(true, title="Show Chikou")

source = close

//Script for Ichimoku Indicator
donchian(len) => avg(lowest(len), highest(len))
TS = donchian(Ten)
KS = donchian(Kij)
SpanA = avg(TS, KS)
SpanB = donchian(LeadSpan)

CloudTop = max(TS, KS)

Chikou = source[Displace]
SpanAA = avg(TS, KS)[SpanOffset]
SpanBB = donchian(LeadSpan)[SpanOffset]

//Kumo Breakout (Long)
SpanA_Top = SpanAA >= SpanBB ? 1 : 0
SpanB_Top = SpanBB >= SpanAA ? 1 : 0

SpanA_Top2 = SpanA >= SpanB ? 1 : 0
SpanB_Top2 = SpanB >= SpanA ? 1 : 0

SpanA1 = SpanA_Top2 ? SpanA : na
SpanA2 = SpanA_Top2 ? SpanB : na

SpanB1 = SpanB_Top2 ? SpanA : na
SpanB2 = SpanB_Top2 ? SpanB : na

//plot for Tenkan and Kijun (Current Timeframe)
p1= plot(sts and TS ? TS : na, title="Tenkan", linewidth = 2, color = gray)
p2 = plot(sks and KS ? KS : na, title="Kijun", linewidth = 2, color = black)
//p5 = plot(sc and KS ? KS : na, title="Chikou", linewidth = 2, color = orange)
p5 = plot(sc and Displace ? close: na, title="Chikou", linewidth = 2, offset=-Displace, color = orange)

//Plot for Kumo Cloud (Dynamic Color)
p3 = plot(ssa and SpanA ? SpanA : na, title="SpanA", linewidth=2, offset=Displace, color=green)
p4 = plot(ssb and SpanB ? SpanB : na, title="SpanB", linewidth=2, offset=Displace, color=red)

p8 = plot(ssa and SpanA1 ? SpanA1 : na, title="Span A1 above", style=linebr, linewidth=1, offset=Displace, color=green)
p9 = plot(ssa and SpanA2 ? SpanA2 : na, title="Span A2 above", style=linebr, linewidth=1, offset=Displace, color=green)
p10 = plot(ssb and SpanB1 ? SpanB1 : na, title="Span B1 above", style=linebr, linewidth=1, offset=Displace, color=red)
p11 = plot(ssb and SpanB2 ? SpanB2 : na, title="Span B2 above", style=linebr, linewidth=1, offset=Displace, color=red)

fill(p8, p9, color = lime, transp=70, title="Kumo Cloud Up")
fill (p10, p11, color=red, transp=70, title="Kumo Cloud Down")

LongSpan = (SpanA_Top and source[1] < SpanAA[1] and source > SpanAA) or (SpanB_Top and source[1] < SpanBB[1] and source > SpanBB) ? 1 : 0
cupSpan = LongSpan  == 1 ? LongSpan : 0

Long_Breakout = (SpanA_Top ==1 and crossover(source, SpanAA)) or (SpanB_Top ==1 and crossover(source, SpanBB))

ShortSpan = (SpanB_Top and source[1] > SpanAA[1] and source < SpanAA) or (SpanA_Top and source[1] > SpanBB[1] and source < SpanBB) ? 1 : 0
cdnSpan = ShortSpan == 1 ? ShortSpan : 0

Short_Breakout = (SpanA_Top ==1 and crossunder(source, SpanBB)) or (SpanB_Top ==1 and crossunder(source, SpanAA))

//Kumo Twist
Kumo_Twist_Long = SpanA[1] < SpanB[1] and SpanA > SpanB ? 1 : 0
Kumo_Twist_Short = SpanA[1] > SpanB[1] and SpanA < SpanB ? 1 : 0

cupD = Kumo_Twist_Long == 1 ? Kumo_Twist_Long : 0
cdnD = Kumo_Twist_Short == 1 ? Kumo_Twist_Short : 0

Chikou_Above = close > Chikou
Chikou_Below = close < Chikou

long = (cross(TS, SpanA) or cross(TS, SpanB)) and TS>SpanA and TS>SpanB and TS>=KS
short = cross(TS, KS) and KS >= TS

if testPeriod()
    strategy.entry("long", strategy.long, when=Long_Breakout)
strategy.entry("short", strategy.short, when=Short_Breakout)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Ichimoku-Balance-Line-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Ichimoku Stop Loss StrategyPine Script · Breakout · 1d
- Multi Indicator Short Term Algorithmic Trading StrategyPine Script · Breakout · 4h
- The Octagon Cloud Tracing StrategyPine Script · Breakout · 1d
- Ichimoku Breakout StrategyPine Script · Breakout · 1d
- Integrated Ichimoku Keltner Trading System Based on Moving Average StrategyPine Script · Breakout · 1h
- Ichimoku Cloud Market Analysis StrategyPine Script · Breakout · 5m