Ichimoku Cloud and MACD Momentum RidingIchimoku Cloud and MACD Momentum Riding Strategy
The Ichimoku Cloud and MACD Momentum Riding is a trend following strategy combining the Ichimoku Cloud indicator and the MACD momentum indicator. The strategy utilizes the Ichimoku Cloud to determine trend direction…
Overview
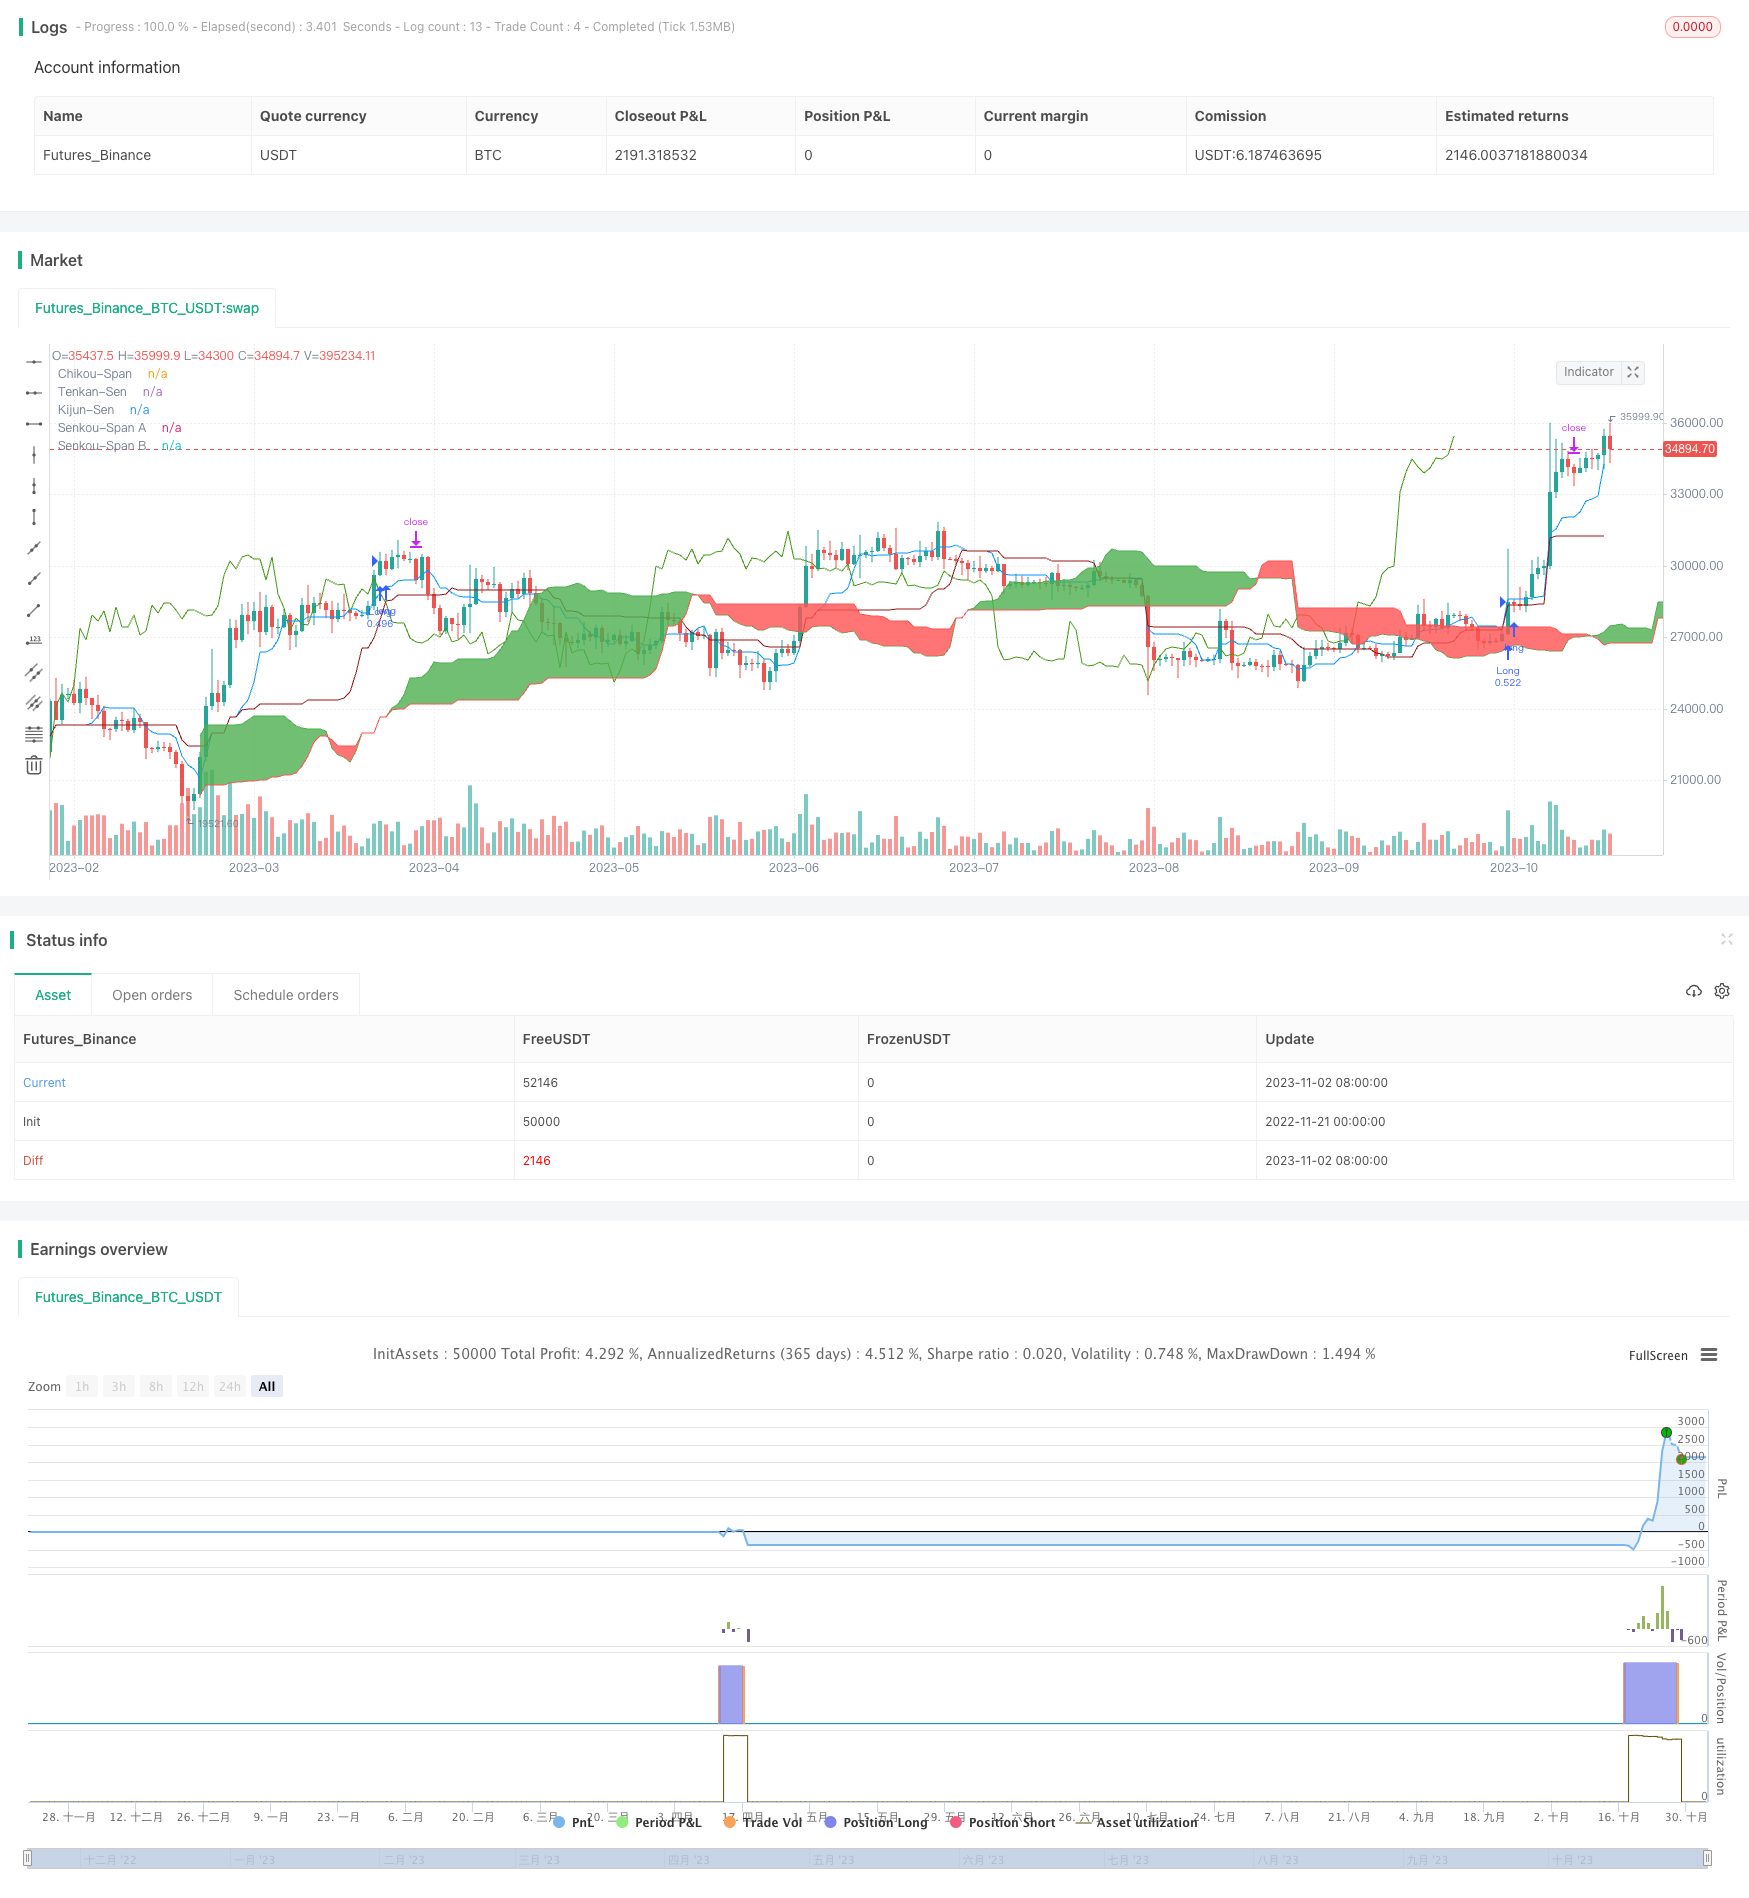
The Ichimoku Cloud and MACD Momentum Riding is a trend following strategy combining the Ichimoku Cloud indicator and the MACD momentum indicator. The strategy utilizes the Ichimoku Cloud to determine trend direction and support/resistance levels, as well as the MACD indicator to detect momentum reversal, and enters the market timed during a trend. Meanwhile, the strategy adopts a trailing stop loss to lock in profits and reduce drawdowns.
Strategy Logic
Ichimoku Cloud
The Ichimoku Cloud consists of the Turning Line (Tenkan-Sen), Base Line (Kijun-Sen), Leading Span A (Senkou-Span A), Leading Span B (Senkou-Span B) and Confirmation Line (Chikou-Span). The strategy uses the following signals to determine trend direction and support/resistance:
- Price above Cloud - Uptrend
- Price below Cloud - Downtrend
- Turning Line crosses above Base Line - Bullish signal
- Turning Line crosses below Base Line - Bearish signal
MACD Indicator
The Moving Average Convergence Divergence, or MACD, is a momentum indicator. In this strategy, when MACD's fast line crosses above slow line it's a buy signal, and when fast line crosses below slow line it's a sell signal.
Entries and Exits
When Turning Line crosses above Base Line, Confirmation Line crosses above close price of 26 bars ago, close price breaks above top band of Cloud, and MACD's fast line has bullish crossover over slow line, go long.
When price rises 3%, the strategy will move stop loss to 97% of current price to lock in profits and trail the upside move. If drawdown exceeds 3%, stop out with loss.
When Turning Line crosses below Base Line, Confirmation Line crosses below close price of 26 bars ago, close price breaks below bottom band of Cloud, and MACD's fast line has bearish crossover below slow line, go short.
When price drops 3%, the strategy will move stop loss to 103% of current price to lock in profits and trail the downside move. If rise exceeds 3%, stop out with loss.
Advantage Analysis
This strategy combines trend identification and timing of entry, which can achieve good returns during trending markets.
Ichimoku Cloud can clearly identify trend direction. The strategy only enters aligning with Cloud direction, avoiding counter-trend trades.
MACD is effective in detecting short-term momentum reversals. Combining with Cloud it improves entry accuracy.
Trailing stop loss allows the strategy to keep running during a trend. Proper position sizing ensures controlled risk per trade.
Risk Analysis
There are also certain risks with this strategy:
Cloud needs relatively long lookback periods and may give inaccurate signals in the short term.
MACD oscillates with price and can generate false signals. More filters are needed to confirm signals.
Trailing stop loss only suits trending markets. Stop loss percentage needs to be adjusted accordingly, otherwise whipsaws may stop out too frequently during ranging markets.
The strategy itself does not manage risk. User needs to implement external risk management techniques to control losses.
Optimization Directions
The Ichimoku Cloud and MACD Momentum Riding strategy can be optimized in the following ways:
Parameter tuning - Adjust Turning Line, Base Line lookback periods, optimize MACD parameters for clearer signals.
Add filtration - Use other indicators like RSI, Bollinger Bands to filter out bad signals, reducing false signals.
Dynamic stops - Base stop loss percentage on market volatility and risk preference.
Incorporate position sizing - Limit max loss per trade to control overall drawdown.
Auto selecting contracts & rebalancing - Expand adaptability to more markets.
Conclusion
The Ichimoku Cloud and MACD Momentum Riding strategy considers both trend and timing, which can achieve good return when parameters are properly tuned and risk controls are in place. It suits investors with some programming skills as a trend following strategy, and serves as a reference to quant trading beginners for learning technical indicators and strategy development.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Show Date Range |
| v_input_int_1 | 9 | Tenkan-Sen Bars |
| v_input_int_2 | 26 | Kijun-Sen Bars |
| v_input_int_3 | 52 | Senkou-Span B Bars |
| v_input_int_4 | 26 | Chikou-Span Offset |
| v_input_int_5 | 26 | Senkou-Span Offset |
| v_input_2 | true | Long Entry |
| v_input_3 | true | Short Entry |
| v_input_float_1 | 3 | Trail Long Loss (%) |
| v_input_float_2 | 3 | Trail Short Loss (%) |
Source Pine Script
/*backtest
start: 2022-11-21 00:00:00
end: 2023-11-03 05:20:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy('Ichimoku Cloud with MACD and Trailing Stop Loss',
         overlay=true,
         initial_capital=1000,
         process_orders_on_close=true,
         default_qty_type=strategy.percent_of_equity,
         default_qty_value=30,
         commission_type=strategy.commission.percent,
         commission_value=0.1)

showDate = input(defval=true, title='Show Date Range')
timePeriod = time >= timestamp(syminfo.timezone, 2022, 6, 1, 0, 0)


// Inputs
ts_bars = input.int(9, minval=1, title='Tenkan-Sen Bars')
ks_bars = input.int(26, minval=1, title='Kijun-Sen Bars')
ssb_bars = input.int(52, minval=1, title='Senkou-Span B Bars')
cs_offset = input.int(26, minval=1, title='Chikou-Span Offset')
ss_offset = input.int(26, minval=1, title='Senkou-Span Offset')
long_entry = input(true, title='Long Entry')
short_entry = input(true, title='Short Entry')

middle(len) => math.avg(ta.lowest(len), ta.highest(len))

// Ichimoku Components
tenkan = middle(ts_bars)
kijun = middle(ks_bars)
senkouA = math.avg(tenkan, kijun)
senkouB = middle(ssb_bars)

// Plot Ichimoku Kinko Hyo
plot(tenkan, color=color.new(#0496ff, 0), title='Tenkan-Sen')
plot(kijun, color=color.new(#991515, 0), title='Kijun-Sen')
plot(close, offset=-cs_offset + 1, color=color.new(#459915, 0), title='Chikou-Span')
sa = plot(senkouA, offset=ss_offset - 1, color=color.new(color.green, 0), title='Senkou-Span A')
sb = plot(senkouB, offset=ss_offset - 1, color=color.new(color.red, 0), title='Senkou-Span B')
fill(sa, sb, color=senkouA > senkouB ? color.green : color.red, title='Cloud color', transp=90)

ss_high = math.max(senkouA[ss_offset - 1], senkouB[ss_offset - 1])
ss_low = math.min(senkouA[ss_offset - 1], senkouB[ss_offset - 1])


// MACD
[macd, macd_signal, macd_histogram] = ta.macd(close, 12, 26, 9)


// Entry/Exit Signals
tk_cross_bull = tenkan > kijun
tk_cross_bear = tenkan < kijun
cs_cross_bull = ta.mom(close, cs_offset - 1) > 0
cs_cross_bear = ta.mom(close, cs_offset - 1) < 0
price_above_kumo = close > ss_high
price_below_kumo = close < ss_low

bullish = tk_cross_bull and cs_cross_bull and price_above_kumo and ta.crossover(macd, macd_signal)
bearish = tk_cross_bear and cs_cross_bear and price_below_kumo and ta.crossunder(macd, macd_signal)

// Configure trail stop level with input options
longTrailPerc = input.float(title='Trail Long Loss (%)', minval=0.0, step=0.1, defval=3) * 0.01
shortTrailPerc = input.float(title='Trail Short Loss (%)', minval=0.0, step=0.1, defval=3) * 0.01

// Determine trail stop loss prices
longStopPrice = 0.0
shortStopPrice = 0.0

longStopPrice := if strategy.position_size > 0
    stopValue = close * (1 - longTrailPerc)
    math.max(stopValue, longStopPrice[1])
else
    0

shortStopPrice := if strategy.position_size < 0
    stopValue = close * (1 + shortTrailPerc)
    math.min(stopValue, shortStopPrice[1])
else
    999999

strategy.entry('Long', strategy.long, when=bullish and long_entry and timePeriod)
strategy.exit('Exit', stop = longStopPrice, limit = shortStopPrice)
//strategy.close('Long', when=bearish and not short_entry)

//strategy.entry('Short', strategy.short, when=bearish and short_entry and timePeriod)
//strategy.close('Short', when=bullish and not long_entry)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Ichimoku-Cloud-and-MACD-Momentum-RidingIchimoku-Cloud-and-MACD-Momentum-Riding-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dynamic Trend Momentum Optimization Strategy with G Channel IndicatorPine Script · Momentum · 1h
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- Multi factor Adaptive Momentum Tracking StrategyPine Script · Momentum · 3m
- Cloud Soaring High Yield Daily Trading StrategyPine Script · Momentum · 1h
- Multi Indicator Trend Momentum Trading Strategy An Optimized Quantitative Trading System Based on Bollinger Bands Fibonacci and ATRPine Script · Momentum · 1h
- Momentum Trend Ichimoku Cloud Trading StrategyPine Script · Momentum · 1d