Ichimoku Cloud Quant Scalping Strategy
The Ichimoku Cloud Quant Scalping Strategy is a short-term quantitative strategy integrating Ichimoku Cloud and Average Directional Index (ADX). It utilizes Ichimoku Cloud to determine the trend direction and ADX to…
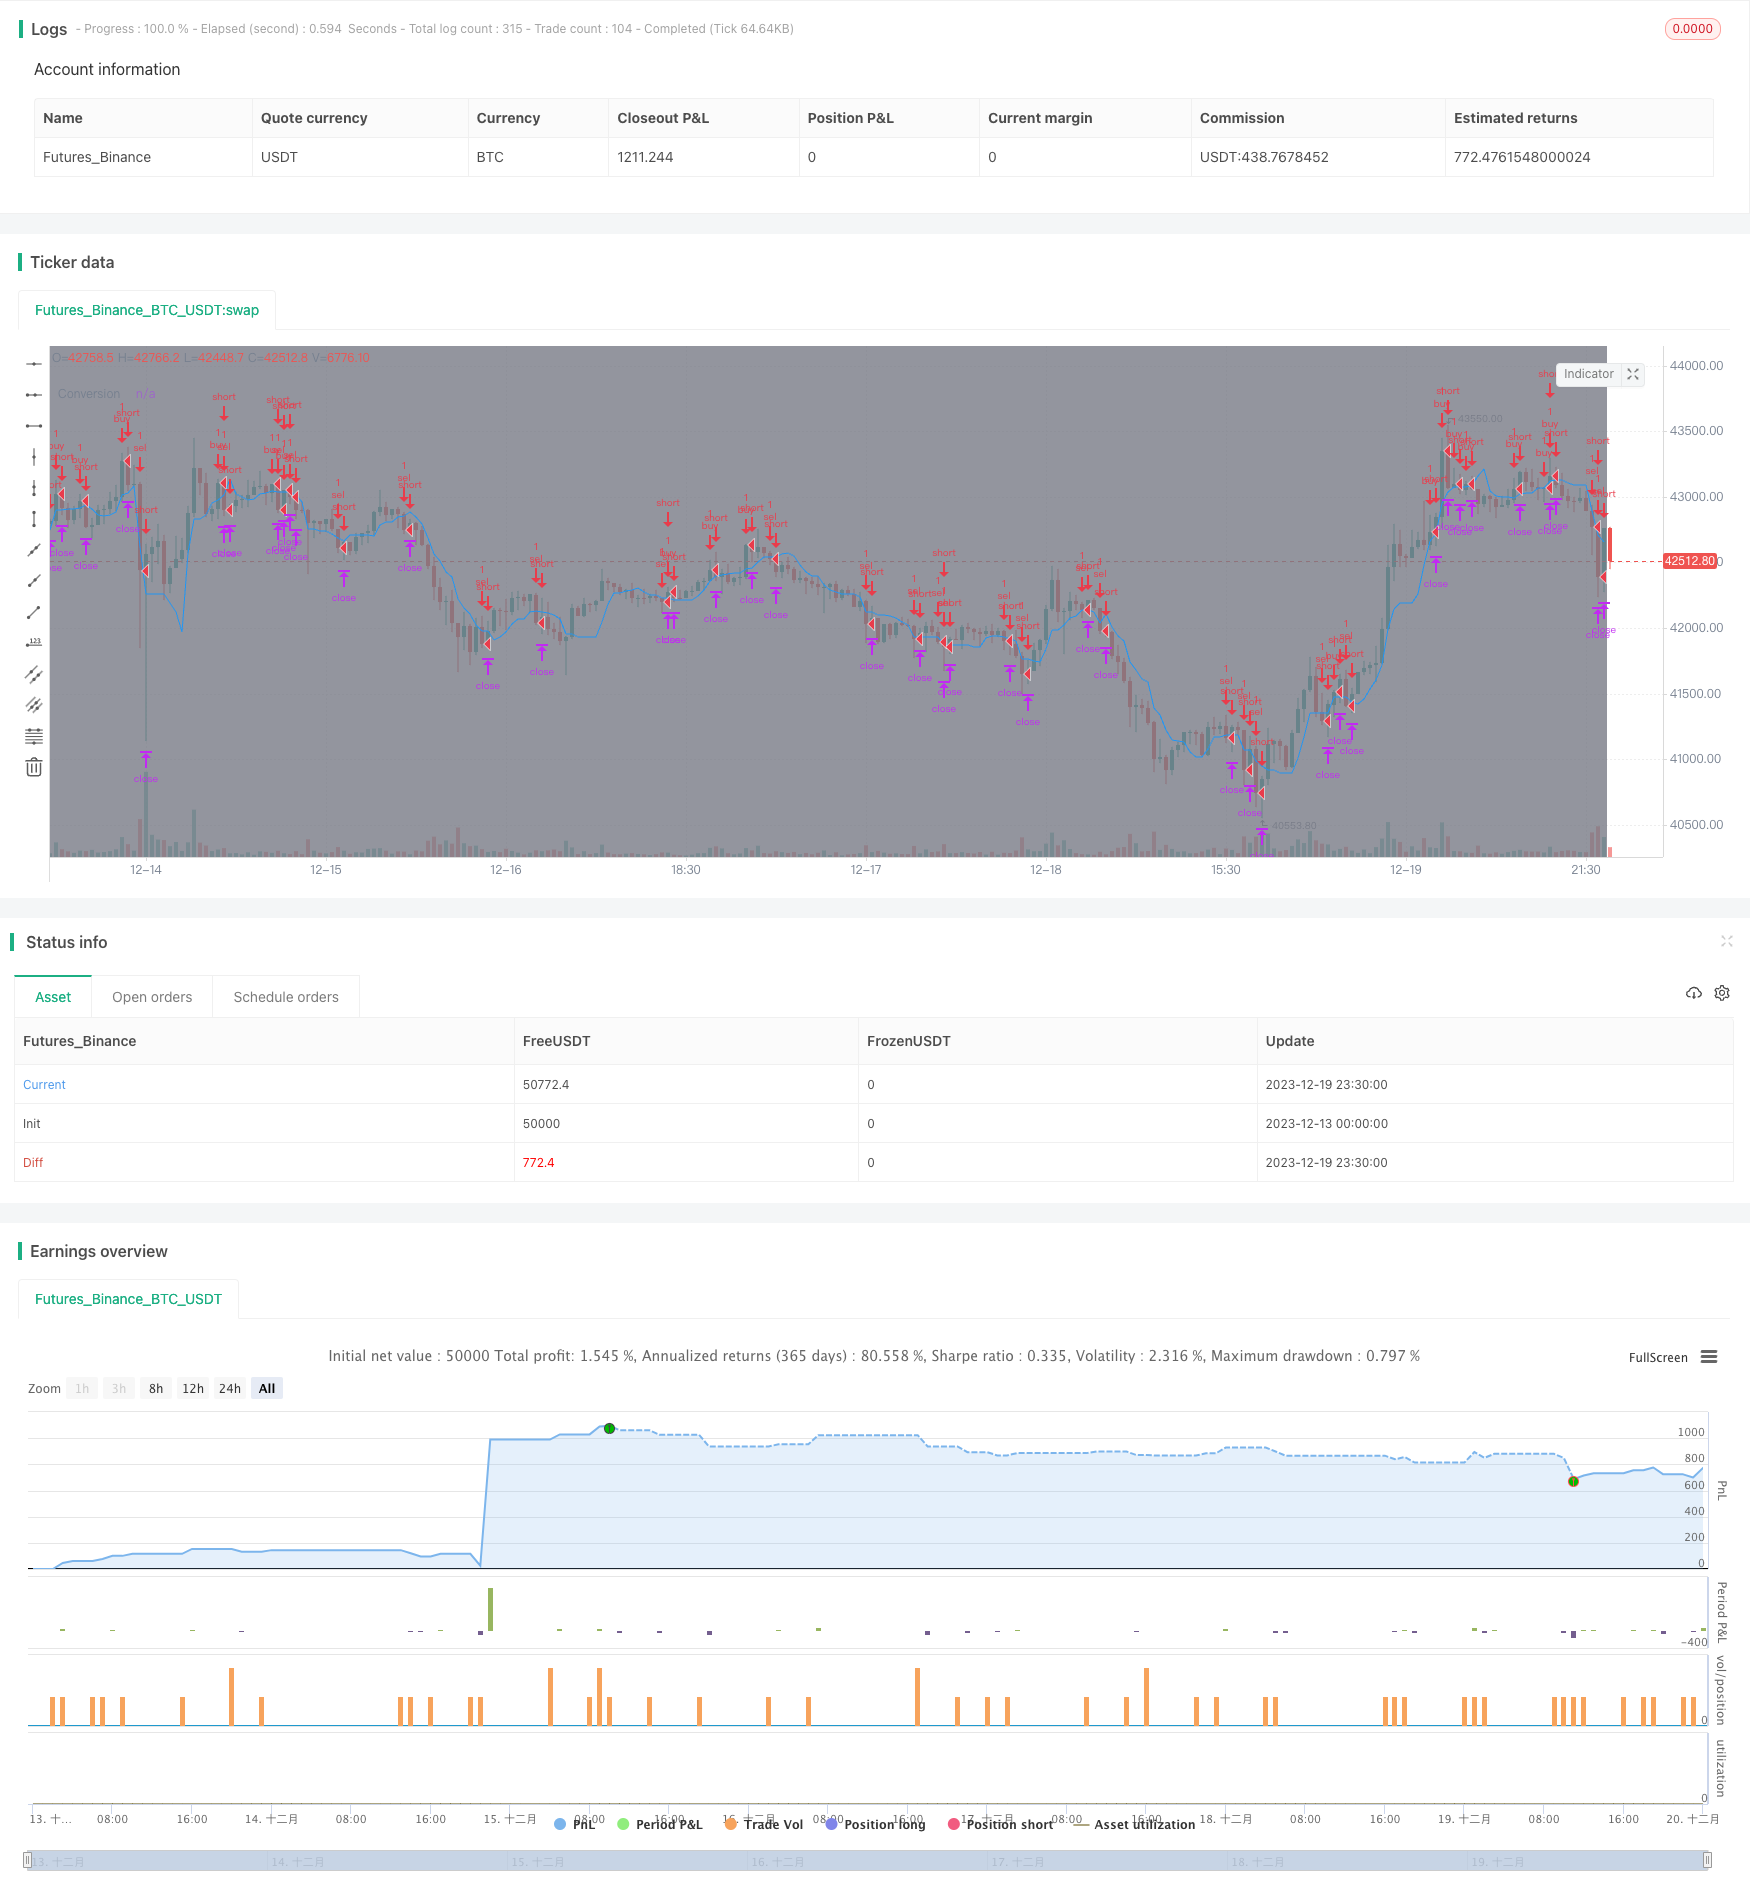
Overview
The Ichimoku Cloud Quant Scalping Strategy is a short-term quantitative strategy integrating Ichimoku Cloud and Average Directional Index (ADX). It utilizes Ichimoku Cloud to determine the trend direction and ADX to filter non-trending markets for scalping during trending conditions.
Strategy Logic
The strategy consists of two main components:
Ichimoku Cloud to judge the trend direction
- Conversion Line: middle price of last 7 periods
- Base Line: middle price of last 26 periods
- Leading Span A: midpoint of Conversion Line and Base Line
- Leading Span B: middle price of last 52 periods
Price above the cloud indicates an uptrend while below means a downtrend. The strategy uses the breakout of Conversion Line to determine the reversal of the trend.
ADX to filter non-trending market
Only taking signals when ADX is greater than 20, suggesting a trending market. No trade when ADX<20 during range-bound market.
Trade Rules:
- Long Entry: Price breaks above Conversion Line and ADX>20
- Short Entry: Price breaks below Conversion Line and ADX>20
- Stop Loss: 150 ticks
- Take Profit: 200 ticks
Advantage Analysis
The advantages of this strategy:
Following the trend, avoiding ranges. Ichimoku Cloud can accurately determine trend direction and turning points. ADX filters range-bound market to prevent false breakout.
Drawdown control. 150 ticks stop loss effectively limits per trade loss.
High profit factor. 200 ticks take profit vs 150 ticks stop loss gives a profit factor of 1.33, easy to gain profits.
Appropriate trading frequency. Only trading when a trend emerges prevents over-trading.
Risk Analysis
The risks are:
Trend determination failure risk. Incorrect signal when Ichimoku Cloud fails to detect trend reversal. Can optimize parameters to improve accuracy.
Stop loss being hit risk. Stop loss can be penetrated during fast market. Can use trailing stop loss or wider stop loss range.
Overnight and premarket trading risk. Default setting only allows day trading. Judgement may fail during extended hours. Can enable 24H trading or customize strategies for extended sessions.
Optimization Directions
The potential optimization directions:
Parameter tuning of Ichimoku Cloud to find the optimal setting.
ADX parameter and threshold optimization to determine the best values.
Profit target and stop loss optimization based on historical data.
Trailing stop loss to better follow the trend.
Additional indicators like MACD and KD to assist trend determination.
Adaptive optimization for different products.
Conclusion
The Ichimoku Cloud Quant Scalping Strategy integrates the advantages of Ichimoku Cloud and ADX to accurately determine trend reversal points and filter out range-bound markets. It has high profit factor, controllable drawdown, and is suitable for scalping along the trend. Further improvements on parameters, stop loss, auxiliary indicators can enhance the stability and profitability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 7 | Conversion Periods: |
| v_input_2 | 14 | Length |
| v_input_3 | 20 | threshold |
| v_input_4 | true | Use Trading Session? |
| v_input_5 | 0400-1500 | Trade Session: |
| v_input_6 | true | Trade Size: |
| v_input_7 | 150 | Stop Loss in ticks: |
| v_input_8 | 200 | Take Profit in ticks: |
Source Pine Script
/*backtest
start: 2023-12-13 00:00:00
end: 2023-12-20 00:00:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy(title='[STRATEGY][RS]Spot/Binary Scalper V0', shorttitle='IC', overlay=true, initial_capital=100000, currency=currency.USD)
//  ||  Adapted from:
//  ||      http://www.binaryoptionsedge.com/topic/1414-ta-spot-scalping-it-works-damn-good/?hl=singh

//  ||  Ichimoku cloud:
conversionPeriods = input(title='Conversion Periods:',  defval=7, minval=1),
basePeriods = 26//input(title='Base Periods',  defval=26, minval=1)
laggingSpan2Periods = 52//input(title='Lagging Span:',  defval=52, minval=1),
displacement = 26//input(title='Displacement:',  defval=26, minval=1)

f_donchian(_len) => avg(lowest(_len), highest(_len))

f_ichimoku_cloud(_conversion_periods, _base_periods, _lagging_span)=>
    _conversion_line = f_donchian(_conversion_periods)
    _base_line = f_donchian(_base_periods)
    _lead_line1 = avg(_conversion_line, _base_line)
    _lead_line2 = f_donchian(_lagging_span)
    [_conversion_line, _base_line, _lead_line1, _lead_line2]

[conversionLine, baseLine, leadLine1, leadLine2] = f_ichimoku_cloud(conversionPeriods, basePeriods, laggingSpan2Periods)

//ps0 = plot(title='A', series=leadLine1, color=green, linewidth=2)
//ps1 = plot(title='B', series=leadLine2, color=red, linewidth=2)
//fill(title='AB', plot1=ps0, plot2=ps1, color=blue, transp=80)
//plot(title='Base', series=baseLine, color=blue, linewidth=1, offset=displacement)
plot(title='Conversion', series=conversionLine, color=blue, linewidth=1)
//  ||----------------------------------------------------------------------------------------------------------------------------------------------||
//  ||  ADX
len = input(title="Length",  defval=14)
th = input(title="threshold",  defval=20)

TrueRange = max(max(high-low, abs(high-nz(close[1]))), abs(low-nz(close[1])))
DirectionalMovementPlus = high-nz(high[1]) > nz(low[1])-low ? max(high-nz(high[1]), 0): 0
DirectionalMovementMinus = nz(low[1])-low > high-nz(high[1]) ? max(nz(low[1])-low, 0): 0


SmoothedTrueRange = nz(SmoothedTrueRange[1]) - (nz(SmoothedTrueRange[1])/len) + TrueRange
SmoothedDirectionalMovementPlus = nz(SmoothedDirectionalMovementPlus[1]) - (nz(SmoothedDirectionalMovementPlus[1])/len) + DirectionalMovementPlus
SmoothedDirectionalMovementMinus = nz(SmoothedDirectionalMovementMinus[1]) - (nz(SmoothedDirectionalMovementMinus[1])/len) + DirectionalMovementMinus

DIPlus = SmoothedDirectionalMovementPlus / SmoothedTrueRange * 100
DIMinus = SmoothedDirectionalMovementMinus / SmoothedTrueRange * 100
DX = abs(DIPlus-DIMinus) / (DIPlus+DIMinus)*100
ADX = sma(DX, len)
//  ||----------------------------------------------------------------------------------------------------------------------------------------------||
//  ||  Trade session:
USE_TRADESESSION = input(title='Use Trading Session?', type=bool, defval=true)
trade_session = input(title='Trade Session:', defval='0400-1500', confirm=false)
istradingsession = not USE_TRADESESSION ? false : not na(time('1', trade_session))
bgcolor(istradingsession?gray:na)
//  ||----------------------------------------------------------------------------------------------------------------------------------------------||
//  ||  Strategy:
trade_size = input(title='Trade Size:',  defval=1)
stop_loss_in_ticks = input(title='Stop Loss in ticks:',  defval=150)
take_profit_in_ticks = input(title='Take Profit in ticks:',  defval=200)

buy_icloud_signal = open < conversionLine and close > conversionLine
buy_adx_signal = DIPlus > 20
buy_signal = istradingsession and buy_icloud_signal and buy_adx_signal

sel_icloud_signal = open > conversionLine and close < conversionLine
sel_adx_signal = DIMinus > 20
sel_signal = istradingsession and sel_icloud_signal and sel_adx_signal


strategy.order('buy', long=true, qty=trade_size, comment='buy', when=buy_signal)
strategy.order('sel', long=false, qty=trade_size, comment='sel', when=sel_signal)

strategy.exit('exit buy', from_entry='buy', profit=take_profit_in_ticks, loss=stop_loss_in_ticks)
strategy.exit('exit sel', from_entry='sel', profit=take_profit_in_ticks, loss=stop_loss_in_ticks)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Ichimoku-Cloud-Quant-Scalping-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Vitalik ScalpePine Script · Scalping
- Scalping EMA ADX RSI with Buy SellPine Script · Scalping · 5m
- Triple Moving Average Combined with MACD Quantitative StrategyPine Script · Machine learning · 1d
- Dual Moving Average Crossover Scalping StrategyPine Script · Scalping · 1h
- MACD Willy StrategyPine Script · Scalping · 1h
- Moving Average Scalping StrategyPine Script · Scalping · 4h