Strategy vault / Trend following
Ichimoku Kinko Hyo Cross Strategy
The Ichimoku Kinko Hyo Cross strategy generates trading signals by observing the crossovers between Tenkan-Sen and Kijun-Sen lines of the Ichimoku system, combined with the price level versus the Cloud. This strategy…
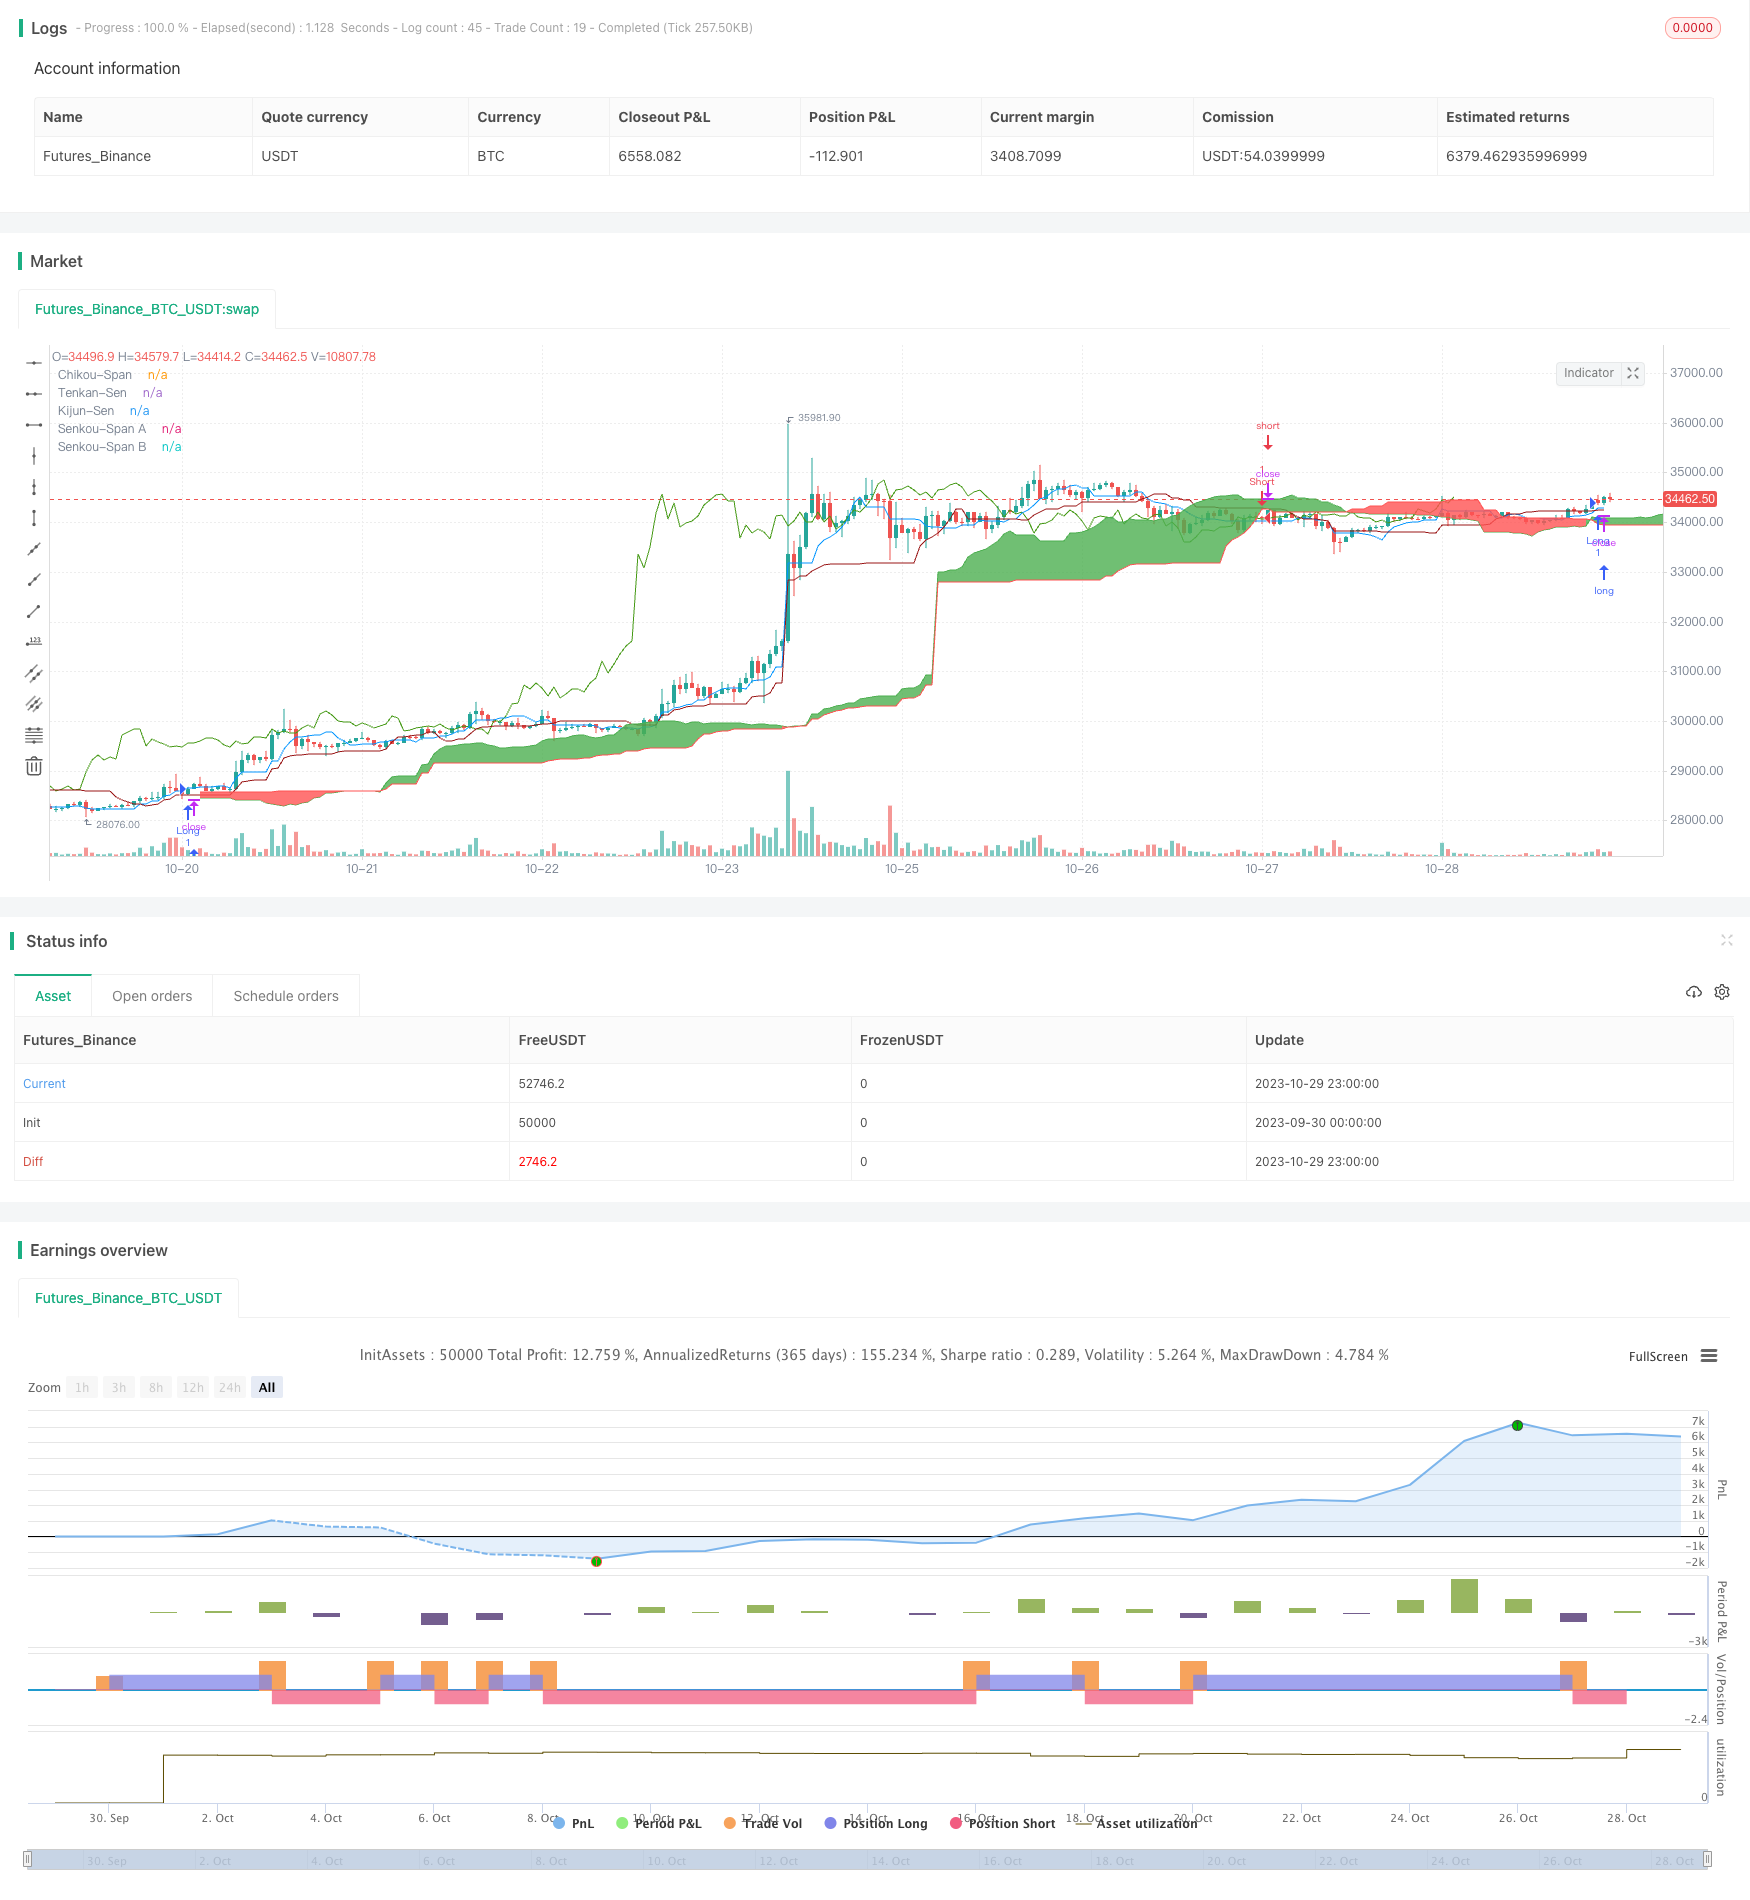
Overview
The Ichimoku Kinko Hyo Cross strategy generates trading signals by observing the crossovers between Tenkan-Sen and Kijun-Sen lines of the Ichimoku system, combined with the price level versus the Cloud. This strategy incorporates both trend following and reversal trading, making it a versatile and practical trading strategy.
Strategy Logic
Calculate the Ichimoku components:
Tenkan-Sen: Midpoint of last 9 bars
Kijun-Sen: Midpoint of last 26 bars
Senkou Span A: Average of Tenkan-Sen and Kijun-Sen
Senkou Span B: Midpoint of last 52 bars
Observe the combination of following trading signals:
Crossover between Tenkan-Sen and Kijun-Sen (Golden Cross and Death Cross)
Close price above or below the Cloud (Senkou Span A and B)
Chikou Span compared to close price 26 bars ago
Entry signals:
Long: Tenkan-Sen crosses above Kijun-Sen (Golden Cross) and close above Cloud and Chikou Span above close 26 bars ago
Short: Tenkan-Sen crosses below Kijun-Sen (Death Cross) and close below Cloud and Chikou Span below close 26 bars ago
Exit signals when opposite signal occurs.
Advantages
Combines trend following and reversal trading.
Crossovers ensure signal reliability and avoid false breakouts.
Multiple signal confirmation filters out market noise.
Chikou Span avoids whipsaws.
Cloud provides support and resistance for entries and exits.
Risks
Improper parameters may cause overtrading or unclear signals.
Trend reversals can lead to large losses.
Fewer trading opportunities during range-bound markets.
Delayed entry signals if Cloud is too wide.
High signal complexity increases implementation difficulty.
Risks can be mitigated through parameter optimization, position sizing, stop losses, liquid products, etc.
Enhancements
Optimize moving average periods for ideal frequency and profitability.
Add trend filter to avoid trend reversal losses.
Add volatility filter to control risk.
Optimize entry size and stop loss placement.
Add volume filter to ensure liquidity.
Test parameters across different products.
Employ machine learning to auto-optimize parameters based on backtests.
Conclusion
The Ichimoku Kinko Hyo Cross strategy combines various technical analysis tools like moving average crossovers, delayed lines, and Cloud bands to identify high-probability entries in trending or reversal scenarios. Proper optimization and risk management can further improve its stability and profitability. The strategy is easy to understand and implement, making it worth live testing and application.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 9 | Tenkan-Sen Bars |
| v_input_2 | 26 | Kijun-Sen Bars |
| v_input_3 | 52 | Senkou-Span B Bars |
| v_input_4 | 26 | Chikou-Span Offset |
| v_input_5 | 26 | Senkou-Span Offset |
| v_input_6 | true | Long Entry |
| v_input_7 | true | Short Entry |
Source Pine Script
/*backtest
start: 2023-09-30 00:00:00
end: 2023-10-30 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("Ichimoku Kinko Hyo: Basic Strategy", overlay=true)

//Inputs
ts_bars = input(9, minval=1, title="Tenkan-Sen Bars")
ks_bars = input(26, minval=1, title="Kijun-Sen Bars")
ssb_bars = input(52, minval=1, title="Senkou-Span B Bars")
cs_offset = input(26, minval=1, title="Chikou-Span Offset")
ss_offset = input(26, minval=1, title="Senkou-Span Offset")
long_entry = input(true, title="Long Entry")
short_entry = input(true, title="Short Entry")

middle(len) => avg(lowest(len), highest(len))

// Ichimoku Components
tenkan = middle(ts_bars)
kijun = middle(ks_bars)
senkouA = avg(tenkan, kijun)
senkouB = middle(ssb_bars)

// Plot Ichimoku Kinko Hyo
plot(tenkan, color=#0496ff, title="Tenkan-Sen")
plot(kijun, color=#991515, title="Kijun-Sen")
plot(close, offset=-cs_offset+1, color=#459915, title="Chikou-Span")
sa=plot(senkouA, offset=ss_offset-1, color=green, title="Senkou-Span A")
sb=plot(senkouB, offset=ss_offset-1, color=red, title="Senkou-Span B")
fill(sa, sb, color = senkouA > senkouB ? green : red, title="Cloud color")

ss_high = max(senkouA[ss_offset-1], senkouB[ss_offset-1])
ss_low = min(senkouA[ss_offset-1], senkouB[ss_offset-1])

// Entry/Exit Signals
tk_cross_bull = tenkan > kijun
tk_cross_bear = tenkan < kijun
cs_cross_bull = mom(close, cs_offset-1) > 0
cs_cross_bear = mom(close, cs_offset-1) < 0
price_above_kumo = close > ss_high
price_below_kumo = close < ss_low

bullish = tk_cross_bull and cs_cross_bull and price_above_kumo
bearish = tk_cross_bear and cs_cross_bear and price_below_kumo

strategy.entry("Long", strategy.long, when=bullish and long_entry)
strategy.entry("Short", strategy.short, when=bearish and short_entry)

strategy.close("Long", when=bearish and not short_entry)
strategy.close("Short", when=bullish and not long_entry)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-31. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Ichimoku-Kinko-Hyo-Cross-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Ichimoku Trend Following StrategyPine Script · Trend following · 1d
- EMA SMA Trend Following with Swing Trading Strategy Combined Volume Filter and Percentage Take Profit Stop Loss SystemPine Script · Trend following · 1d
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Factor Trend Price Action Strategy with Dynamic Risk Management SystemPine Script · Trend following · 2h
- Multi Level Dynamic MACD Trend Following Strategy with 52 Week High Low Extension Analysis SystemPine Script · Trend following · 1d
- Trend Detection Strategy Based on Gaussian Channel and Stochastic RSI FilterPine Script · Trend following · 1h