Ichimoku Kinko Hyo Trading Strategy
The Ichimoku Kinko Hyo trading strategy is a trend-following strategy based on the Ichimoku technical indicator. It uses the conversion line, base line, leading span 1, leading span 2 and other indicators of the…
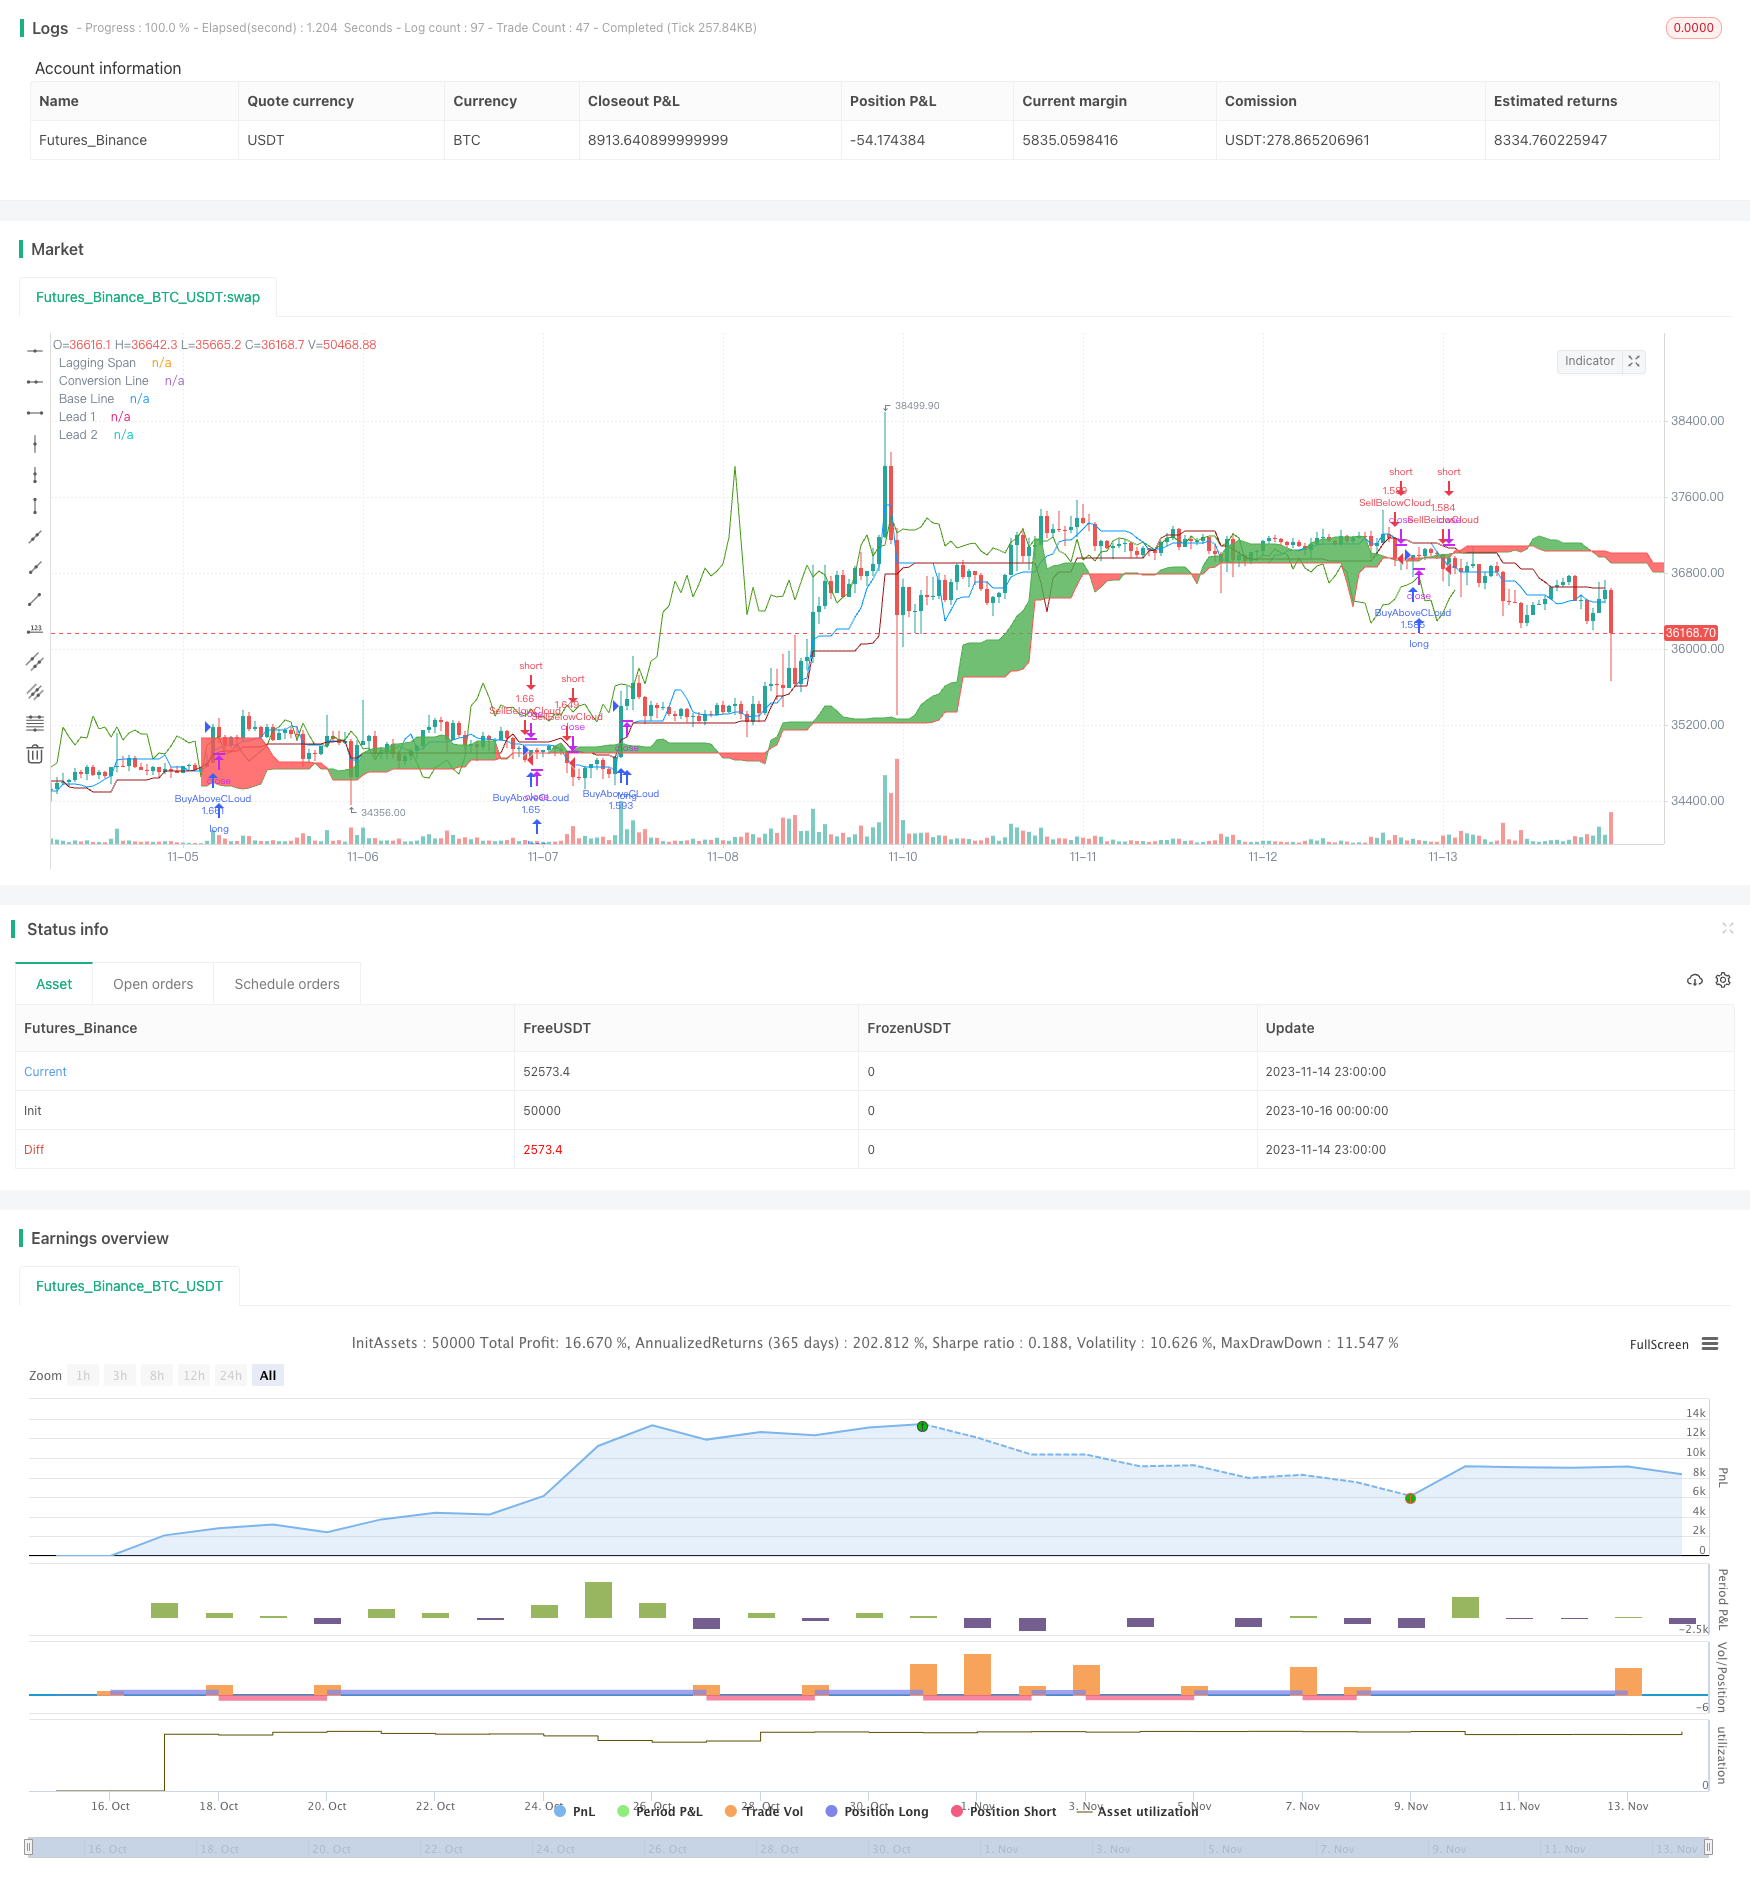
Overview
The Ichimoku Kinko Hyo trading strategy is a trend-following strategy based on the Ichimoku technical indicator. It uses the conversion line, base line, leading span 1, leading span 2 and other indicators of the Ichimoku system to determine trend direction and timing of entry and exit.
Strategy Logic
The strategy mainly judges the following four conditions to decide the trading direction:
- Go long when the closing price crosses above the 26-period average of the top of the cloud
- Go short when the closing price crosses below the 26-period average of the bottom of the cloud
- Take profit condition: 3.5%
- Stop loss condition: 1.5%
Specifically, the strategy first calculates the conversion line, base line, leading span 1 and leading span 2. It then determines whether to go long or short based on if the closing price breaks through the top or bottom of the cloud.
If the closing price crosses above the top of the cloud, i.e. above the 26-period average of the greater value between leading span 1 and leading span 2, it indicates an upward trend and goes long.
If the closing price crosses below the bottom of the cloud, i.e. below the 26-period average of the lower value between leading span 1 and leading span 2, it indicates a downward trend and goes short.
After entry, take profit and stop loss conditions are set. Take profit is set at 3.5% of entry price and stop loss is 1.5% of entry price.
Advantage Analysis
The Ichimoku Kinko Hyo trading strategy has the following advantages:
- Ability to identify trend changes early and enter trends in a timely manner
- Using the cloud to determine support and resistance areas makes entries more accurate
- Considers both price and volume to avoid false breakouts
- Clear profit taking and stop loss conditions to control trading risk
Risk Analysis
The Ichimoku Kinko Hyo trading strategy also has some risks:
- It can produce multiple small losses in range-bound markets
- Stop loss can be large if the major trend reverses
- Needs multiple conditions to be met which reduces opportunities
- Incorrect parameter settings may misinterpret indicator signals
Solutions:
- Relax entry conditions to increase opportunities
- Optimize parameters to fit market characteristics better
- Add filters with other indicators to avoid false signals
Optimization Directions
The Ichimoku Kinko Hyo trading strategy can be optimized in the following aspects:
- Optimize conversion line, base line and other parameters to fit different period market conditions
- Optimize entry conditions to capitalize on more opportunities
- Optimize take profit and stop loss strategies for higher risk-adjusted returns
- Add filters with other indicators to reduce whipsaws
- Dynamically adjust position sizing based on market volatility
Summary
The Ichimoku Kinko Hyo trading strategy is an overall relatively good strategy that can capture potential trends in a timely manner. But it still needs further optimization and combination with other indicators to form a robust trading system. By adjusting parameters, improving entry and exit techniques, and controlling risks, Ichimoku strategy can achieve higher risk-adjusted returns in trending markets.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | false | only shows buying Trade |
| v_input_2 | 9 | Conversion Line Periods |
| v_input_3 | 26 | Base Line Periods |
| v_input_4 | 52 | Lagging Span 2 Periods |
| v_input_5 | 26 | Displacement |
| v_input_6 | 3.5 | enter target in % after entry |
| v_input_7 | 1.5 | enter Stoploss in % after entry |
Source Pine Script
/*backtest
start: 2023-10-16 00:00:00
end: 2023-11-15 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("Ichimoku system", overlay=true, initial_capital = 100000, default_qty_type = strategy.percent_of_equity, default_qty_value=100)

buyOnly = input(false, "only shows buying Trade", type = input.bool)


conversionPeriods = input(9, minval=1, title="Conversion Line Periods"),
basePeriods = input(26, minval=1, title="Base Line Periods")
laggingSpan2Periods = input(52, minval=1, title="Lagging Span 2 Periods"),
displacement = input(26, minval=1, title="Displacement")

donchian(len) => avg(lowest(len), highest(len))

conversionLine = donchian(conversionPeriods)
baseLine = donchian(basePeriods)
leadLine1 = avg(conversionLine, baseLine)
leadLine2 = donchian(laggingSpan2Periods)

plot(conversionLine, color=#0496ff, title="Conversion Line")
plot(baseLine, color=#991515, title="Base Line")
plot(close, offset = -displacement + 1, color=#459915, title="Lagging Span")

p1 = plot(leadLine1, offset = displacement - 1, color=color.green,
 title="Lead 1")
p2 = plot(leadLine2, offset = displacement - 1, color=color.red,
 title="Lead 2")
fill(p1, p2, color = leadLine1 > leadLine2 ? color.green : color.red)


profit = input(3.5, "enter target in % after entry", step = 0.5)

stoploss = input(1.5, "enter Stoploss in % after entry", step = 0.5)


sl = stoploss /100 * strategy.position_avg_price / syminfo.mintick

profitt = profit /100 * strategy.position_avg_price / syminfo.mintick


abovecloud =  max(leadLine1, leadLine2)

belowcloud = min(leadLine1, leadLine2)


buying = close > abovecloud[26] and close[1] < abovecloud[27]

selling = close < belowcloud[26] and close[1] > belowcloud[27]

strategy.entry("BuyAboveCLoud", true, when = buying)

if buyOnly
    strategy.close("BuyAboveCLoud", when = selling)
else
    strategy.entry("SellBelowCloud", false, when = selling)

//strategy.exit("Exit Position", "BuyAboveCLoud", profit = profitt, loss = sl)


//strategy.exit("Exit Position", "SellBelowCloud", profit = profitt, loss = sl)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Ichimoku-Kinko-Hyo-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Short Term Algorithmic Trading StrategyPine Script · Breakout · 4h
- Ichimoku Cloud Market Analysis StrategyPine Script · Breakout · 5m
- Dynamic Filter Quant Trading StrategyPine Script · Breakout · 1d
- Price Deviation from Daily Average Trading StrategyPine Script · Breakout · 1d
- Donchian Channel Breakout Strategy 442842Pine Script · Breakout · 4h
- Ichimoku Stop Loss StrategyPine Script · Breakout · 1d