Strategy vault / Trend following
Improved Wave Trend Tracking Strategy
Overview: This is a trend following strategy that utilizes the Wave Trend oscillator to identify trends. It calculates exponential moving averages of the average price and absolute price difference to plot a Wave…
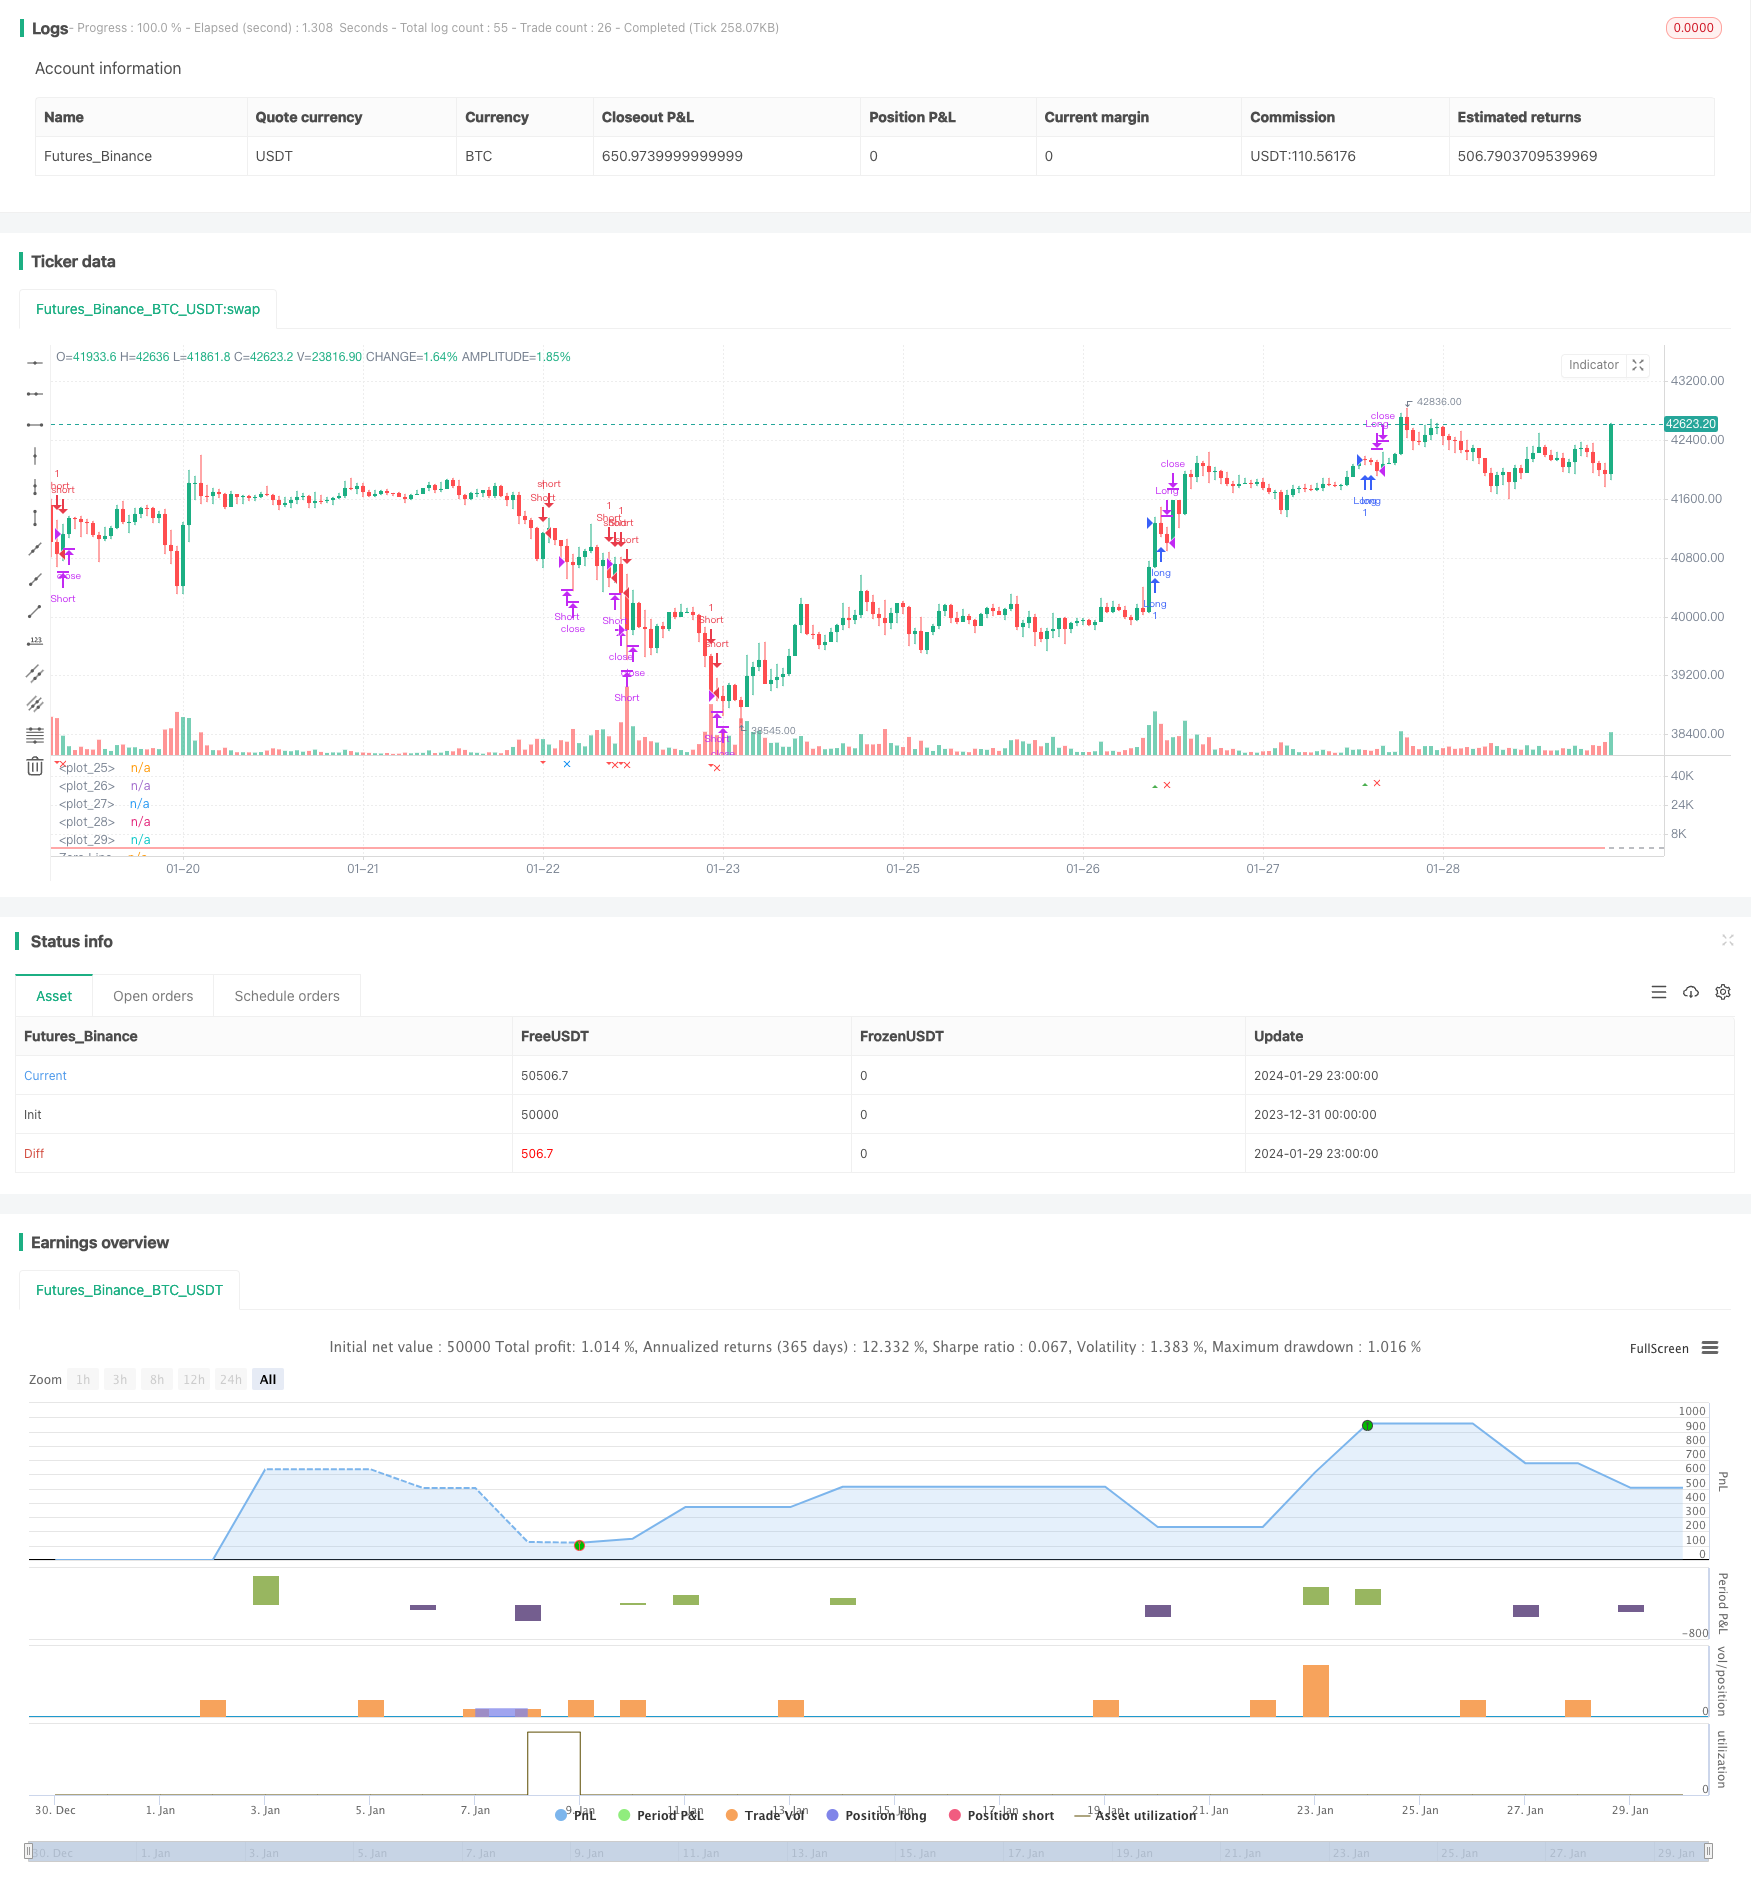
Overview: This is a trend following strategy that utilizes the Wave Trend oscillator to identify trends. It calculates exponential moving averages of the average price and absolute price difference to plot a Wave Trend line. Trading signals are generated when the Wave Trend line crosses overbought/oversold zones. Additional filters on moving average and volume avoid false signals.
Strategy Logic:
Calculate average price ap = (high + low + close)/3
Compute n1-period EMA of ap to get esa
Compute n1-period EMA of absolute difference between ap and esa to get d
Compute Wave Trend line: ci = (ap - esa)/(0.015*d)
Compute n2-period EMA of ci to get final wave trend line tci, i.e. wt1
Compute 4-period SMA of wt1 to get wt2
Plot overbought/oversold level lines obLevel1/2 and osLevel1/2
Generate buy signal when wt1 crosses over obLevel2; generate sell signal when wt1 crosses below osLevel2
Add moving average emaFilter and volume filter volumeFilter as filters to avoid false signals
Set take profit/stop loss after entry to exit positions
Advantages:
Wave Trend line handles trend/counter-trend transitions well
Reliability improved through dual filters of moving average and volume
Multiple parameters avoid limitations of single indicator
Take profit/stop loss locks in profits and controls risk
Risks and Limitations:
Choice of parameters can lead to poor performance or overfitting
No definitive guidance on optimal parameters
Ignores broader market conditions
Risk of whip-saws in range-bound/choppy markets
Lack of exit rules besides take profit/stop loss
Enhancement Opportunities:
Test parameters across timeframes/assets to find optimal values
Incorporate volatility metrics to avoid low volatility regimes
Add indicators like RSI to improve signal accuracy
Build machine learning model to find optimal tailored parameters
Enhance exits with trailing stops or volatility event based exits
Conclusion:
This is a trend following strategy incorporating the Wave Trend indicator with additional filters. It capitalizes on the Wave Trend line's ability to identify trend transitions, uses moving average and volume filters to avoid false signals, and aims to capture most medium/long term trends. Take profit/stop loss is used to control risk. Significant opportunity exists to improve performance across more instruments and timeframes by optimizing parameters, adding more indicators, and techniques like machine learning.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | Channel Length |
| v_input_2 | 21 | Average Length |
| v_input_3 | 60 | Over Bought Level 1 |
| v_input_4 | 53 | Over Bought Level 2 |
| v_input_5 | -65 | Over Sold Level 1 |
| v_input_6 | -60 | Over Sold Level 2 |
| v_input_7 | true | Take Profit (%) |
| v_input_8 | 0.5 | Stop Loss (%) |
Source Pine Script
/*backtest
start: 2023-12-31 00:00:00
end: 2024-01-30 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Bush Strategy test", shorttitle="Nique Audi", overlay=false)

// Paramètres
n1 = input(10, title="Channel Length")
n2 = input(21, title="Average Length")
obLevel1 = input(60, title="Over Bought Level 1")
obLevel2 = input(53, title="Over Bought Level 2")
osLevel1 = input(-65, title="Over Sold Level 1")
osLevel2 = input(-60, title="Over Sold Level 2")
takeProfitPercentage = input(1, title="Take Profit (%)")
stopLossPercentage = input(0.50, title="Stop Loss (%)")

// Calculs
ap = hlc3
esa = ta.ema(ap, n1)
d = ta.ema(math.abs(ap - esa), n1)
ci = (ap - esa) / (0.015 * d)
tci = ta.ema(ci, n2)

wt1 = tci
wt2 = ta.sma(wt1, 4)

// Tracé des lignes
plot(0, color=color.gray)
plot(obLevel1, color=color.red)
plot(osLevel1, color=color.green)
plot(obLevel2, color=color.red, style=plot.style_line)
plot(osLevel2, color=color.green, style=plot.style_line)

plot(wt1, color=color.green)
plot(wt2, color=color.red, style=plot.style_line)

// Tracé de la différence entre wt1 et wt2 en bleu
hline(0, "Zero Line", color=color.gray)

// Conditions d'entrée long et court
longCondition = ta.crossover(wt1, obLevel2)
shortCondition = ta.crossunder(wt1, osLevel2)

// Tracé des signaux d'achat et de vente
plotshape(series=longCondition, style=shape.triangleup, location=location.belowbar, color=color.green, size=size.small, title="Buy Signal")
plotshape(series=shortCondition, style=shape.triangledown, location=location.abovebar, color=color.red, size=size.small, title="Sell Signal")

// Conditions d'entrée et de sortie
strategy.entry("Long", strategy.long, when=longCondition)
strategy.entry("Short", strategy.short, when=shortCondition)

// Niveaux de prise de profit pour les positions longues et courtes
longTakeProfitLevel = strategy.position_avg_price * (1 + takeProfitPercentage / 100)
shortTakeProfitLevel = strategy.position_avg_price * (1 - takeProfitPercentage / 100)

// Vérification si les niveaux de prise de profit sont atteints
longTakeProfitReached = strategy.position_size > 0 and high >= longTakeProfitLevel
shortTakeProfitReached = strategy.position_size < 0 and low <= shortTakeProfitLevel

// Tracé des formes de prise de profit
plotshape(series=longTakeProfitReached, style=shape.xcross, location=location.belowbar, color=color.blue, size=size.small, title="Take Profit Long")
plotshape(series=shortTakeProfitReached, style=shape.xcross, location=location.abovebar, color=color.blue, size=size.small, title="Take Profit Short")

// Niveaux de stop loss pour les positions longues et courtes
longStopLossLevel = strategy.position_avg_price * (1 - stopLossPercentage / 100)
shortStopLossLevel = strategy.position_avg_price * (1 + stopLossPercentage / 100)

// Vérification si les niveaux de stop loss sont atteints
longStopLossReached = strategy.position_size > 0 and low <= longStopLossLevel
shortStopLossReached = strategy.position_size < 0 and high >= shortStopLossLevel

// Tracé des formes de stop loss
plotshape(series=longStopLossReached, style=shape.xcross, location=location.belowbar, color=color.red, size=size.small, title="Stop Loss Long")
plotshape(series=shortStopLossReached, style=shape.xcross, location=location.abovebar, color=color.red, size=size.small, title="Stop Loss Short")

// Fermeture des positions en cas de prise de profit ou de stop loss
strategy.close("Long", when=longTakeProfitReached or longStopLossReached)
strategy.close("Short", when=shortTakeProfitReached or shortStopLossReached)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-31. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Improved-Wave-Trend-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- YinYang RSI Volume Trend Trading StrategyPine Script · Trend following · 1h
- Dynamic ATR Trailing Stop with EMA Cross Combination StrategyPine Script · Trend following · 2h
- Five Minute Triple Confirmation Trend Trading Strategy with Risk Management SystemPine Script · Trend following · 1m
- Moving Average Crossover Strategy 427164Pine Script · Trend following · 10m
- Moving Average Crossover Strategy 430371Pine Script · Trend following · 1h