Integrated Ichimoku Keltner Trading System Based on Moving Average Strategy
This strategy integrates moving average strategy, Ichimoku cloud charts and Keltner channel technical indicators to achieve trend following and breakthrough trading, which is suitable for high-frequency algorithmic…
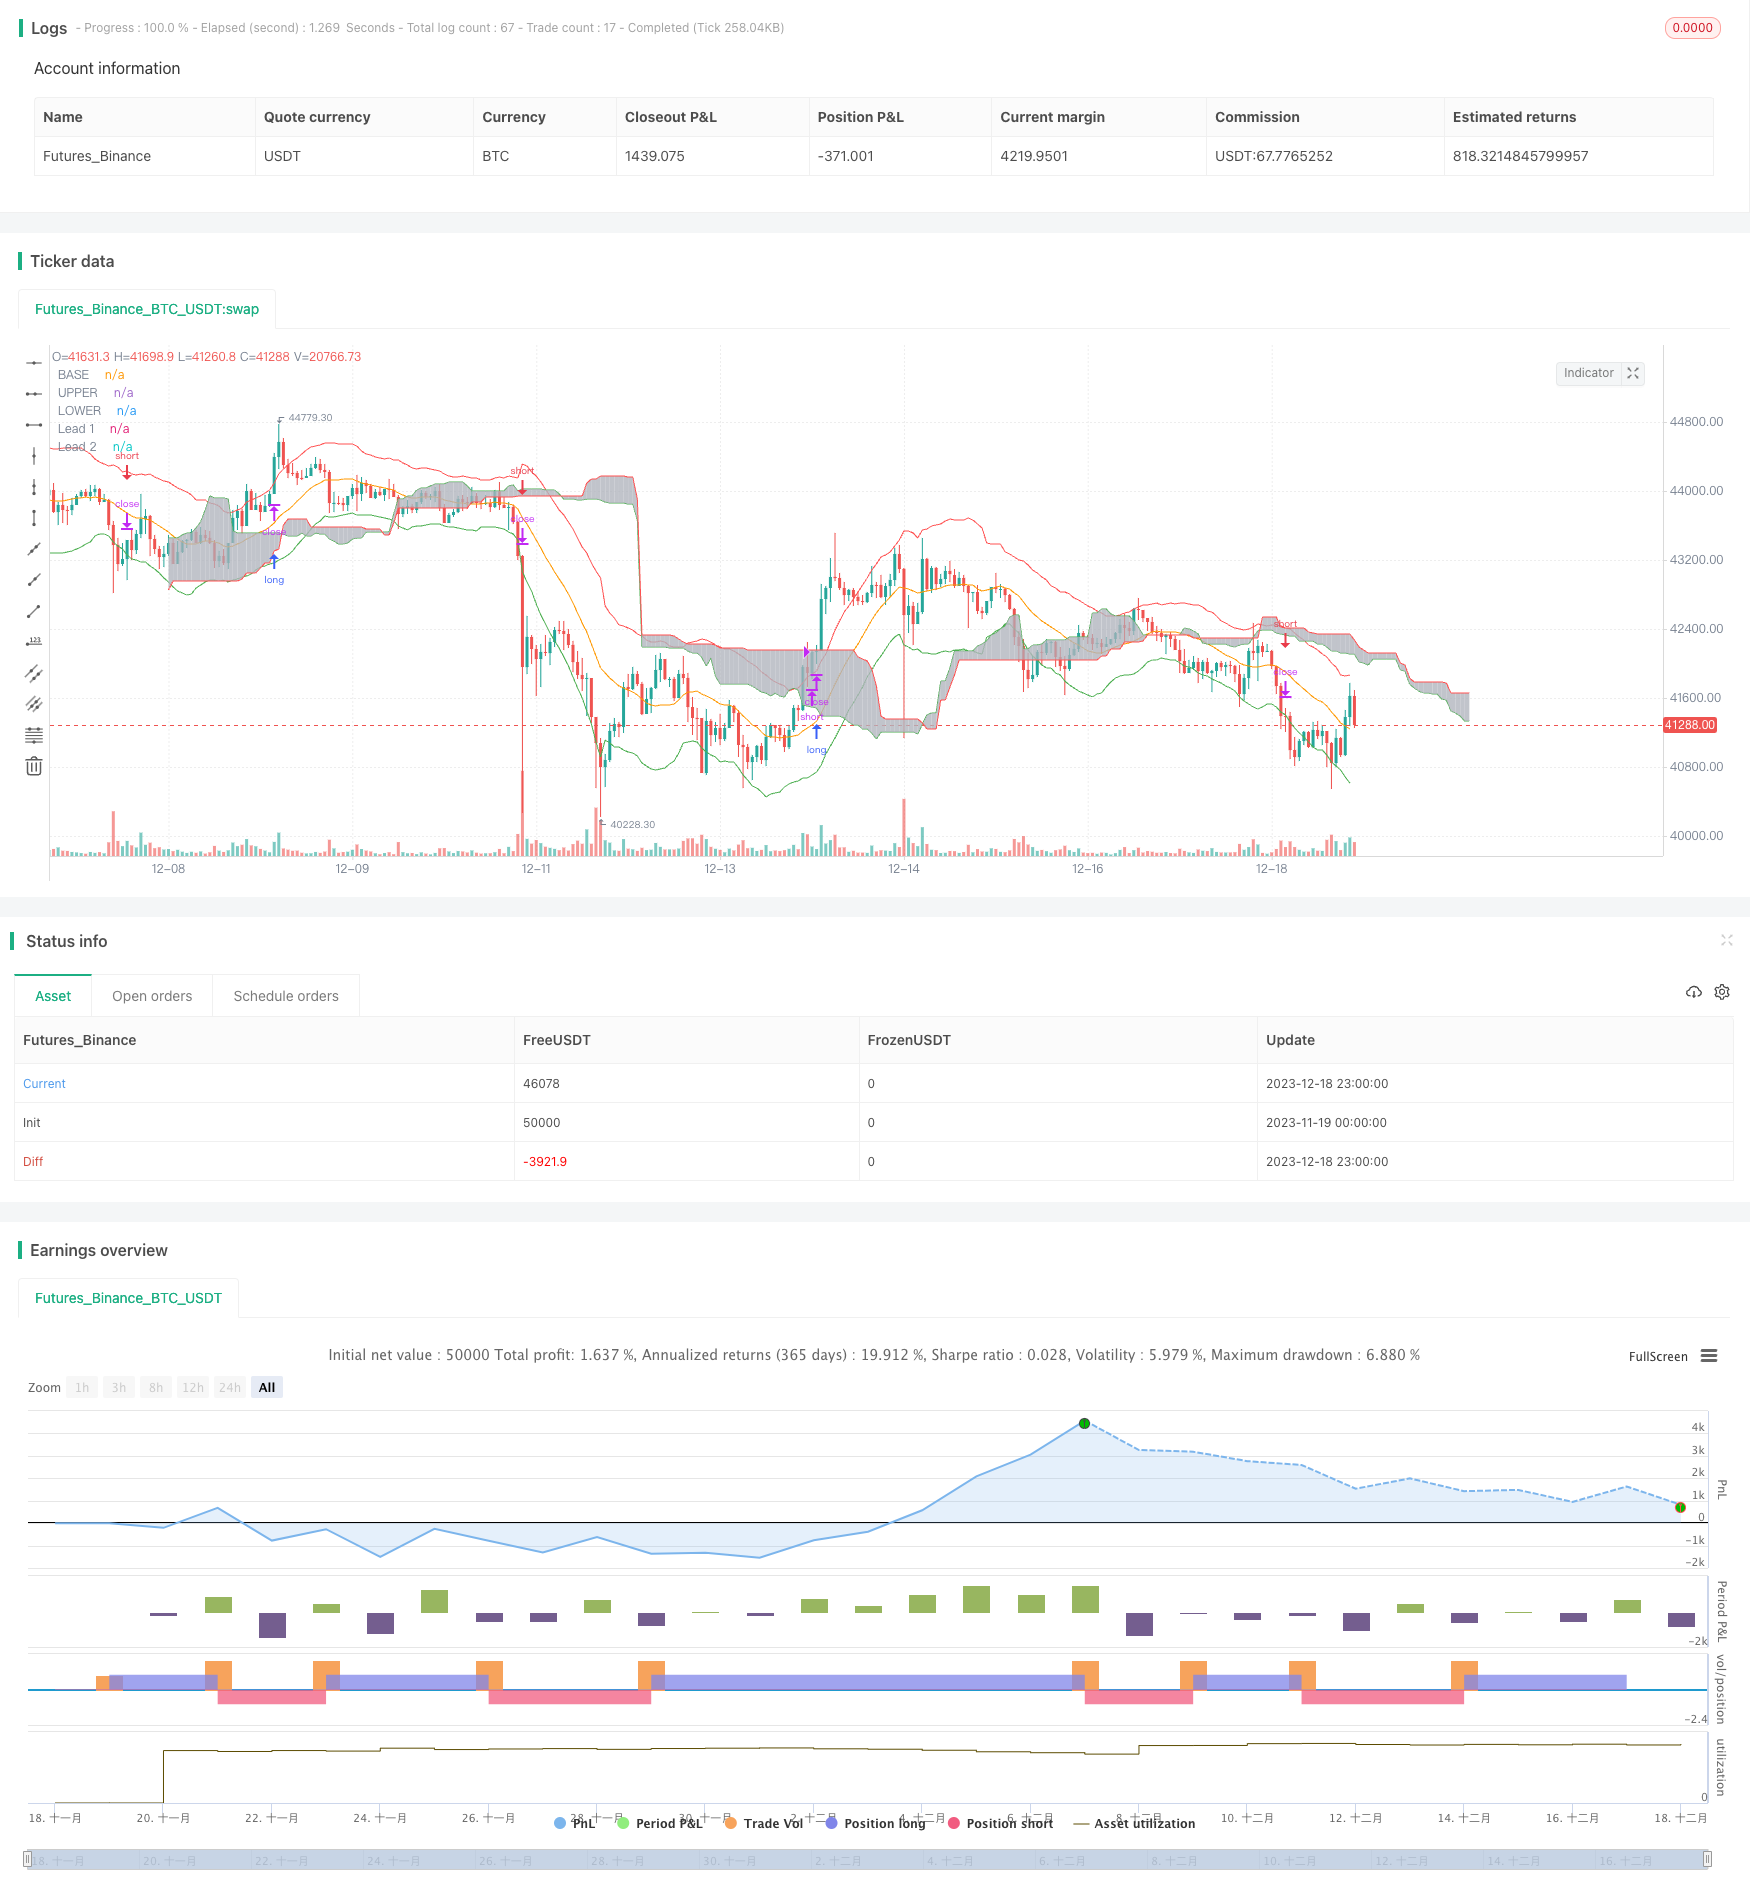
Overview
This strategy integrates moving average strategy, Ichimoku cloud charts and Keltner channel technical indicators to achieve trend following and breakthrough trading, which is suitable for high-frequency algorithmic trading.
Strategy Principle
- Use Keltner channel to judge whether the stock price exceeds the upper and lower rails of the channel as a signal for opening positions
- Ichimoku cloud charts judge the trend direction and use with Keltner channel
- Moving average strategy sends closing signals
Advantage Analysis
- Integrate multiple technical indicators for comprehensive judgment to improve decision accuracy
- Keltner channel judges overbought and oversold conditions to avoid chasing highs and killing lows when opening positions
- Ichimoku cloud charts judge major trends to avoid trading against the trend
- Moving average strategy filters shocks and prevents excessive sensitivity
Risk Analysis
- The integration of multiple indicators makes parameter settings more complex and requires careful testing
- The crossing of conversion line and baseline of cloud charts is not always a reliable trading signal
- The Keltner channel needs to adjust parameters to adapt to the characteristics of different stocks
Optimization Directions
- Evaluate server performance and appropriately shorten moving average cycles to increase trading frequency
- Test the sensitivity of different stocks to parameters and set adaptive parameters
- Increase stop loss strategy to reduce single loss
Summary
This strategy integrates Ichimoku cloud charts, Keltner channels and moving average strategies with multiple technical indicators to achieve trend tracking and efficient breakthrough trading. Compared with a single indicator, the judgment of this strategy is more comprehensive and accurate, avoiding certain false signals. At the same time, there are also problems that the parameter settings are more complex and need to be optimized for individual stocks. In general, this strategy is suitable for high-frequency algorithmic trading with significant effects.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | useTrueRange |
| v_input_2 | 18 | length |
| v_input_3 | 1.8 | mult |
| v_input_4 | 200 | ATRlength |
| v_input_5 | 2.272 | ATRMult |
| v_input_6 | 26 | EMA Length |
| v_input_7_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_8 | 15 | conversionPeriods |
| v_input_9 | 35 | basePeriods |
| v_input_10 | 52 | laggingSpan2Periods |
| v_input_11 | 26 | displacement |
Source Pine Script
/*backtest
start: 2023-11-19 00:00:00
end: 2023-12-19 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
// Author: Persio Flexa
// Description: Ichimoku Clouds with Keltner Channel, perfect for margin trading
strategy("Ichimoku Keltner Strategy", overlay=true)

// -- Keltner ------------------------------------------------------------------
source = close

useTrueRange = input(true)
length = input(18, minval=1)
mult = input(1.8)

ma = sma(source, length)
range = useTrueRange ? tr : high - low
rangema = sma(range, length)
upper = ma + rangema * mult
lower = ma - rangema * mult

plot(ma, title="BASE", color=orange,transp=85)
plot(upper, title="UPPER", color=red)
plot(lower, title="LOWER", color=green)

//crossUpper = crossover(source, upper)
//crossLower = crossunder(source, lower)
crossUpper = source > upper
crossLower = source  < lower

bprice = 0.0
bprice := crossUpper ? high+syminfo.mintick : nz(bprice[1])

sprice = 0.0
sprice := crossLower ? low -syminfo.mintick : nz(sprice[1])

crossBcond = false
crossBcond := crossUpper ? true
 : na(crossBcond[1]) ? false : crossBcond[1]

crossScond = false
crossScond := crossLower ? true
 : na(crossScond[1]) ? false : crossScond[1]

cancelBcond = crossBcond and (source < ma or high >= bprice )
cancelScond = crossScond and (source > ma or low <= sprice )

// ---------------------------------------------------------------------


// -- Ichimoku

ATRlength = input(200, minval=1)
ATRMult = input(2.272, minval=1)

ATR = rma(tr(true), ATRlength)

len = input(26, minval=1, title="EMA Length")
src = input(close, title="Source")
out = ema(src, len)

emaup = out+(ATR*ATRMult)
emadw = out-(ATR*ATRMult)

conversionPeriods = input(15, minval=1),
basePeriods = input(35, minval=1)
laggingSpan2Periods = input(52, minval=1),
displacement = input(26, minval=1)

donchian(len) => avg(lowest(len), highest(len))

conversionLine = donchian(conversionPeriods)
baseLine = donchian(basePeriods)
leadLine1 = avg(conversionLine, baseLine)
leadLine2 = donchian(laggingSpan2Periods)

p1 = plot(leadLine1, offset = displacement, color=green,transp=85, title="Lead 1")
p2 = plot(leadLine2, offset = displacement, color=red,transp=85, title="Lead 2")
fill(p1, p2,silver)

longCond    = crossover(conversionLine, baseLine)
shortCond   = crossunder(conversionLine, baseLine)
// -------------------------------------------------------------------------

if (crossUpper and (conversionLine > baseLine))
    strategy.entry("long", strategy.long, stop=bprice, comment="LONG")

if (crossLower and (conversionLine < baseLine))
    strategy.entry("short", strategy.short, stop=sprice, comment="SHORT")

strategy.close("long", when = (shortCond and source < lower))
strategy.close("short", when = (longCond and source > upper))Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Integrated-Ichimoku-Keltner-Trading-System-Based-on-Moving-Average-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- MACD Bollinger Turtle Trading StrategyPine Script · Breakout · 1d
- Donchian Channel and Larry Williams Large Trade Index StrategyPine Script · Breakout · 1m
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h
- Flexible Long Short Trading Strategy Based on Keltner ChannelsPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 435896Pine Script · Breakout · 1d
- Multi Indicator Trend Breakout Strategy with Dynamic Stop LossPine Script · Breakout · 1d