Strategy vault / Machine learning
Intelligent Exponential Moving Average Trading Strategy Optimization System
This is an intelligent trading strategy system based on Exponential Moving Average (EMA). The strategy utilizes crossover signals between short-term and long-term EMAs, combined with price-EMA relationships to…
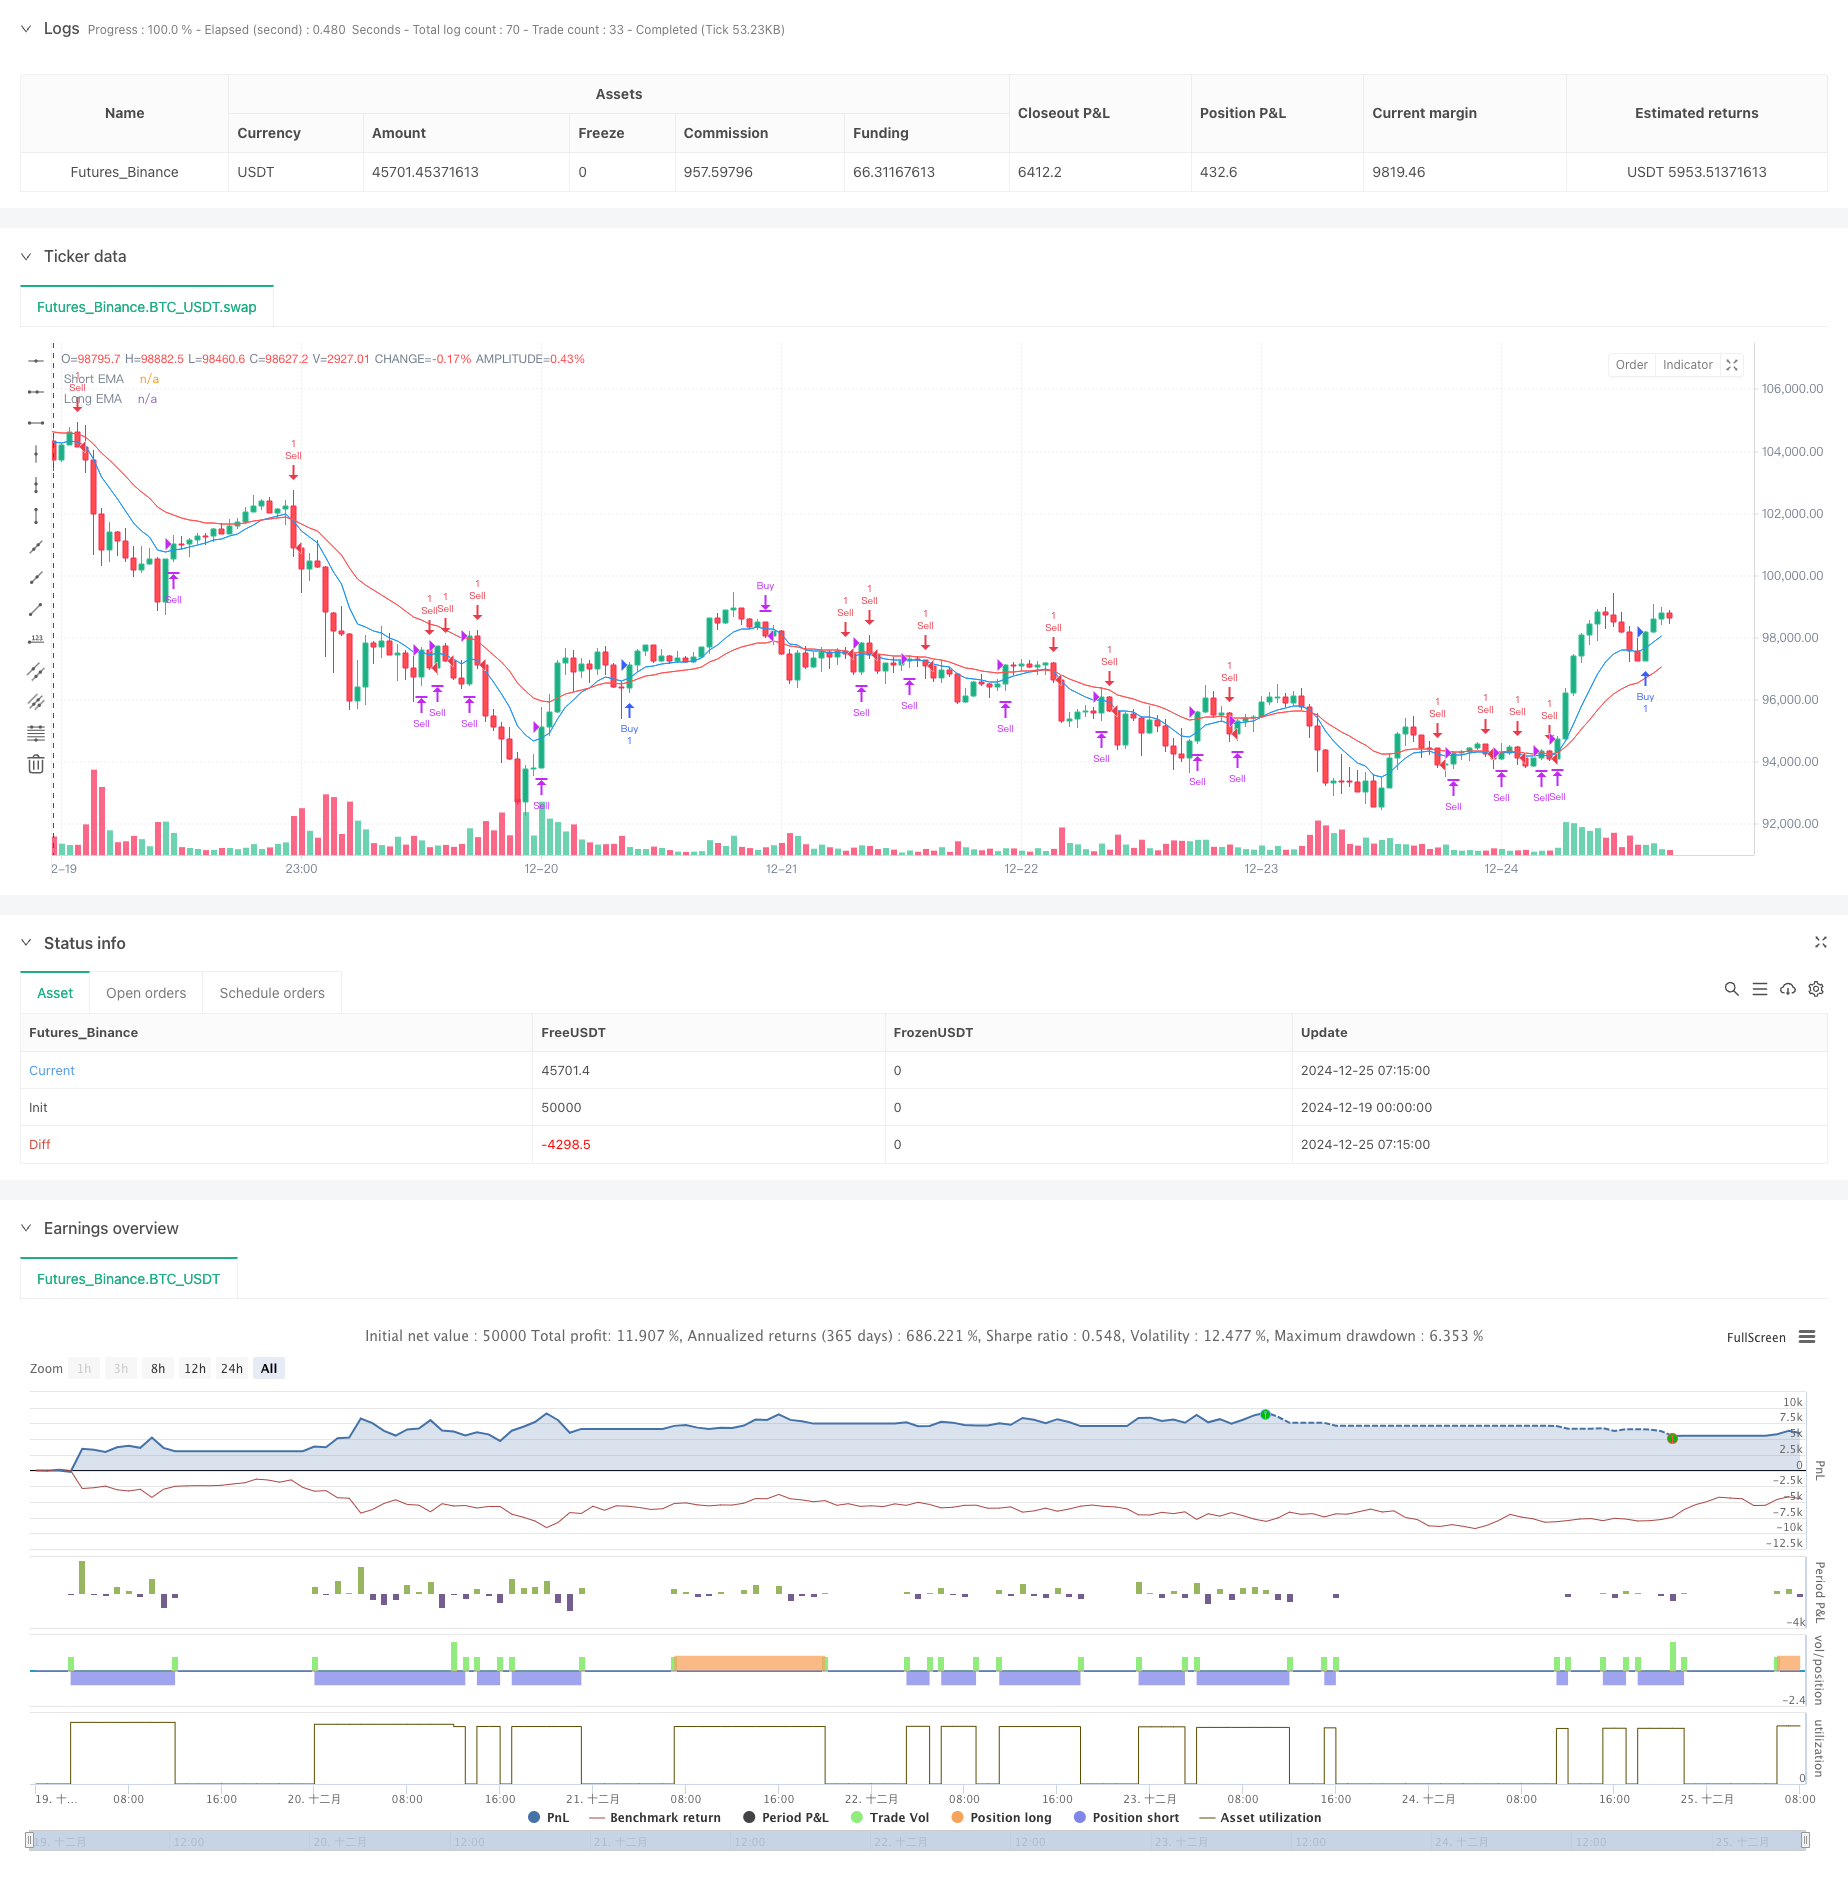
Overview
This is an intelligent trading strategy system based on Exponential Moving Average (EMA). The strategy utilizes crossover signals between short-term and long-term EMAs, combined with price-EMA relationships to identify market trends and trading opportunities. The strategy was developed with AI assistance, achieving automated trading through dynamic price trend analysis.
Strategy Principle
The core logic of the strategy is based on several key components:
- Dual EMA System: Uses 9-period and 21-period exponential moving averages as signal indicators
- Trend Determination: Market trend direction is determined by the position of short-term EMA relative to long-term EMA
- Entry Signals: Long positions are taken when price breaks above short-term EMA in uptrends; short positions when price breaks below short-term EMA in downtrends
- Exit Mechanism: Reverse crossovers between price and short-term EMA serve as stop-loss signals
Strategy Advantages
- Systematic Operation: Fully systematic strategy avoiding emotional interference
- Trend Following: Effectively captures major market trends, increasing profit opportunities
- Risk Control: Clear stop-loss mechanism for timely loss control
- Simple and Reliable: Clear strategy logic, easy to understand and execute
- High Adaptability: Can be adjusted to different market conditions through parameter optimization
Strategy Risks
- Unsuitable for Ranging Markets: May generate frequent false signals during consolidation phases
- Lag Risk: Moving averages have inherent lag, potentially missing optimal entry points
- Parameter Sensitivity: Strategy performance heavily depends on EMA parameter selection
- Market Environment Dependency: Strategy performs better in trending markets
Strategy Optimization Directions
- Add Volume Filters: Incorporate volume confirmation signals to improve trade quality
- Dynamic Parameter Optimization: Automatically adjust EMA parameters based on market volatility
- Include Trend Strength Indicators: Combine with other technical indicators to evaluate trend strength
- Improve Profit-Taking Mechanism: Design more flexible profit-taking mechanisms
- Introduce Volatility Management: Adjust position sizing based on volatility
Summary
This is a well-structured trend-following strategy with clear logic. Through the coordinated use of EMA indicators, it achieves effective market trend capture. The strategy's optimization potential mainly lies in signal filtering and risk management aspects, with continuous improvements potentially enhancing strategy stability and profitability.
Source Pine Script
/*backtest
start: 2024-12-19 00:00:00
end: 2024-12-25 08:00:00
period: 45m
basePeriod: 45m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Jerryorange

//@version=6
strategy("Smart EMA Algo", overlay=true)

// Inputs
emaShortLength = input.int(9, title="Short EMA Length", minval=1)
emaLongLength = input.int(21, title="Long EMA Length", minval=1)
src = input(close, title="Source")

// EMA Calculations
emaShort = ta.ema(src, emaShortLength)
emaLong = ta.ema(src, emaLongLength)

// Market Direction
isUptrend = emaShort > emaLong
isDowntrend = emaShort < emaLong

// Entry Conditions
longCondition = isUptrend and ta.crossover(close, emaShort)
shortCondition = isDowntrend and ta.crossunder(close, emaShort)

// Exit Conditions
exitLong = ta.crossunder(close, emaShort)
exitShort = ta.crossover(close, emaShort)

// Strategy Logic
if (longCondition)
    strategy.entry("Buy", strategy.long)

if (shortCondition)
    strategy.entry("Sell", strategy.short)

if (exitLong)
    strategy.close("Buy")

if (exitShort)
    strategy.close("Sell")

// Plot EMAs
plot(emaShort, color=color.blue, title="Short EMA")
plot(emaLong, color=color.red, title="Long EMA")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Intelligent-Exponential-Moving-Average-Trading-Strategy-Optimization-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Neural Moving Average Crossover Trend Following Strategy with EMA Filtering SystemPine Script · Machine learning · 1h
- Bull Bear Power Trading Strategy with Volume Percentile Based Dynamic Take Profit SystemPine Script · Machine learning · 1d
- Fast and Slow Kurtosis Trading StrategyPine Script · Machine learning · 1d
- Multi indicator Quant Trading StrategyPine Script · Machine learning · 1h
- Multi Dynamic Indicator Combination StrategyPine Script · Machine learning · 2d
- Dual Pressure Quantitative Trading StrategyPine Script · Machine learning · 1h