Strategy vault / Mean reversion
Intelligent Trailing Stop Loss Strategy
The Intelligent Trailing Stop Loss Strategy is a strategy that automatically adjusts the stop loss point based on price changes. It combines the logic of the SAR indicator and adjusts the trailing stop loss line when…
Overview
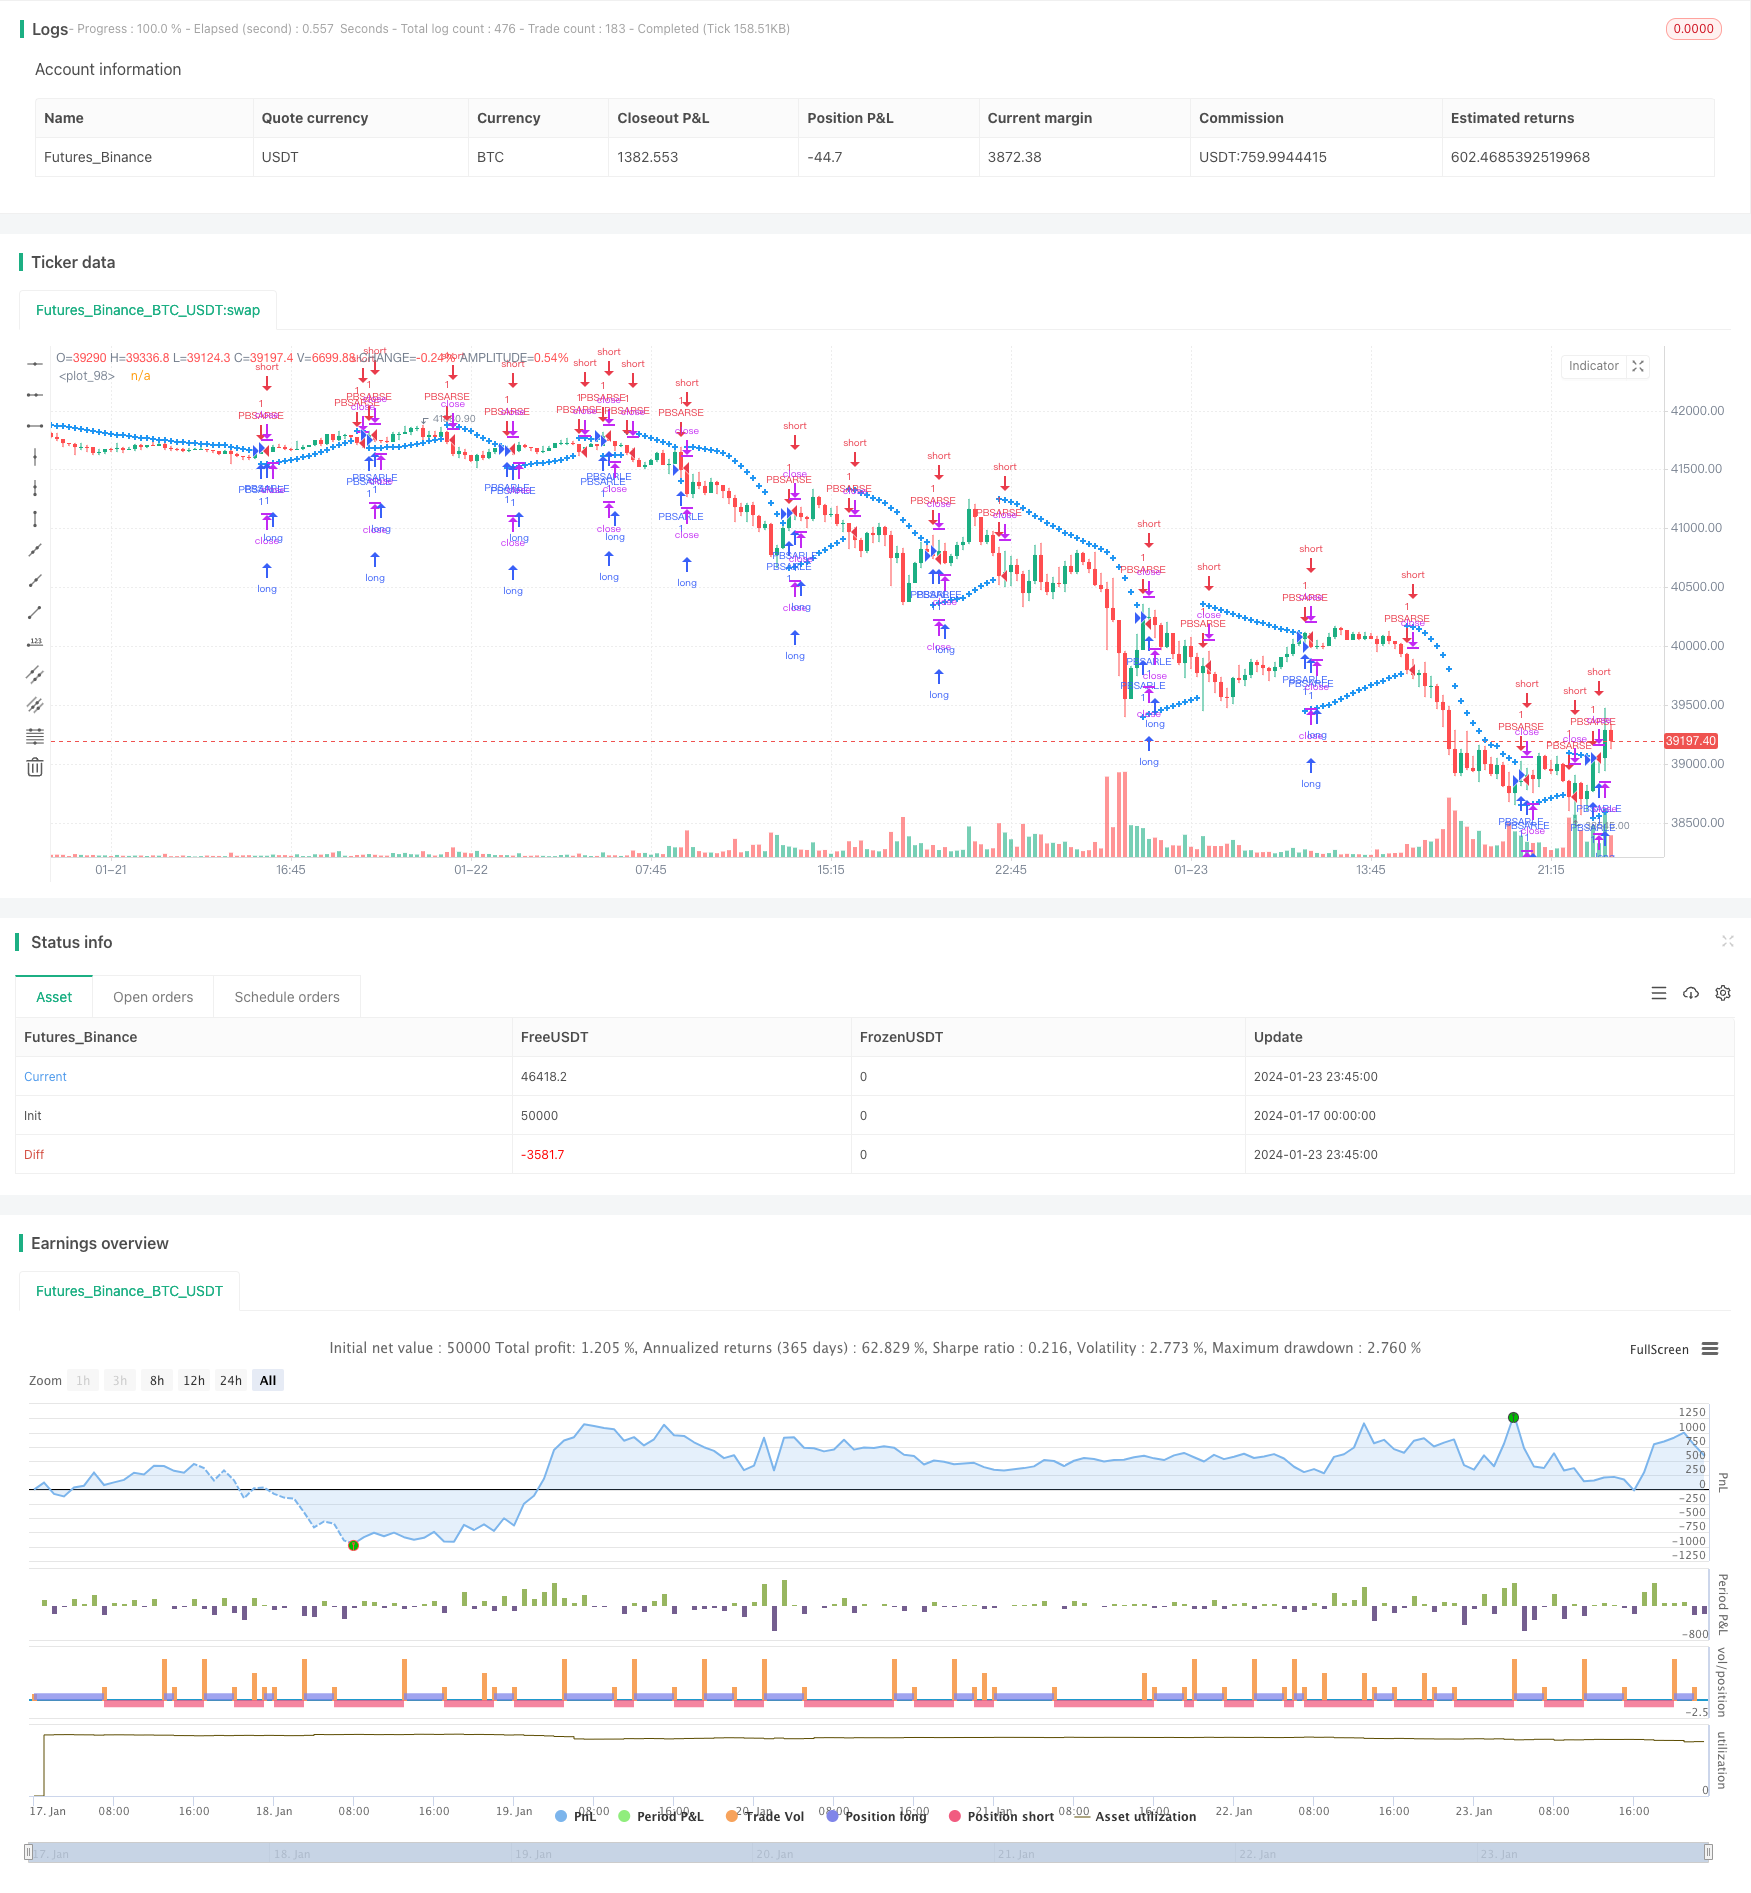
The Intelligent Trailing Stop Loss Strategy is a strategy that automatically adjusts the stop loss point based on price changes. It combines the logic of the SAR indicator and adjusts the trailing stop loss line when the price reaches new high or low points to achieve maximum drawdown control.
Strategy Principle
The core logic of this strategy is to automatically adjust the stop loss line based on the SAR indicator. Specifically, it defines four variables:
- EP: Extreme Point
- SAR: Current Stop Loss Point
- AF: Step Factor, used to control the adjustment magnitude of stop loss line
- Uptrend Flag: To judge if it is currently an uptrend or a downtrend
During an uptrend, the stop loss line will continue to move up to trail the rising price. When the price turns into a downtrend, the stop loss line remains unchanged until the next uptrend.
The adjustment magnitude of the stop loss line is controlled by the Step Factor AF. AF will increase when a new stop loss point is successfully set, thereby expanding the next adjustment magnitude.
Advantages
The biggest advantage of this strategy is that it can intelligently adjust the stop loss point according to market fluctuations, while ensuring sufficient profit space and minimizing the maximum drawdown as much as possible. Compared with the traditional static stop loss method, it can better capture the price trend.
Specifically, there are main advantages:
- Reduce Maximum Drawdown: Intelligent adjustment of stop loss line can exit before trend reversal to maximize protection of realized profit
- Capture Trends: The stop loss line will adjust with new highs or lows and automatically trail price trends
- Customizable Parameters: Users can customize AF step value and initial value based on their own risk preference to control sensitivity of stop loss adjustments
Risk Analysis
There are also some risks to note for this strategy:
- Overly Sensitive: If the AF step adjustment is too large or the initial value is too small, the stop loss line will be too sensitive and may be triggered by short-term market noise
- Missing Opportunities: Triggering stop loss too early may also result in missing profitable opportunities from continued upside
- Parameter Selection: Improper parameter settings will also affect strategy performance and needs adjustment for different markets
Optimization Directions
The strategy can also be optimized in the following aspects:
- Combine With Other Indicators: Pause stop loss line adjustment when major cycle indicators issue signals to avoid premature stop loss before trend reversal
- Add Parameter Self-Adaptive Module: Automatically optimize parameters based on historical data using machine learning algorithms
- Multi-Level Stop Loss: Set up multiple stop loss lines to trail different magnitudes of market fluctuations
Conclusion
The Intelligent Trailing Stop Loss Strategy adjusts stop loss line positions in real-time by simulating the operating logic of the SAR indicator. While protecting profits, it also minimizes the possibility of missing opportunities as much as possible. It maximizes the inherent value of the stop loss function itself.
Compared with traditional fixed stop loss strategies, this strategy can better adapt to market changes and is more flexible. Through custom parameter settings, users can choose stop loss modes suitable for their own risk preferences.
Of course, there are also certain parameter optimization spaces for this strategy, and improved effects that can be achieved by combining other indicators. Overall, it finds a more intelligent balance between stop loss and profit taking for investors.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0.02 | AF_initial |
| v_input_2 | 0.02 | AF_increment |
| v_input_3 | 0.2 | AF_maximum |
Source Pine Script
/*backtest
start: 2024-01-17 00:00:00
end: 2024-01-24 00:00:00
period: 15m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("Lucid SAR Strategy", shorttitle="Lucid SAR Strategy", overlay=true)

// Full credit to Sawcruhteez, Lucid Investment Strategies LLC and Casey Bowman.
// This is a strategy version of the Lucid SAR indicator created by the above-mentioned parties.
// Original version of the indicator: https://www.tradingview.com/script/OkACQQgL-Lucid-SAR/

// Branded under the name "Lucid SAR"
// As agreed to with Lucid Investment Strategies LLC on July 9, 2019
// https://lucidinvestmentstrategies.com/


// Created by Casey Bowman on July 4, 2019

// MIT License

// Copyright (c) 2019 Casey Bowman

// Permission is hereby granted, free of charge, to any person obtaining a copy
// of this software and associated documentation files (the "Software"), to deal
// in the Software without restriction, including without limitation the rights
// to use, copy, modify, merge, publish, distribute, sublicense, and/or sell
// copies of the Software, and to permit persons to whom the Software is
// furnished to do so, subject to the following conditions:

// The above copyright notice and this permission notice shall be included in all
// copies or substantial portions of the Software.

// THE SOFTWARE IS PROVIDED "AS IS", WITHOUT WARRANTY OF ANY KIND, EXPRESS OR
// IMPLIED, INCLUDING BUT NOT LIMITED TO THE WARRANTIES OF MERCHANTABILITY,
// FITNESS FOR A PARTICULAR PURPOSE AND NONINFRINGEMENT. IN NO EVENT SHALL THE
// AUTHORS OR COPYRIGHT HOLDERS BE LIABLE FOR ANY CLAIM, DAMAGES OR OTHER
// LIABILITY, WHETHER IN AN ACTION OF CONTRACT, TORT OR OTHERWISE, ARISING FROM,
// OUT OF OR IN CONNECTION WITH THE SOFTWARE OR THE USE OR OTHER DEALINGS IN THE
// SOFTWARE.


AF_initial = input(0.02)
AF_increment = input(0.02)
AF_maximum = input(0.2)


// start with uptrend
uptrend = true
newtrend = false
EP = high
SAR = low
AF = AF_initial

if not na(uptrend[1]) and not na(newtrend[1])
    if uptrend[1]
        EP := max(high, EP[1])
    else
        EP := min(low, EP[1])
    if newtrend[1]
        AF := AF_initial
    else
        if EP != EP[1]
            AF := min(AF_maximum, AF[1] + AF_increment)
        else
            AF := AF[1]
    SAR := SAR[1] + AF * (EP - SAR[1])
    if uptrend[1]
        if newtrend
            SAR := max(high, EP[1])
            EP := min(low, low[1])
        else
            SAR := min(SAR, low[1])
            if not na(low[2])
                SAR := min(SAR, low[2])
            if SAR > low
                uptrend := false
                newtrend := true
                SAR := max(high, EP[1])
                EP := min(low, low[1])
            else
                uptrend := true
                newtrend := false
    else
        if newtrend
            SAR := min(low, EP[1])
            EP := max(high, high[1])
        else
            SAR := max(SAR, high[1])
            if not na(high[2])
                SAR := max(SAR, high[2])
            if SAR < high
                uptrend := true
                newtrend := true
                SAR := min(low, EP[1])
                EP := max(high, high[1])
            else
                uptrend := false
                newtrend := false


plot(SAR, color = color.blue, style = plot.style_cross, linewidth = 2)

if (uptrend)
    strategy.entry("PBSARLE", strategy.long, comment="PBSARLE")
if (newtrend)
strategy.entry("PBSARSE", strategy.short, comment="PBSARSE")Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Intelligent-Trailing-Stop-Loss-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Rail Parabolic SAR Bollinger Bands StrategyPine Script · Mean reversion
- Dynamic PSAR Stock Fluctuation Tracking StrategyPine Script · Mean reversion · 10m
- Parabolic SAR Divergence Trading StrategyPine Script · Mean reversion · 1d
- Parabolic SAR Trailing Stop Loss StrategyPine Script · Mean reversion · 3h
- Combining Simple Moving Average and Adaptive Moving Average StrategyPine Script · Mean reversion · 5m
- Multi Dimensional Technical Indicator Cross Confirmation Buy Signal Optimization StrategyPine Script · Mean reversion · 1d