Strategy vault / Trend following
Intraday Trading Strategy for Stocks Based on Renko Low Point Retracement
This strategy mainly utilizes the intraday renko low point retracement characteristics of stocks to determine the new trend direction, and thus establishes an intraday trading strategy. When there is an obvious…
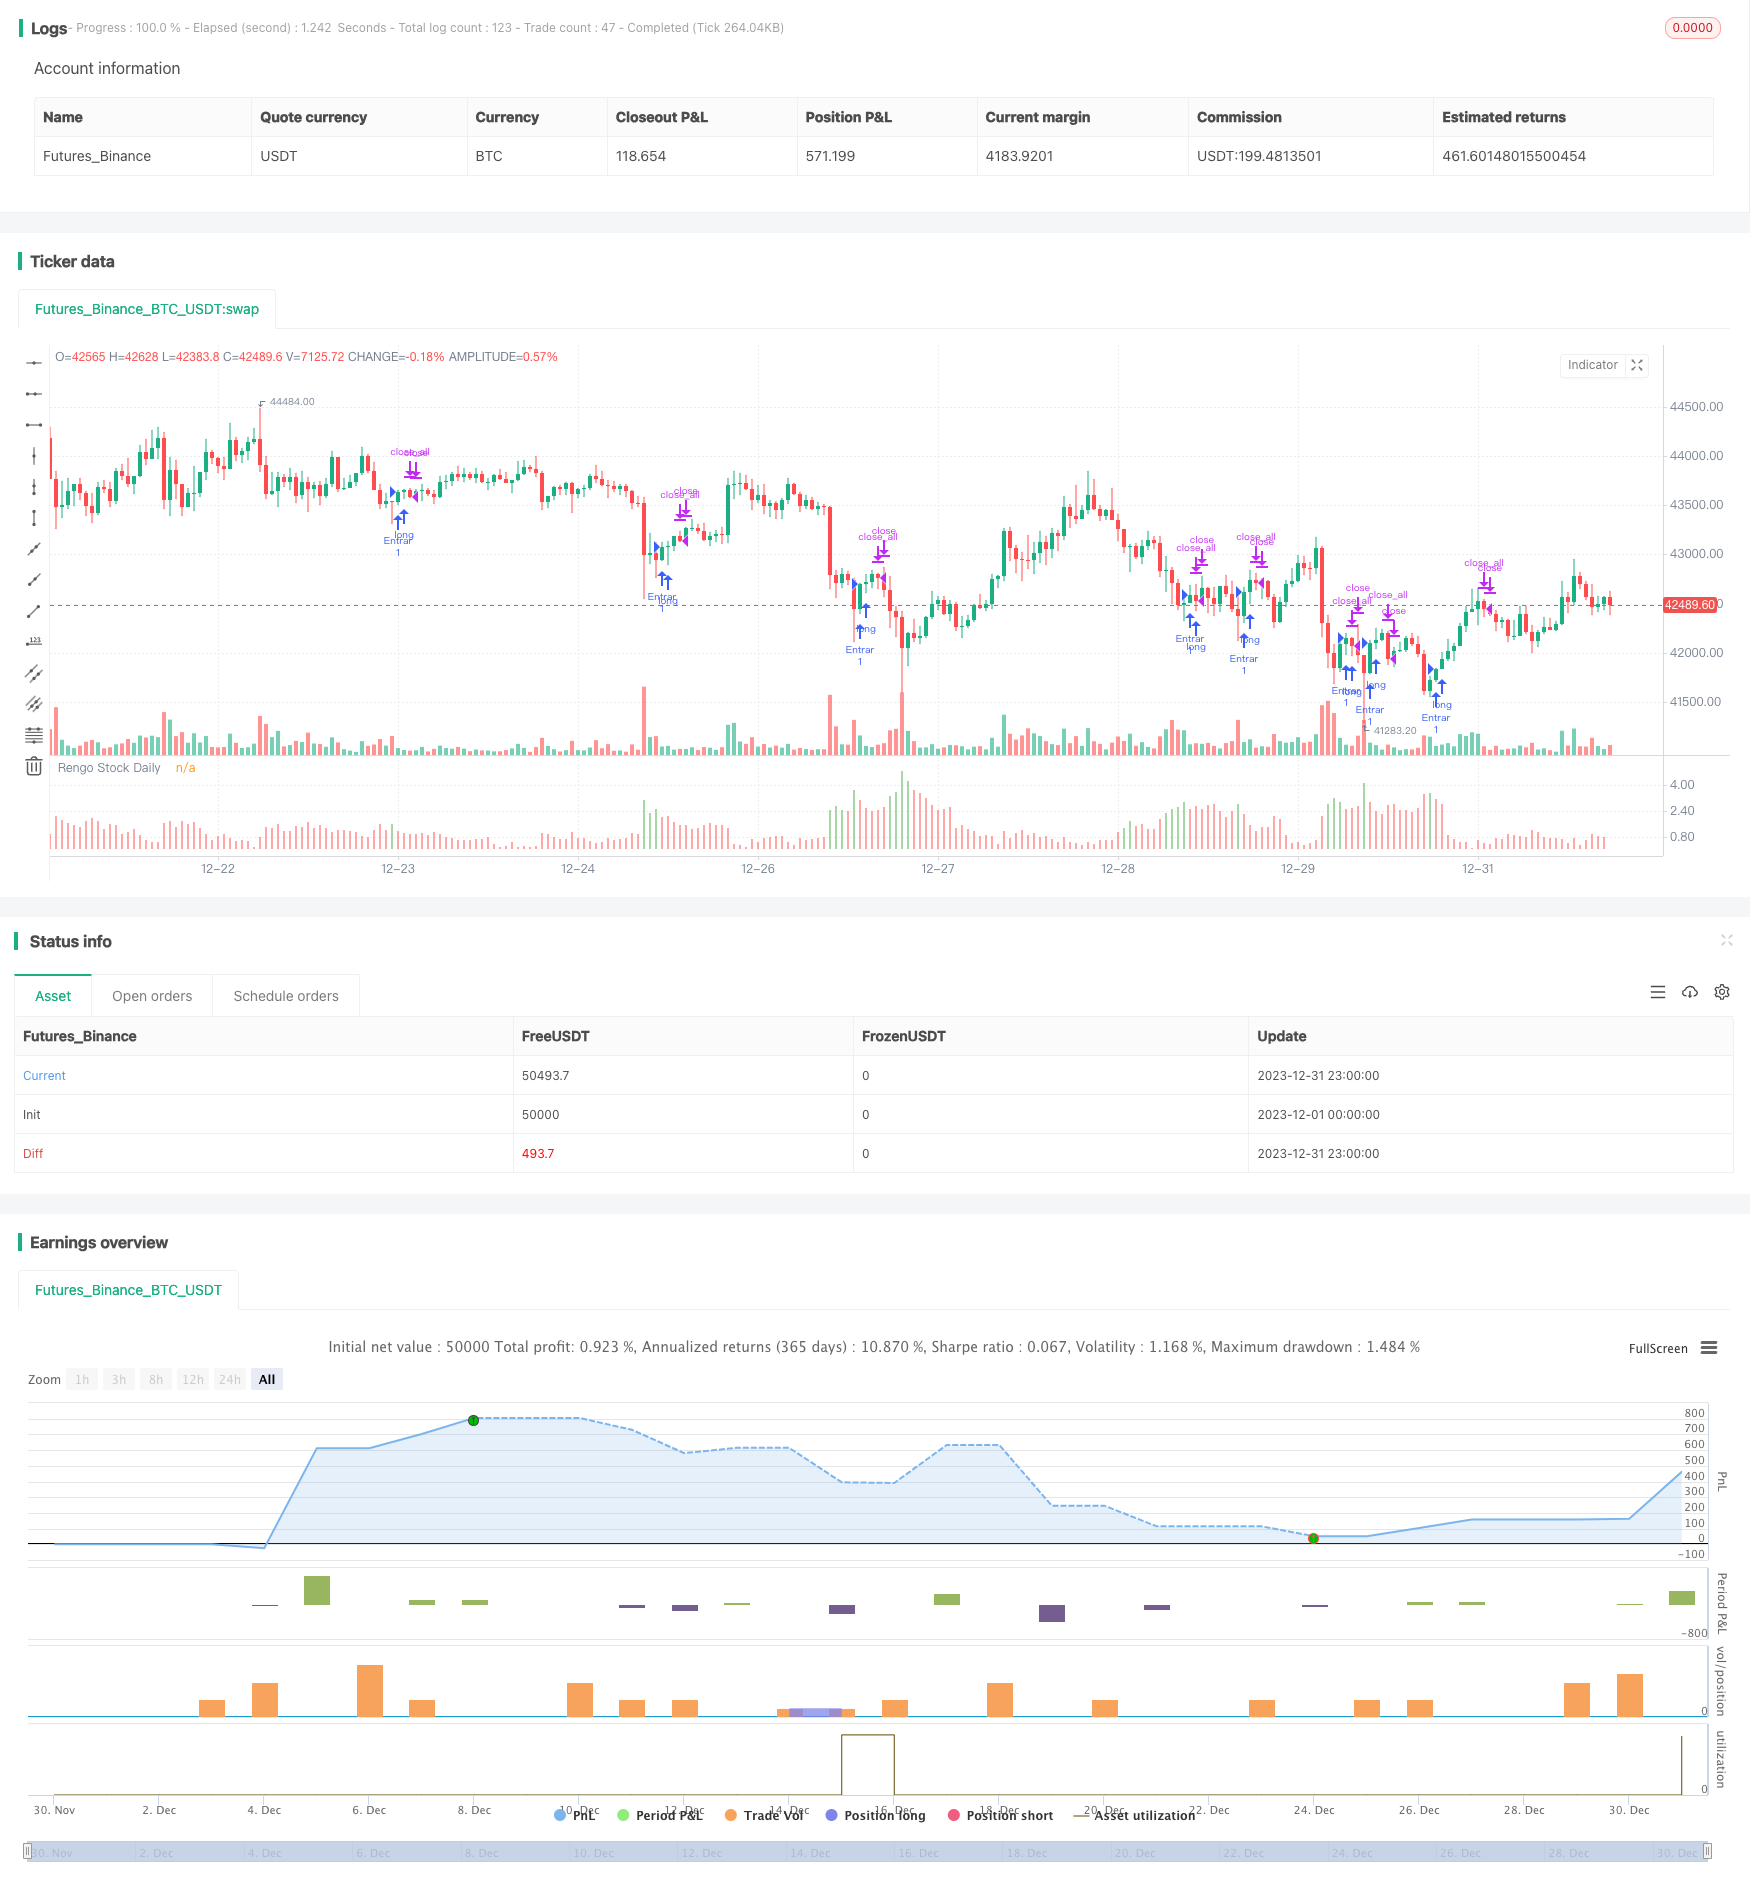
Overview
This strategy mainly utilizes the intraday renko low point retracement characteristics of stocks to determine the new trend direction, and thus establishes an intraday trading strategy. When there is an obvious pullback of the renko intraday low point, it is judged as a new bullish signal and a long position will be taken. When there is a significant decline in the renko closing price, it is regarded as a bearish signal and existing position will be closed.
Strategy Logic
The main criteria of this strategy are: the intraday renko low point retracement exceeds the upper rail and lower rail. The upper rail is calculated as the 20-day average + 2 standard deviations of the renko intraday low point retracement over the past 20 days; The lower rail is calculated as 85% of the highest point of the renko intraday low point retracement over the past 50 days. When the renko intraday low point retracement exceeds the upper rail or lower rail, it is regarded as a buy signal, otherwise the position will be cleared. The specific process is as follows:
- Calculate the standard deviation DesviaccionTipica of the difference between the highest price and the lowest price of the most recent 22 renko bars over the past 20 days
- Calculate the 20-day moving average Media of the difference between the highest price and the lowest price of the most recent 22 renko bars
- Upper rail Rango11 = Media + DesviaccionTipica * 2
- Lower rail Rango22 = highest point of the most recent 50 renko bars * 0.85
- When today's renko satisfies low/highest(low,22)>Rango11 or Rango22, go long; when today's renko satisfies close<open, close position
The above is the main judgment rules and trading logic of this strategy.
Advantage Analysis
- Utilizing the noise filtering capability of renko, renko is used as an assistant judgment to effectively filter out false signals in range-bound markets
- Judging the trend based on renko intraday low point retracement features avoids the misjudgment caused by using a single moving average
- The double rail judgment rules can determine the trend direction more accurately
- The strategy judgment rules are simple and easy to understand and implement
- The strategy is easy to parameter tuning and optimization, which can significantly improve strategy performance
Risk Analysis
- The repainting characteristics of renko may have some impact on actual trading
- Improper settings of double rail distances may miss or misjudge signals
- The strategy uses a single indicator for judgment, which may miss important signals provided by other indicators
- No stop loss setting may lead to greater losses
Risk Mitigations:
- Properly relax double rail parameters to ensure more signals are captured
- Incorporate judgments of more indicators such as moving averages and energy indicators to ensure accurate judgments
- Add moving stop loss to control risks
Optimization Directions
- Parameter Tuning, optimize double rail parameter settings
- Incorporate judgments of more technical indicators
- Add stop loss mechanism
- Expand trading varieties to increase trading opportunities
Summary
The overall idea of this strategy is clear and easy to implement. It utilizes the renko intraday low point retracement to determine the new trend direction. The advantages of this strategy are that it uses renko characteristics for filtration to avoid misjudgment, and adopts double rail judgment to improve accuracy. At the same time, there are also some rooms for improvement of this strategy. The keys are parameter optimization, stop loss setting, and integration of multiple indicator judgments. In general, this is an easy to understand and effective intraday trading strategy for stocks.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | false | Rango 1 |
| v_input_2 | false | Rango 2 |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// @version=2
strategy("Renko Stock Daily")


Rango1 = input(false, title="Rango 1")
Rango2 = input(false, title="Rango 2")

Situacion = ((highest(close, 22)-low)/(highest(close, 22)))*100

DesviaccionTipica = 2 * stdev(Situacion, 20)
Media = sma(Situacion, 20)

Rango11 = Media + DesviaccionTipica

Rango22 = (highest(Situacion, 50)) * 0.85


advertir = Situacion >= Rango11 or Situacion >= Rango22 ? green : red


if (Situacion[1] >= Rango11[1] or Situacion[1] >= Rango22[1]) and (Situacion[0] < Rango11[0] and Situacion[0] < Rango22[0])and (close>open)
    strategy.entry("Entrar", strategy.long,comment= "Entrar",when=strategy.position_size <= 0)


strategy.close_all(when=close<open)


plot(Rango1 and Rango22 ? Rango22 : na, title="Rango22", style=line, linewidth=4, color=orange)
plot(Situacion, title="Rengo Stock Daily", style=histogram, linewidth = 4, color=advertir)
plot(Rango2 and Rango11 ? Rango11 : na, title="Upper Band", style=line, linewidth = 3, color=aqua)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-31. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Intraday-Trading-Strategy-for-Stocks-Based-on-Renko-Low-Point-Retracement.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m