Jupiter and Saturn Momentum MA Crossover Filtered Strategy
This strategy uses moving average crossovers as trading signals, combined with volatility indicator BB and a custom momentum indicator for filtration, aiming to improve the reliability of MA crossover signals and…
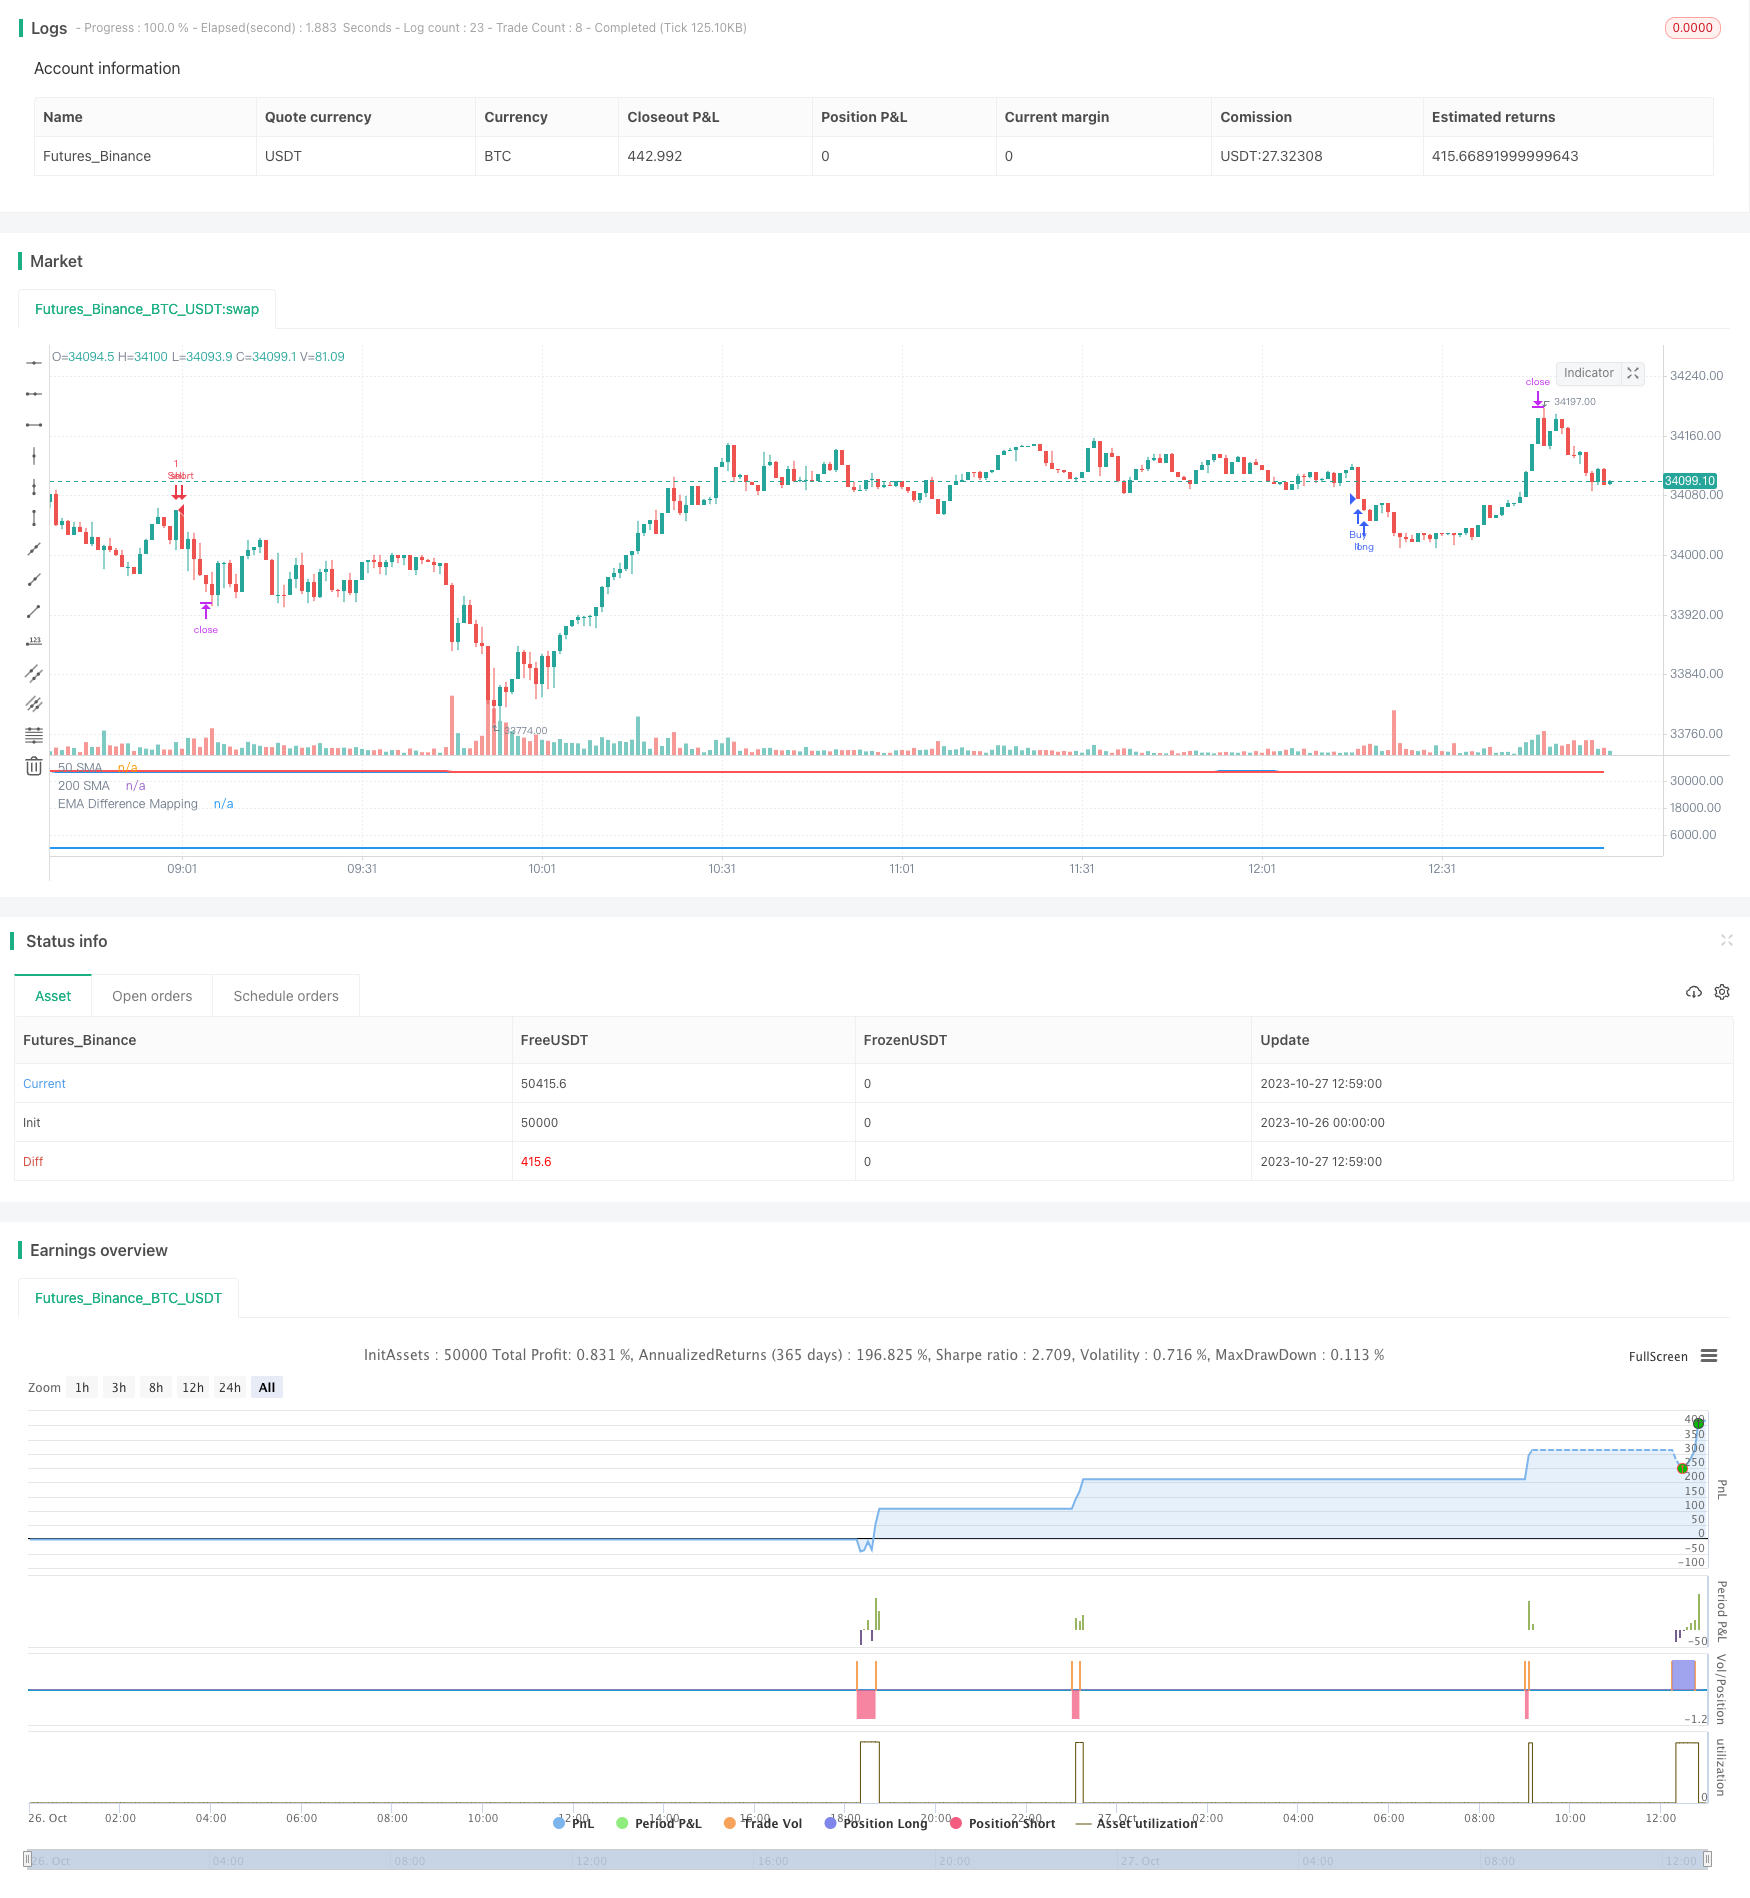
Overview
This strategy uses moving average crossovers as trading signals, combined with volatility indicator BB and a custom momentum indicator for filtration, aiming to improve the reliability of MA crossover signals and reduce false signals.
Principles
Use 50-period EMA and 200-period SMA to form golden cross and death cross signals.
When price is in an uptrend, require price to be above 200-day line and custom momentum indicator value below 25 to generate buy signals.
When price is in a downtrend, require price to be below 200-day line and custom momentum indicator value above 75 to generate sell signals.
Custom momentum indicator maps BB midline and band distance into 0-100 range based on historical maximums and minimums.
Momentum indicator reflects relative price volatility, threshold filtering helps reduce false crossovers.
Advantages
Utilize strengths of EMA and SMA to capture medium-long term trends.
Increased filtration with momentum indicator improves reliability and reduces false signals.
BB band distance reflects volatility intensity, historical normalization avoids parameter dependency.
Customizable EMA, SMA periods and momentum threshold adaptable to varying market environments.
Simple logic with optimization flexibility, strong practicality.
Risk Analysis
EMA and SMA have lagging effect, may miss short-term opportunities.
Trend following nature unsuitable for range-bound markets.
Momentum threshold requires iterative backtesting for optimal parameter, risks overfitting.
Longer-term systems offer steady but potentially limited absolute returns.
Can shorten MA periods or add complementary indicators to improve adaptability.
Enhancement Opportunities
Test different MA combinations for optimal parameters.
Add complementary indicators like MACD, KD for additional validation.
Optimize momentum indicator parameters like lookback period, mapping range.
Incorporate stop loss to control risks.
Adjust for symbol-specific parameters using machine learning feature extraction.
Add volume indicators to avoid unreasonable crossover signals.
Conclusion
This strategy combines the strengths of long-term trend following and dual momentum threshold filtering for high reliability and practical value. Further improvements are possible through parameter optimization and complementary techniques. The innovative concept provides valuable insights for other trend systems. A valuable addition to the algorithmic trading strategy library.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 20 | EMA Length |
| v_input_2 | 2 | Standard Deviation Length |
| v_input_3 | 1000 | Take Profit (in Points) |
| v_input_4 | 2500 | Stop Loss (in Points) |
Source Pine Script
/*backtest
start: 2023-10-26 00:00:00
end: 2023-10-27 13:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="EMA Difference Mapping with Trades", shorttitle="EMA Diff Map", overlay=false)

// Inputs
emaLength = input(20, "EMA Length")
stdDevLength = input(2, "Standard Deviation Length")
priceSource = close
takeProfitPoints = input(1000, title="Take Profit (in Points)")
stopLossPoints = input(2500, title="Stop Loss (in Points)")

// Calculate EMA
ema = ema(priceSource, emaLength)

// Calculate Standard Deviation
stdDev = stdev(priceSource, stdDevLength)

// Calculate differences
diff1 = (ema + stdDev) - ema
diff2 = ema - (ema - stdDev)

// Calculate min and max differences from last year
lookbackPeriod = 504 // Number of trading days in a year
minDiff1 = lowest(diff1, lookbackPeriod)
maxDiff1 = highest(diff1, lookbackPeriod)
minDiff2 = lowest(diff2, lookbackPeriod)
maxDiff2 = highest(diff2, lookbackPeriod)

// Map differences based on requirements
mappedDiff1 = 50 + 50 * ((diff1 - minDiff1) / (maxDiff1 - minDiff1))
mappedDiff2 = 50 - 50 * ((diff2 - minDiff2) / (maxDiff2 - minDiff2))

// Combine mapped differences into a single line
mappedLine = if close > ema
    mappedDiff1
else
    mappedDiff2

// Plot 'mappedLine' in the main chart area conditionally
plot(mappedLine, title="EMA Difference Mapping", color=(close > ema ? color.blue : na), style=plot.style_line, linewidth=2)

// Calculate the 50EMA and 200SMA
ema50 = ema(close, 50)
sma200 = sma(close, 200)

// Plot the 50EMA and 200SMA on the main chart
plot(ema50, color=color.blue, title="50 SMA", linewidth=2)
plot(sma200, color=color.red, title="200 SMA", linewidth=2)

// Initialize trade variables
var bool waitingForBuy = na
var bool waitingForSell = na
var bool buyConditionMet = false
var bool sellConditionMet = false

if not sellConditionMet and crossunder(ema50, sma200)
    sellConditionMet := true
    waitingForBuy := false

if sellConditionMet
    waitingForSell := true
    sellConditionMet := false

if waitingForSell and close < sma200 and mappedLine > 75
    strategy.entry("Sell", strategy.short)
    strategy.exit("Sell Exit", "Sell", profit=takeProfitPoints, loss=stopLossPoints)
    waitingForSell := false

// Define the strategy conditions and execute trades
if not buyConditionMet  and crossover(ema50, sma200)
    buyConditionMet := true
    waitingForSell := false

if buyConditionMet
    waitingForBuy := true
    buyConditionMet := false

if waitingForBuy and close > sma200 and mappedLine < 25
    strategy.entry("Buy", strategy.long)
    strategy.exit("Buy Exit", "Buy", profit=takeProfitPoints, loss=stopLossPoints)
    waitingForBuy := false
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-03. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Jupiter-and-Saturn-Momentum-MA-Crossover-Filtered-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- MACD Momentum Indicator Backtest StrategyPine Script · Momentum · 1h
- MACD of Relative Strength StrategyPine Script · Momentum · 1d
- MoonFlag MACD Momentum StochRSI Trading StrategyPine Script · Momentum · 1d
- Multi Indicator Trend Momentum Trading Strategy with Dynamic Risk Management SystemPine Script · Momentum · 1h
- Multi Level Technical Indicator Momentum Trading Strategy Based on Enhanced MACD Volume Strength and EMA Signal SystemPine Script · Momentum · 1h