Keltner Channel Tracking Strategy
This strategy is designed based on the Keltner Channel indicator to generate trading signals when price breaks through the upper and lower bands of the channel. The strategy only goes long, if a sell signal appears…
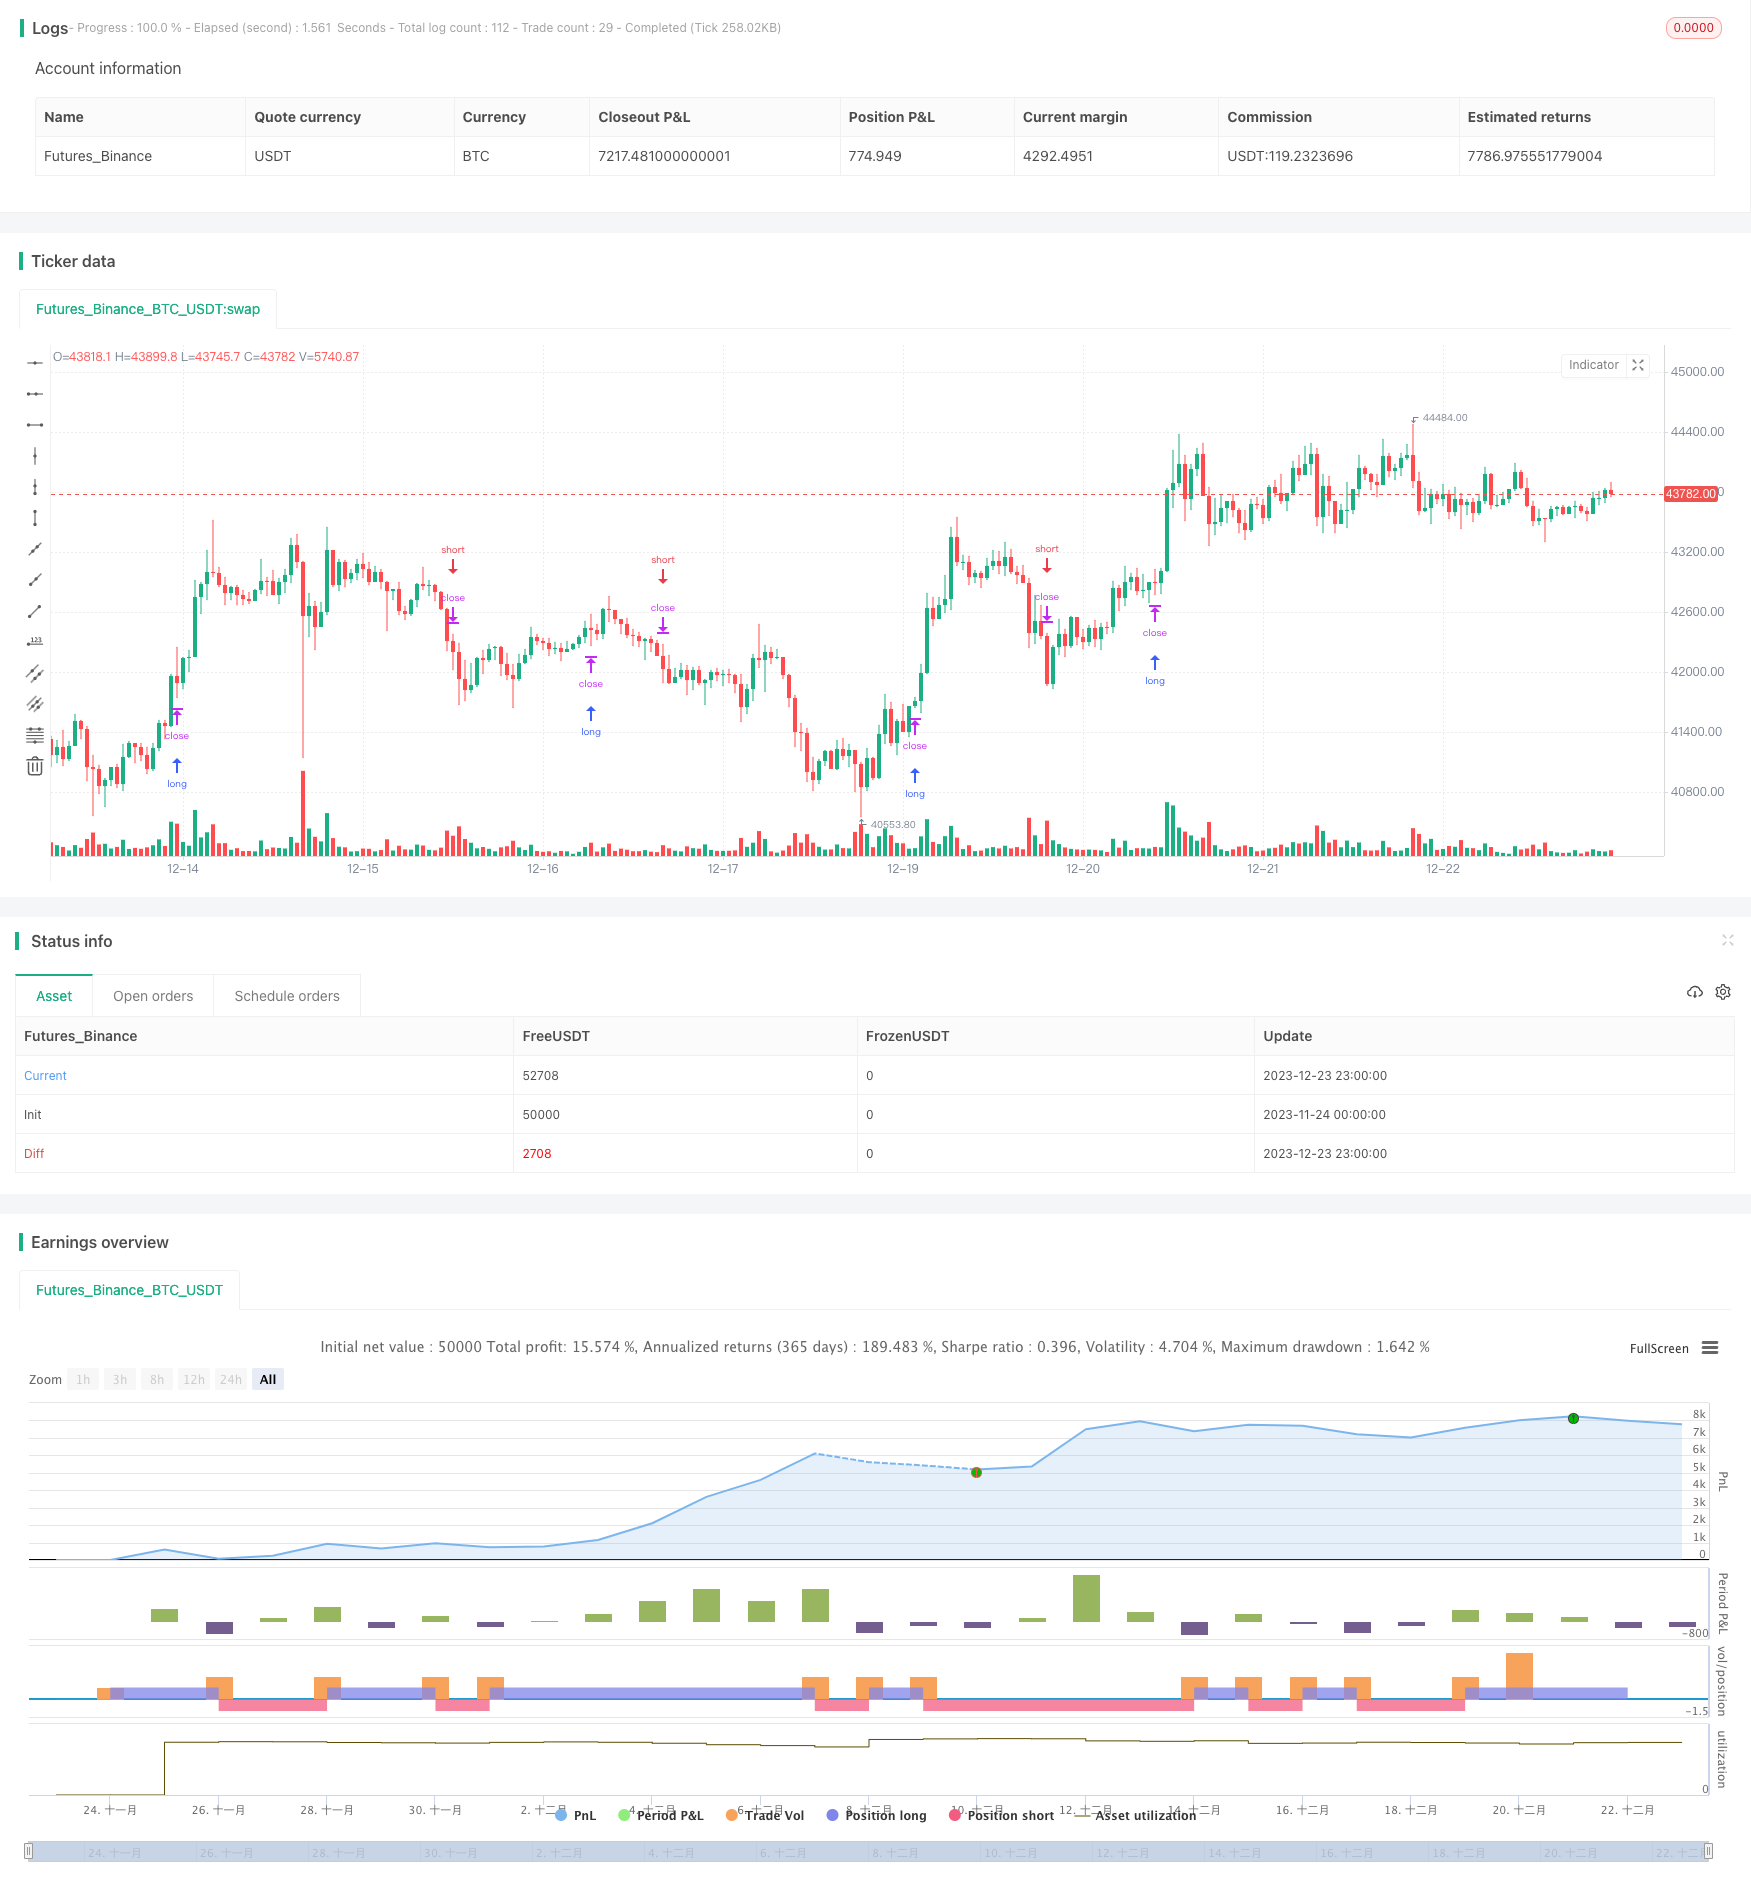
Overview
This strategy is designed based on the Keltner Channel indicator to generate trading signals when price breaks through the upper and lower bands of the channel. The strategy only goes long, if a sell signal appears, it will flatten the position to neutral.
Strategy Logic
The strategy uses SMA and ATR to build the Keltner Channel. The upper and lower bands are calculated as:
Upper Band = SMA + ATR * Multiplier Lower Band = SMA - ATR * Multiplier
When price breaks above the upper band, a buy signal is generated. When price breaks below the lower band, a sell signal is generated.
Since it only goes long, if a sell signal appears, it will cancel previous orders and flatten the position.
The logic is:
- Build Keltner Channel with SMA and ATR
- When price breaks above upper band, set entry price and go long
- When price breaks below lower band, flatten previous long position
Advantage Analysis
The advantages of this strategy:
- Simple and clear logic, easy to understand and implement
- Keltner Channel is intuitive for trend identification
- Only go long avoids chasing stop loss risk
- Conditional orders for precision entries
Risk Analysis
There are also some risks:
- Frequent open/close trades during market fluctuation
- Unable to take advantage of short opportunities
- Lack of exit mechanism, need manual intervention
Solutions:
- Optimize channel parameters to reduce false signals
- Add short module for two-way trading
- Add exit mechanisms like moving stop loss, trailing stop
Optimization Directions
The strategy can be optimized in the following aspects:
- Optimize parameters like channel period, ATR multiplier etc
- Add short module based on lower band breakout
- Incorporate stop loss mechanisms like ATR trailing stop
- Consider more filters to avoid false signals
- Test effectiveness across different products
Conclusion
This strategy effectively catches market trends with simple Keltner Channel rules. The logic is clear and easy to understand. Although the lack of exits and short module, it has great potential for improvements like parameter tuning, adding stops, going short etc. Overall a valuable quant strategy worth in-depth research and application.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | useTrueRange |
| v_input_2 | 20 | length |
| v_input_3 | true | mult |
Source Pine Script
/*backtest
start: 2023-11-24 00:00:00
end: 2023-12-24 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("Keltner Channel Strategy", overlay=true)
source = close

useTrueRange = input(true)
length = input(20, minval=1)
mult = input(1.0)

ma = sma(source, length)
range = useTrueRange ? tr : high - low
rangema = sma(range, length)
upper = ma + rangema * mult
lower = ma - rangema * mult

crossUpper = crossover(source, upper)
crossLower = crossunder(source, lower)

bprice = 0.0
bprice := crossUpper ? high+syminfo.mintick : nz(bprice[1])

sprice = 0.0
sprice := crossLower ? low -syminfo.mintick : nz(sprice[1])

crossBcond = false
crossBcond := crossUpper ? true
 : na(crossBcond[1]) ? false : crossBcond[1]

crossScond = false
crossScond := crossLower ? true
 : na(crossScond[1]) ? false : crossScond[1]

cancelBcond = crossBcond and (source < ma or high >= bprice )
cancelScond = crossScond and (source > ma or low <= sprice )

if (cancelBcond)
    strategy.cancel("KltChLE")

if (crossUpper)
    strategy.entry("KltChLE", strategy.long, stop=bprice, comment="KltChLE")

if (cancelScond)
    strategy.cancel("KltChSE")

if (crossLower)
    strategy.entry("KltChSE", strategy.short, stop=sprice, comment="KltChSE")

//plot(strategy.equity, title="equity", color=red, linewidth=2, style=areabr)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Keltner-Channel-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h
- Flexible Long Short Trading Strategy Based on Keltner ChannelsPine Script · Breakout · 1d
- Quantitative Trading Price Breakthrough StrategyPine Script · Breakout · 1d
- Integrated Ichimoku Keltner Trading System Based on Moving Average StrategyPine Script · Breakout · 1h
- Keltner Channel Pullback StrategyPine Script · Breakout · 1h
- Multi Technical Indicator Trend Following Channel Breakout Trading Strategy with Candlestick Pattern Filtering SystemPine Script · Breakout · 1h