KST EMA Momentum Trend Following Strategy
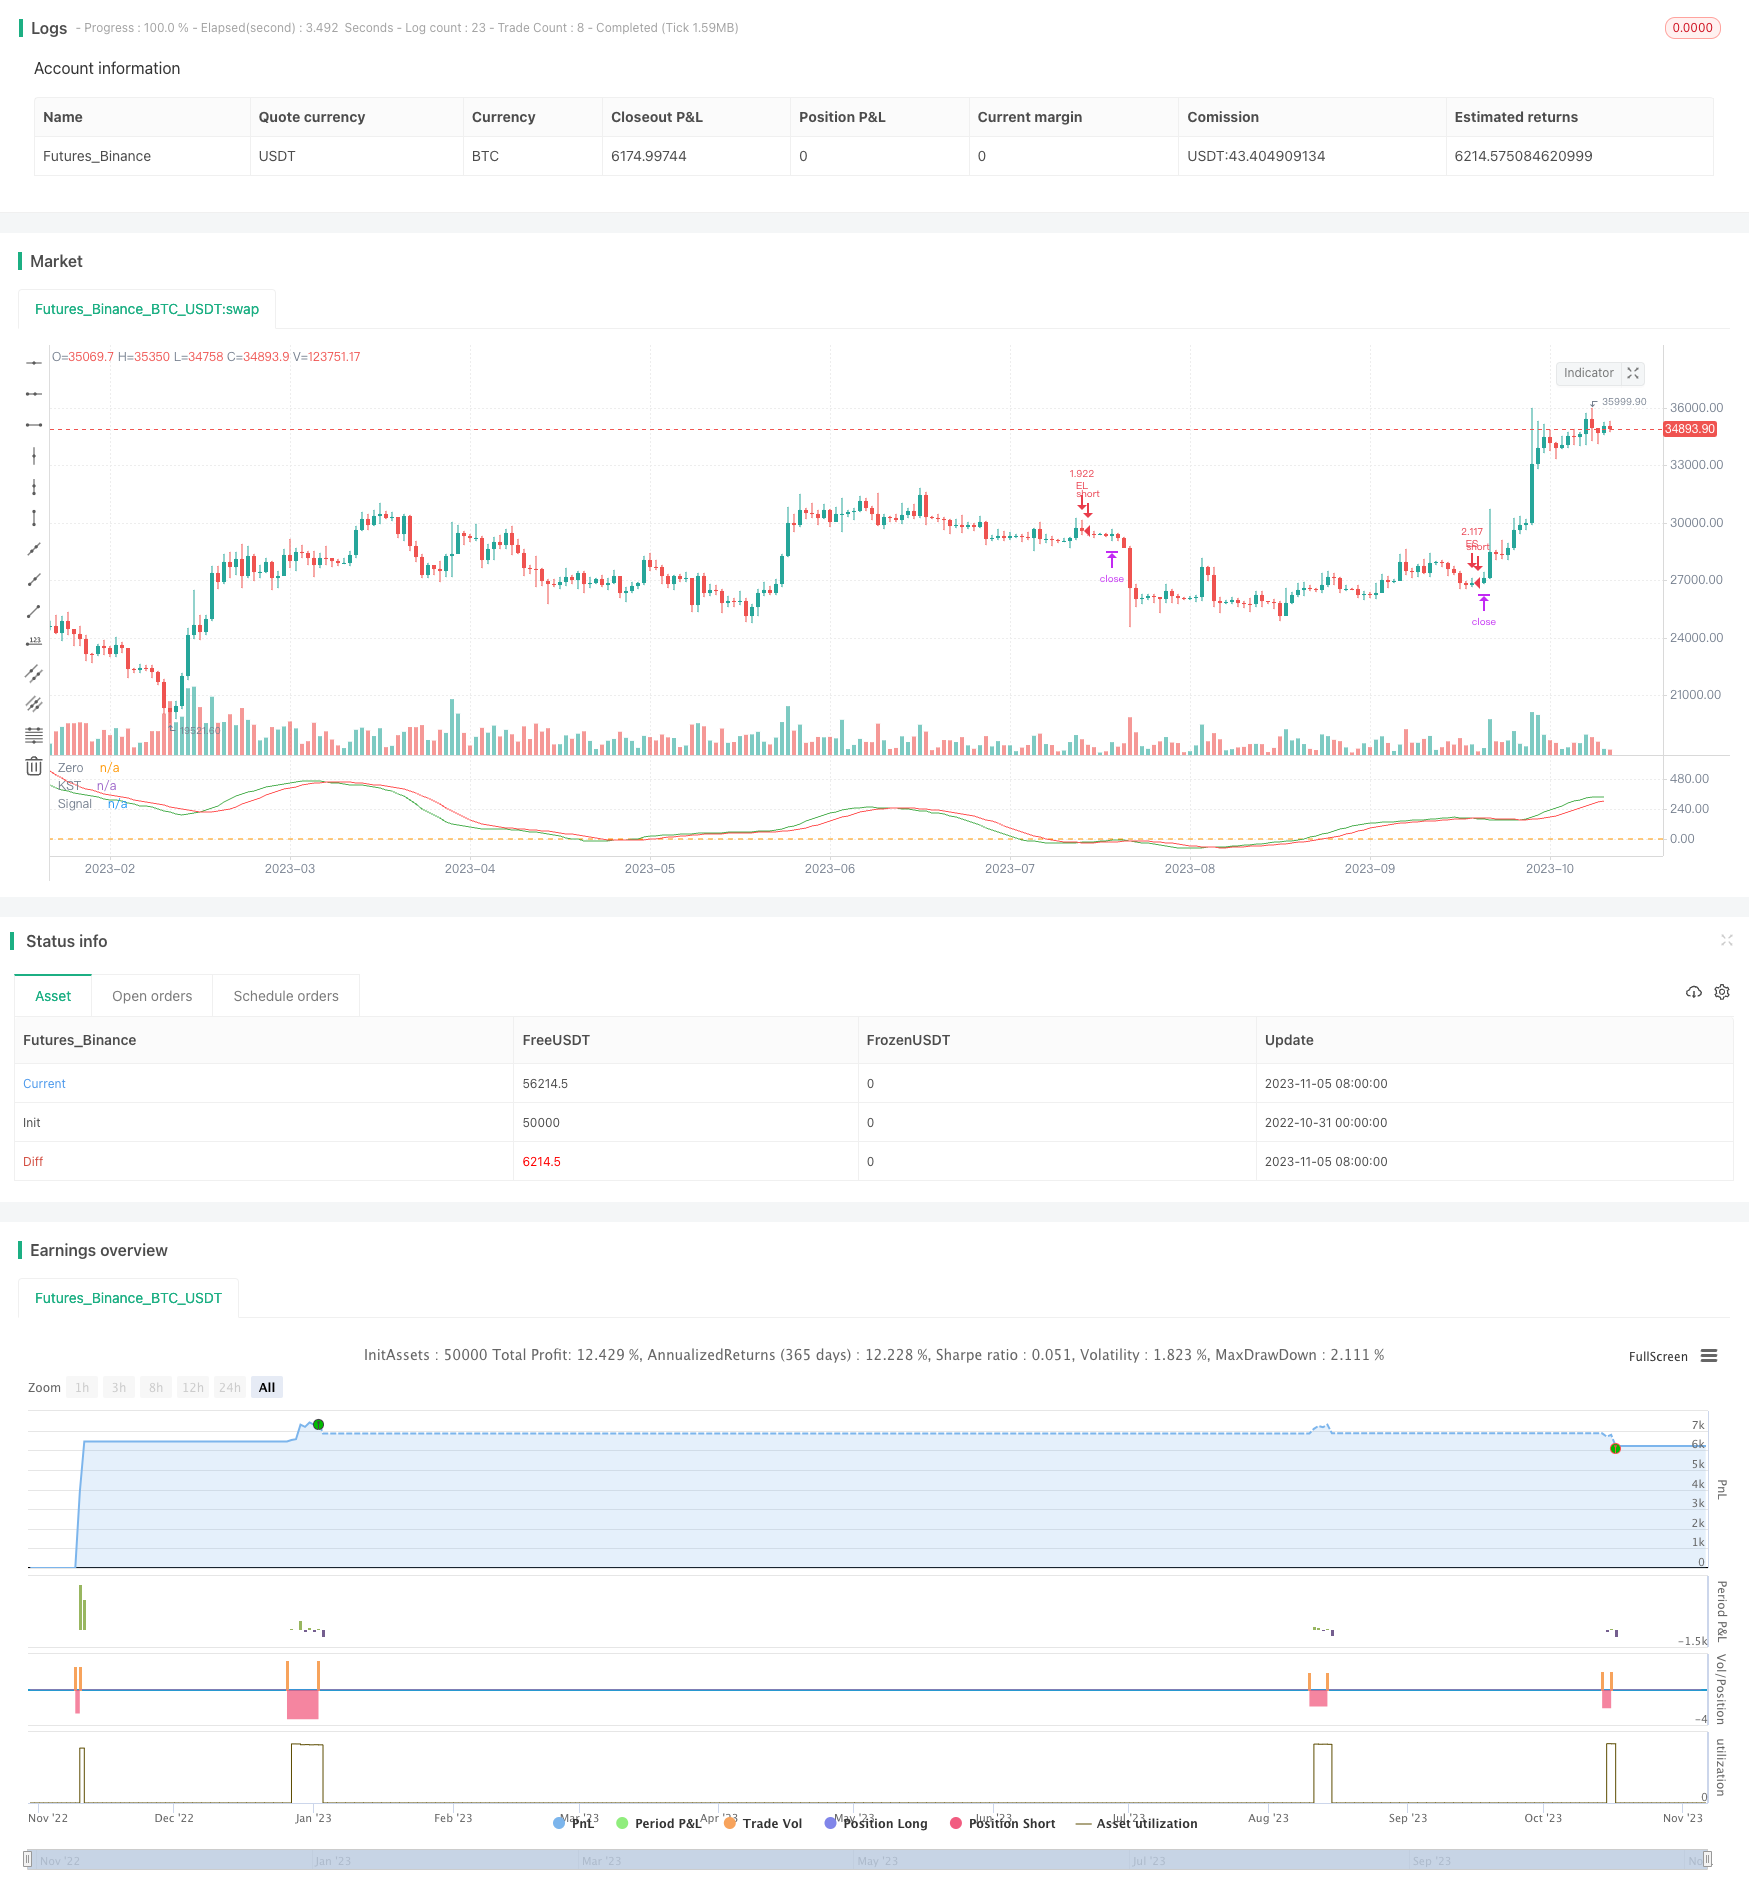
The core idea of this strategy is to combine the KST indicator and EMA lines to identify and follow trends. It generates buy signals when the KST indicator crosses above 0 and closes above the EMA line, and sell…
Overview
The core idea of this strategy is to combine the KST indicator and EMA lines to identify and follow trends. It generates buy signals when the KST indicator crosses above 0 and closes above the EMA line, and sell signals when it crosses below 0 and closes below the EMA line. This simple and practical strategy can automatically track trends and is suitable for medium to long term holdings.
Strategy Logic
Calculate the KST indicator: Compute the ROC of 10, 15, 20 and 30 periods, take a weighted sum, and smooth it with a 9-period SMA to derive the KST indicator.
Calculate the EMA line: Compute a 50-period EMA line.
Generate buy signal: When the fast KST line crosses above the slow KST line (golden cross) and is below 0, while the close is above the EMA line, a buy signal is triggered.
Generate sell signal: When the fast KST line crosses below the slow KST line (dead cross) and is above 0, while the close is below the EMA line, a sell signal is triggered.
Set trailing stop loss: The stop loss tracks 1% of account value to realize automatic stop loss.
Advantages
KST identifies trend changes, EMA confirms direction. Combining both accurately detects entry timing.
Using fast/slow crossovers and 0-line avoids unnecessary trades.
EMA as support/resistance further filters fake signals. Only enter on EMA breakouts.
Auto trailing stop loss controls risk and allows profits to run.
Simple parameters make implementation and optimization easy.
Risks
KST has lag in detecting trend changes, may miss some chances. Can shorten periods or optimize weighting.
EMA has lag around trend reversals. Other indicators or MA combos may work better.
Stop loss too wide increases losses, too tight gets stopped out by spikes. Careful testing needed to optimize.
Frequent signals may increase transaction costs. Can tighten entry rules to reduce trades.
Optimization Directions
Optimize KST periods for sensitivity to specific instruments.
Test other moving averages like MA, WMA to see which combines best with KST.
Experiment dynamic stops based on volatility metrics like ATR.
Add filters like volume spikes to avoid traps.
Consider combining with indicators like RSI, MACD for more dimensions.
Test parameters across instruments to optimize for each.
Conclusion
This strategy has clear, reliable logic that is easy to implement. KST identifies trend turns, EMA filters further, and stops control risk. It automatically tracks medium to long term trends. Reasonable parameters provide large optimization space. Users can tweak for different instruments. Applicable for beginners to learn and professionals to build on. With further optimization it shows promise as a robust trend following system.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | ROC Length #1 |
| v_input_2 | 15 | ROC Length #2 |
| v_input_3 | 20 | ROC Length #3 |
| v_input_4 | 30 | ROC Length #4 |
| v_input_5 | 10 | SMA Length #1 |
| v_input_6 | 10 | SMA Length #2 |
| v_input_7 | 10 | SMA Length #3 |
| v_input_8 | 15 | SMA Length #4 |
| v_input_9 | 9 | Signal Line Length |
| v_input_10 | 50 | Length EMA |
| v_input_11_close | 0 | Source EMA: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_12 | false | Offset |
| v_input_13 | true | Trail Long Loss (%) |
| v_input_14 | true | Trail Short Loss (%) |
Source Pine Script
/*backtest
start: 2022-10-31 00:00:00
end: 2023-11-06 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="Know Sure Thing and EMA Strategy by JLX", shorttitle="KST EMA JLX", format=format.price, precision=4, initial_capital = 1000, default_qty_type=strategy.percent_of_equity, default_qty_value = 100)
roclen1 = input(10, minval=1, title = "ROC Length #1")
roclen2 = input(15, minval=1, title = "ROC Length #2")
roclen3 = input(20, minval=1, title = "ROC Length #3")
roclen4 = input(30, minval=1, title = "ROC Length #4")
smalen1 = input(10, minval=1, title = "SMA Length #1")
smalen2 = input(10, minval=1, title = "SMA Length #2")
smalen3 = input(10, minval=1, title = "SMA Length #3")
smalen4 = input(15, minval=1, title = "SMA Length #4")
siglen = input(9, minval=1, title = "Signal Line Length")
smaroc(roclen, smalen) => sma(roc(close, roclen), smalen)
kst = smaroc(roclen1, smalen1) + 2 * smaroc(roclen2, smalen2) + 3 * smaroc(roclen3, smalen3) + 4 * smaroc(roclen4, smalen4)
sig = sma(kst, siglen)
plot(kst, color=color.green, title="KST")
plot(sig, color=color.red, title="Signal")
hline(0, title="Zero")

len = input(50, minval=1, title="Length EMA")
src = input(close, title="Source EMA")
offset = input(title="Offset", type=input.integer, defval=0, minval=-500, maxval=500)
fastEMA = ema(src, len)

delta = kst - sig

buySignal = crossover(delta, 0) and kst < 0 and close > fastEMA
sellSignal = crossunder(delta, 0) and kst > 0 and close < fastEMA

longTrailPerc = input(title="Trail Long Loss (%)", type=input.float, minval=0.0, step=0.1, defval=1) * 0.01
shortTrailPerc = input(title="Trail Short Loss (%)",type=input.float, minval=0.0, step=0.1, defval=1) * 0.01

// STEP 2:
// Determine trail stop loss prices
longStopPrice = 0.0, shortStopPrice = 0.0

longStopPrice := if (strategy.position_size > 0)
    stopValue = close * (1 - longTrailPerc)
    max(stopValue, longStopPrice[1])
else
    0
shortStopPrice := if (strategy.position_size < 0)
    stopValue = close * (1 + shortTrailPerc)
    min(stopValue, shortStopPrice[1])
else
    999999

// Submit entry orders
if (buySignal)
    strategy.entry(id="EL", long=true)

if (sellSignal)
    strategy.entry(id="ES", long=false)

// STEP 3:
// Submit exit orders for trail stop loss price
if (strategy.position_size > 0)
    strategy.exit(id="XL TRL STP", stop=longStopPrice)

if (strategy.position_size < 0)
    strategy.exit(id="XS TRL STP", stop=shortStopPrice)


alertcondition(crossover(delta, 0) and kst < 0 and close > fastEMA,'Long alert', 'You should buy')

alertcondition(crossunder(delta, 0) and kst > 0 and close < fastEMA, 'Short alert', 'You should sell')
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-07. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/KST-EMA-Momentum-Trend-Following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Trend Momentum Trading Strategy with Dynamic Risk Management SystemPine Script · Momentum · 1h
- Multi Indicator Trend Momentum Trading Strategy An Optimized Quantitative Trading System Based on Bollinger Bands Fibonacci and ATRPine Script · Momentum · 1h
- Multi Trend Momentum Crossover Strategy with Volatility Optimization SystemPine Script · Momentum · 1d
- Multi Indicator Dynamic Stop Loss Momentum Trend Trading StrategyPine Script · Momentum · 1h
- Oscillator Candles Momentum Trading StrategyPine Script · Momentum · 1h
- Multi EMA Trend Momentum Trading Strategy with Risk Management SystemPine Script · Momentum · 1h