Lazy Bear Squeeze Momentum Strategy
The Lazy Bear Squeeze Momentum strategy is a quantitative trading strategy that combines Bollinger Bands, Keltner Channels and a momentum indicator. It utilizes Bollinger Bands and Keltner Channels to determine if…
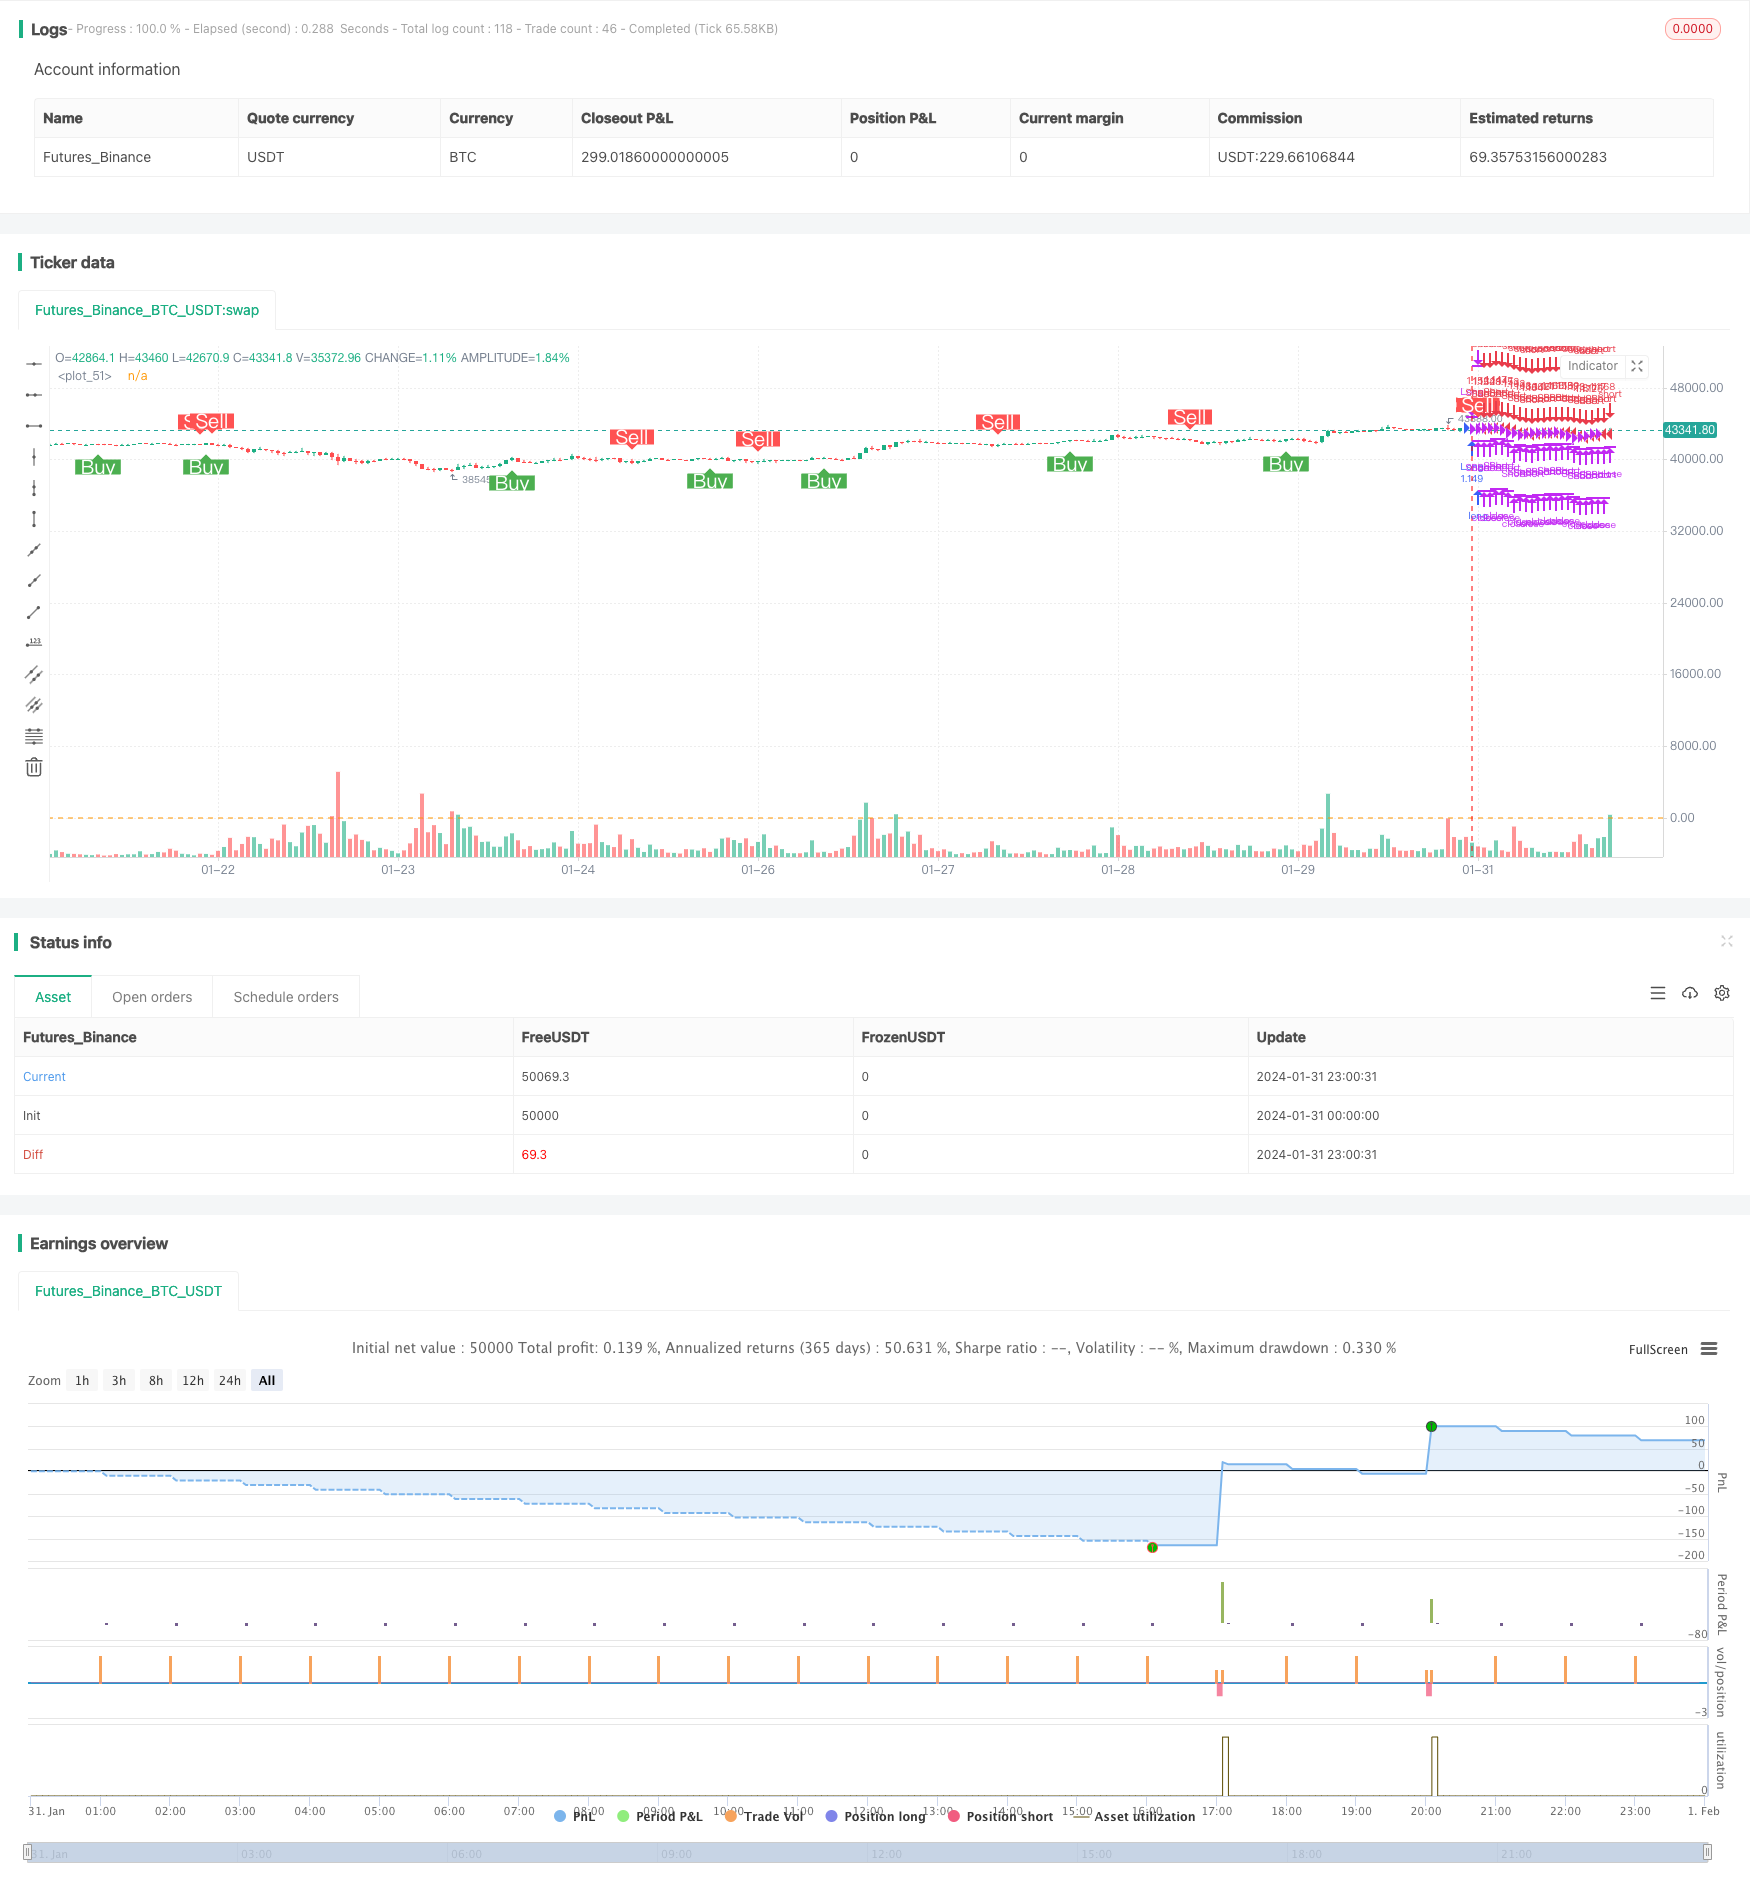
Overview
The Lazy Bear Squeeze Momentum strategy is a quantitative trading strategy that combines Bollinger Bands, Keltner Channels and a momentum indicator. It utilizes Bollinger Bands and Keltner Channels to determine if the market is currently in a squeeze, then uses a momentum indicator to generate trading signals.
The main advantage of this strategy is being able to automatically identify the start of trending moves and determine entry timing with the momentum indicator. However, there are also certain risks that need to be addressed through optimization across different products.
Strategy Logic
The Lazy Bear Squeeze Momentum strategy makes judgements based on the following three indicators:
- Bollinger Bands: Includes middle band, upper band and lower band
- Keltner Channels: Includes middle line, upper line and lower line
- Momentum Indicator: Current price minus price n days ago
When the Bollinger upper band is below the Keltner upper line and the Bollinger lower band is above the Keltner lower line, we determine the market is in a squeeze. This usually implies a trending move is about to start.
To pinpoint entry timing, we use the momentum indicator to gauge the speed of price changes. A buy signal is generated when momentum crosses above its moving average, and a sell signal when momentum crosses below its moving average.
Advantage Analysis
The main advantages of the Lazy Bear Squeeze Momentum strategy:
- Automatically identify early entries into new trends
- Combination of indicators prevents false signals
- Captures both trend and mean-reversion
- Customizable parameters for optimization
- Robust across different products
Risk Analysis
There are also certain risks to the Lazy Bear Squeeze Momentum strategy:
- Probability of false signals from Bollinger & Keltner
- Momentum instability, missing best entries
- Poor performance without optimization
- High correlation to product selection
To mitigate risks, recommendations include: optimizing lengths for Bollinger & Keltner, adjusting stop loss, selecting liquid products, verifying signals with other indicators.
Optimization Directions
The main directions to further enhance performance:
- Test combinations of parameters across products and timeframes
- Optimize lengths for Bollinger Bands and Keltner Channels
- Optimize length of momentum indicator
- Different stop loss/take profit for longs and shorts
- Additional indicators for signal verification
Through rigorous testing and optimization, the strategy's edge and profitability can be greatly improved.
Conclusion
The Lazy Bear Squeeze Momentum strategy has strong signal generation through a multi-indicator approach, and can effectively identify new trend starts. But it also carries risks that necessitate optimization across trading instruments. With continual testing and enhancement, it can become a robust algorithmic trading system.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_string_1 | 0 | Strategy Logic: Cross above 0 | LazyBear |
| v_input_1 | false | (?Backtesting Date Range)Custom Backtesting Date Range |
| v_input_2 | timestamp(01 Jan 2022 00:01 +0000) | Backtesting Start Time |
| v_input_3 | timestamp(31 Dec 2022 23:59 +0000) | Backtesting End Time |
| v_input_bool_1 | true | (?SL/TP For Long Strategy)Enable Long Strategy |
| v_input_float_1 | 5 | Stoploss % |
| v_input_float_2 | 5 | Take Profit % |
| v_input_bool_2 | true | (?SL/TP For Short Strategy)Enable Short Strategy |
| v_input_float_3 | 5 | Stoploss % |
| v_input_float_4 | 5 | Take Profit % |
| v_input_4 | 20 | (?Squeeze Momentum Settings)BB Length |
| v_input_5 | 2 | BB MultFactor |
| v_input_6 | 20 | KC Length |
| v_input_7 | 1.5 | KC MultFactor |
| v_input_8 | true | Use TrueRange (KC) |
| v_input_9 | 5 | Signal Length |
| v_input_10 | true | Show Buy/Sell SQM Labels |
Source Pine Script
/*backtest
start: 2024-01-31 00:00:00
end: 2024-02-01 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © mtahreemalam original strategy by LazyBear

strategy(title = 'SQM Strategy, TP & SL',
         shorttitle = 'Squeeze.M Strat',
         overlay = true,
         pyramiding = 0,
         default_qty_type = strategy.percent_of_equity,
         default_qty_value = 100,
         initial_capital = 1000,
         commission_type=strategy.commission.percent,
         commission_value=0.0,
         process_orders_on_close=true,
         use_bar_magnifier=true)
//Strategy logic
strategy_logic = input.string("Cross above 0", "Strategy Logic", options = ["LazyBear", "Cross above 0"])

// Date Range
testPeriodSwitch = input(false, "Custom Backtesting Date Range",group="Backtesting Date Range")
i_startTime = input(defval = timestamp("01 Jan 2022 00:01 +0000"), title = "Backtesting Start Time",group="Backtesting Date Range")
i_endTime = input(defval = timestamp("31 Dec 2022 23:59 +0000"), title = "Backtesting End Time",group="Backtesting Date Range")
timeCond = true
isPeriod = testPeriodSwitch == true ? timeCond : true

//// Stoploss and Take Profit Parameters
// Enable Long Strategy
enable_long_strategy = input.bool(true, title='Enable Long Strategy', group='SL/TP For Long Strategy', inline='1')
long_stoploss_value = input.float(defval=5, title='Stoploss %', minval=0.1, group='SL/TP For Long Strategy', inline='2')
long_stoploss_percentage = close * (long_stoploss_value / 100) / syminfo.mintick
long_takeprofit_value = input.float(defval=5, title='Take Profit %', minval=0.1, group='SL/TP For Long Strategy', inline='2')
long_takeprofit_percentage = close * (long_takeprofit_value / 100) / syminfo.mintick

// Enable Short Strategy
enable_short_strategy = input.bool(true, title='Enable Short Strategy', group='SL/TP For Short Strategy', inline='3')
short_stoploss_value = input.float(defval=5, title='Stoploss %', minval=0.1, group='SL/TP For Short Strategy', inline='4')
short_stoploss_percentage = close * (short_stoploss_value / 100) / syminfo.mintick
short_takeprofit_value = input.float(defval=5, title='Take Profit %', minval=0.1, group='SL/TP For Short Strategy', inline='4')
short_takeprofit_percentage = close * (short_takeprofit_value / 100) / syminfo.mintick

//// Inputs
//SQUEEZE MOMENTUM STRATEGY
length = input(20, title='BB Length', group = "Squeeze Momentum Settings")
mult = input(2.0, title='BB MultFactor', group = "Squeeze Momentum Settings")
source = close
lengthKC = input(20, title='KC Length', group = "Squeeze Momentum Settings")
multKC = input(1.5, title='KC MultFactor', group = "Squeeze Momentum Settings")
useTrueRange = input(true, title='Use TrueRange (KC)', group = "Squeeze Momentum Settings")
signalPeriod=input(5, title="Signal Length", group = "Squeeze Momentum Settings")
show_labels_sqm = input(title='Show Buy/Sell SQM Labels', defval=true, group = "Squeeze Momentum Settings")
h0 = hline(0)

// Defining MA
ma = ta.sma(source, length)

// Calculate BB
basis = ma
dev = mult * ta.stdev(source, length)
upperBB = basis + dev
lowerBB = basis - dev

// Calculate KC
range_1 = useTrueRange ? ta.tr : high - low
rangema = ta.sma(range_1, lengthKC)
upperKC = ma + rangema * multKC
lowerKC = ma - rangema * multKC


// SqzON | SqzOFF | noSqz
sqzOn = lowerBB > lowerKC and upperBB < upperKC
sqzOff = lowerBB < lowerKC and upperBB > upperKC
noSqz = sqzOn == false and sqzOff == false

// Momentum
val = ta.linreg(source - math.avg(math.avg(ta.highest(high, lengthKC), ta.lowest(low, lengthKC)), ta.sma(close, lengthKC)), lengthKC, 0)

red_line = ta.sma(val,signalPeriod)
blue_line = val

// lqm = if val > 0
//         if val > nz(val[1])
        // long_sqm_custom
        // if val < nz(val[1])
        // short_sqm_custom
// Plots
//plot(val, style = plot.style_line, title = "blue line", color= color.blue, linewidth=2)
//plot(ta.sma(val,SignalPeriod), style = plot.style_line, title = "red line",color = color.red, linewidth=2)

//plot(val, color=blue, linewidth=2)
//plot(0, color=color.gray, style=plot.style_cross, linewidth=2)
//plot(red_line, color=red, linewidth=2)

//LOGIC
//momentum filter
//filterMom = useMomAverage ? math.abs(val) > MomentumMin / 100000 ? true : false : true
//}

////SQM Long Short Conditions
//Lazy Bear Buy Sell Condition
// long_sqm_lazy = (blue_line>red_line)
// short_sqm_lazy = (blue_line<red_line)

long_sqm_lazy = ta.crossover(blue_line,red_line)
short_sqm_lazy = ta.crossunder(blue_line,red_line)


//Custom Buy Sell Condition
dir_sqm = val < 0 ? -1 : 1
long_sqm_custom = dir_sqm == 1 //and dir_sqm[1] == -1
short_sqm_custom = dir_sqm == -1 //and dir_sqm[1] == 1

long_sqm = strategy_logic == "LazyBear" ? long_sqm_lazy : long_sqm_custom
short_sqm = strategy_logic == "LazyBear" ? short_sqm_lazy : short_sqm_custom


// Plot Stoploss & Take Profit Levels
long_stoploss_price = strategy.position_avg_price * (1 - long_stoploss_value / 100)
long_takeprofit_price = strategy.position_avg_price * (1 + long_takeprofit_value / 100)
short_stoploss_price = strategy.position_avg_price * (1 + short_stoploss_value / 100)
short_takeprofit_price = strategy.position_avg_price * (1 - short_takeprofit_value / 100)
plot(enable_long_strategy and not enable_short_strategy ? long_stoploss_percentage : na, color=color.red, style=plot.style_linebr, linewidth=2, title='Long SL Level')
plot(enable_long_strategy and not enable_short_strategy ? long_takeprofit_percentage : na, color=color.green, style=plot.style_linebr, linewidth=2, title='Long TP Level')
plot(enable_short_strategy and not enable_long_strategy ? short_stoploss_price : na, color=color.red, style=plot.style_linebr, linewidth=2, title='Short SL Level')
plot(enable_short_strategy and not enable_long_strategy ? short_takeprofit_price : na, color=color.green, style=plot.style_linebr, linewidth=2, title='Short TP Level')


// Long Strategy
if long_sqm and enable_long_strategy == true
    strategy.entry('Long', strategy.long)
    strategy.exit('Long  SL/TP', from_entry='Long', loss=long_stoploss_percentage, profit=long_takeprofit_percentage)
    strategy.close('Long', comment = "L. CL")

// Short Strategy
if short_sqm and enable_short_strategy == true
    strategy.entry('Short', strategy.short)
    strategy.exit('Short SL/TP', from_entry='Short', loss=short_stoploss_percentage, profit=short_takeprofit_percentage)
    strategy.close('Short', comment = "S.Cl")

plot_sqm_long = long_sqm and not long_sqm[1]
plot_sqm_short = short_sqm and not short_sqm[1]

plotshape(plot_sqm_long and show_labels_sqm, title='Buy', style=shape.labelup, location=location.belowbar, size=size.normal, text='Buy', textcolor=color.new(color.white, 0), color=color.new(color.green, 0))
plotshape(plot_sqm_short and show_labels_sqm, title='Sell', style=shape.labeldown, location=location.abovebar, size=size.normal, text='Sell', textcolor=color.new(color.white, 0), color=color.new(color.red, 0))

// Date Range EXIT
if (not isPeriod)
    strategy.cancel_all()
    strategy.close_all()
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Lazy-Bear-Squeeze-Momentum-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Timeframe Unified Strategy Based on Quantitative Momentum and Convergence DivergencePine Script · Momentum · 1d
- Adaptive Trading Strategy Based on Momentum IndicatorsPine Script · Momentum · 1d
- Squeeze Momentum IndicatorPine Script · Momentum · 1d
- Squeeze Momentum Trading Strategy Based on LazyBear IndicatorPine Script · Momentum · 2h
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Momentum Strategy Based on LazyBears SqueezePine Script · Momentum · 1h