Leveraged RSI Strategy in Pine Script
This strategy aims to solve the problem that Pine Script cannot set leverage during backtesting to achieve compound interest with leverage. The strategy dynamically calculates the position size based on the strategy…
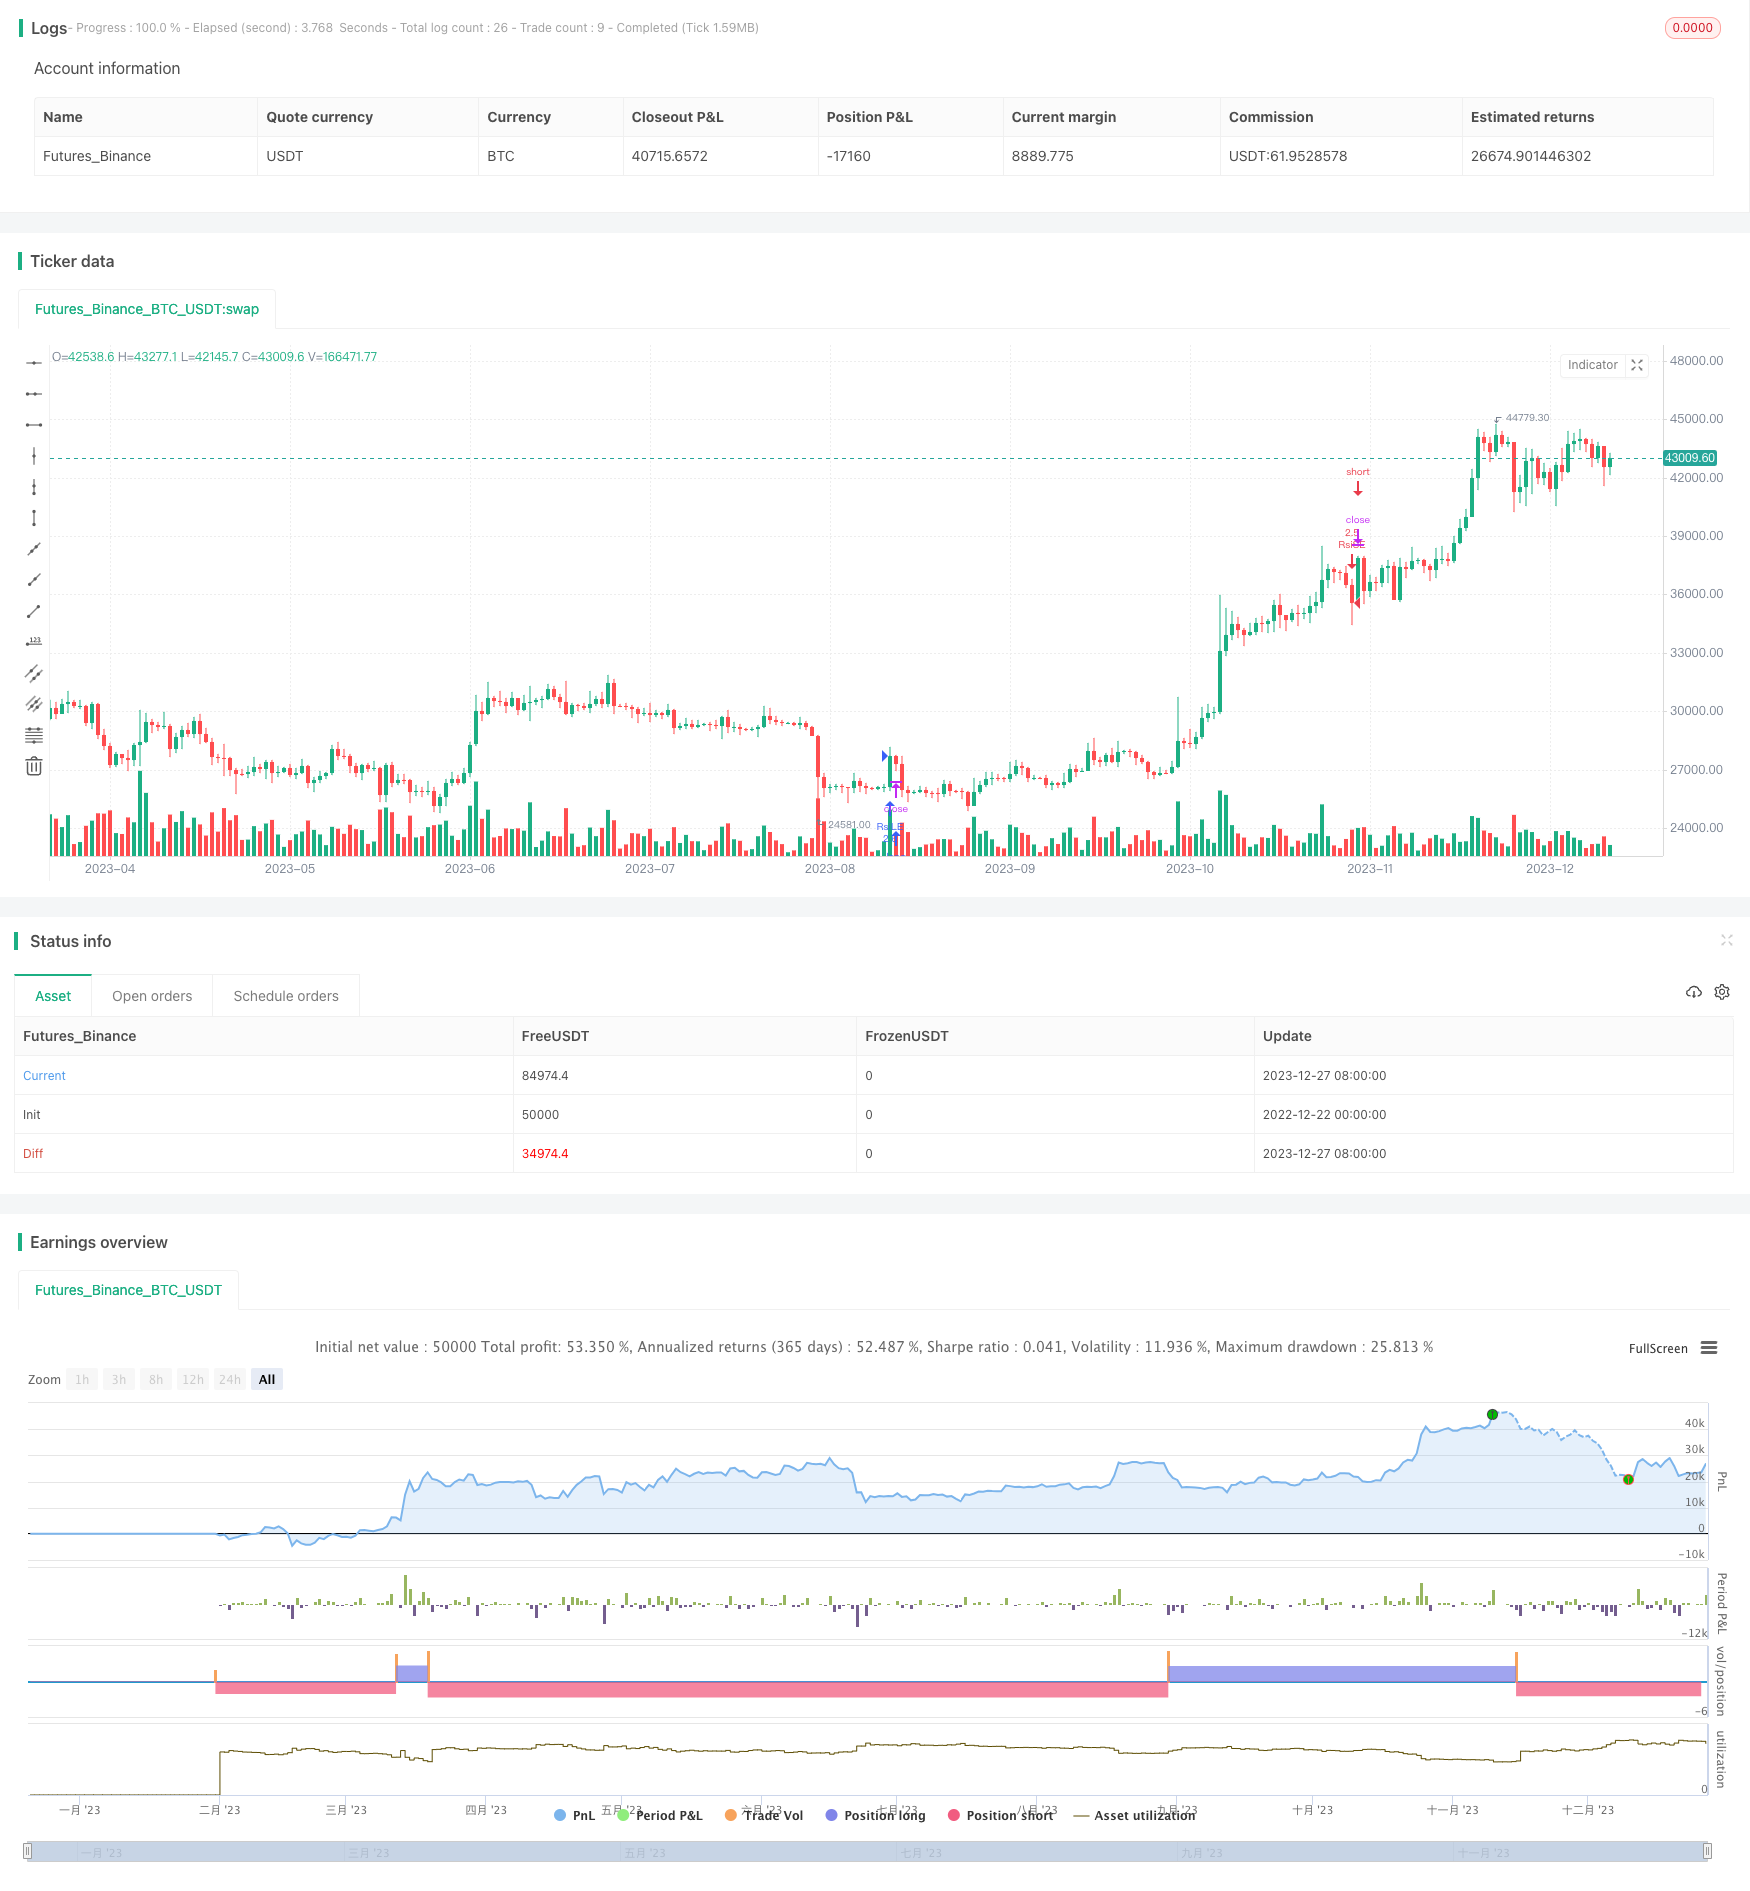
Overview
This strategy aims to solve the problem that Pine Script cannot set leverage during backtesting to achieve compound interest with leverage. The strategy dynamically calculates the position size based on the strategy equity, set leverage ratio and closing price.
Strategy Logic
- Set precision precision to control the precision of position size
- Set leverage ratio leverage, default is 1x
- Calculate position size:
Lev = math.max(math.round(strategy.equity * leverage / close), 0), make it proportional to equity and leverage - Entry signal: long when RSI breaks above 30 from below; short when RSI breaks below 70 from above
- Place order with calculated size Lev
Advantage Analysis
- Solve the problem that Pine Script cannot set leverage
- Position size changes proportionally with equity changes, achieving compound interest with leverage
- RSI filtered, avoiding unnecessary trades
- Precision precision is adjustable to meet different requirements
Risk Analysis
- Excessive leverage can easily cause liquidation
- Need to adjust leverage and position size properly to control risk
Optimization Direction
- Can test stability under different parameters
- Can incorporate stop loss to further control risk
- Can consider multi-factor model to improve strategy performance
Summary
This strategy implements leverage setting in Pine Script, solving the problem that backtesting cannot simulate leverage, calculates position size linked to equity to achieve compound interest with leverage. The strategy is simple and effective, can be further optimized, and worth learning.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | length |
| v_input_2 | 30 | overSold |
| v_input_3 | 70 | overBought |
| v_input_int_1 | true | Precision |
| v_input_int_2 | true | Leverage |
Source Pine Script
/*backtest
start: 2022-12-22 00:00:00
end: 2023-12-28 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © RingsCherrY

//@version=5
strategy("How to use Leverage in PineScript", overlay=true, pyramiding=1, initial_capital=1000000, default_qty_type=strategy.percent_of_equity, default_qty_value=100, calc_on_order_fills=false, slippage=0, commission_type=strategy.commission.percent, commission_value=0.04)

//////////////////////////////////////////
////////////////Indicators////////////////
//////////////////////////////////////////

length = input( 14 )
overSold = input( 30 )
overBought = input( 70 )
price = close
vrsi = ta.rsi(price, length)
co = ta.crossover(vrsi, overSold)
cu = ta.crossunder(vrsi, overBought)

//////////////////////////////////////////
/////////////////Leverage/////////////////
//////////////////////////////////////////


//The number of decimal places for each position opening, i.e., the accuracy
precision = input.int(1,title='Precision')

//Leverage, the default is 1, here is not recommended to open a high leverage

leverage = input.int(1,title='Leverage',minval = 1, maxval = 100 ,step = 1)

//Calculate the number of open contracts, here using equity for calculation, considering that everyone compound interest is used for trading equity
Lev = math.max(math.round(strategy.equity * leverage  / close , precision), 0)

if (not na(vrsi))
	if (co)
		strategy.entry("RsiLE", strategy.long,qty = Lev, comment="RsiLE")
	if (cu)
		strategy.entry("RsiSE", strategy.short,qty = Lev, comment="RsiSE")
//plot(strategy.equity, title="equity", color=color.red, linewidth=2, style=plot.style_areabr)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Leveraged-RSI-Strategy-in-Pine-Script.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.