Linear Regression Channel Breakout Trading Strategy
This strategy uses the upper and lower bands of the linear regression channel, combined with double standard deviation to set breakout buy and sell signals, to establish positions when prices break out. It also uses…
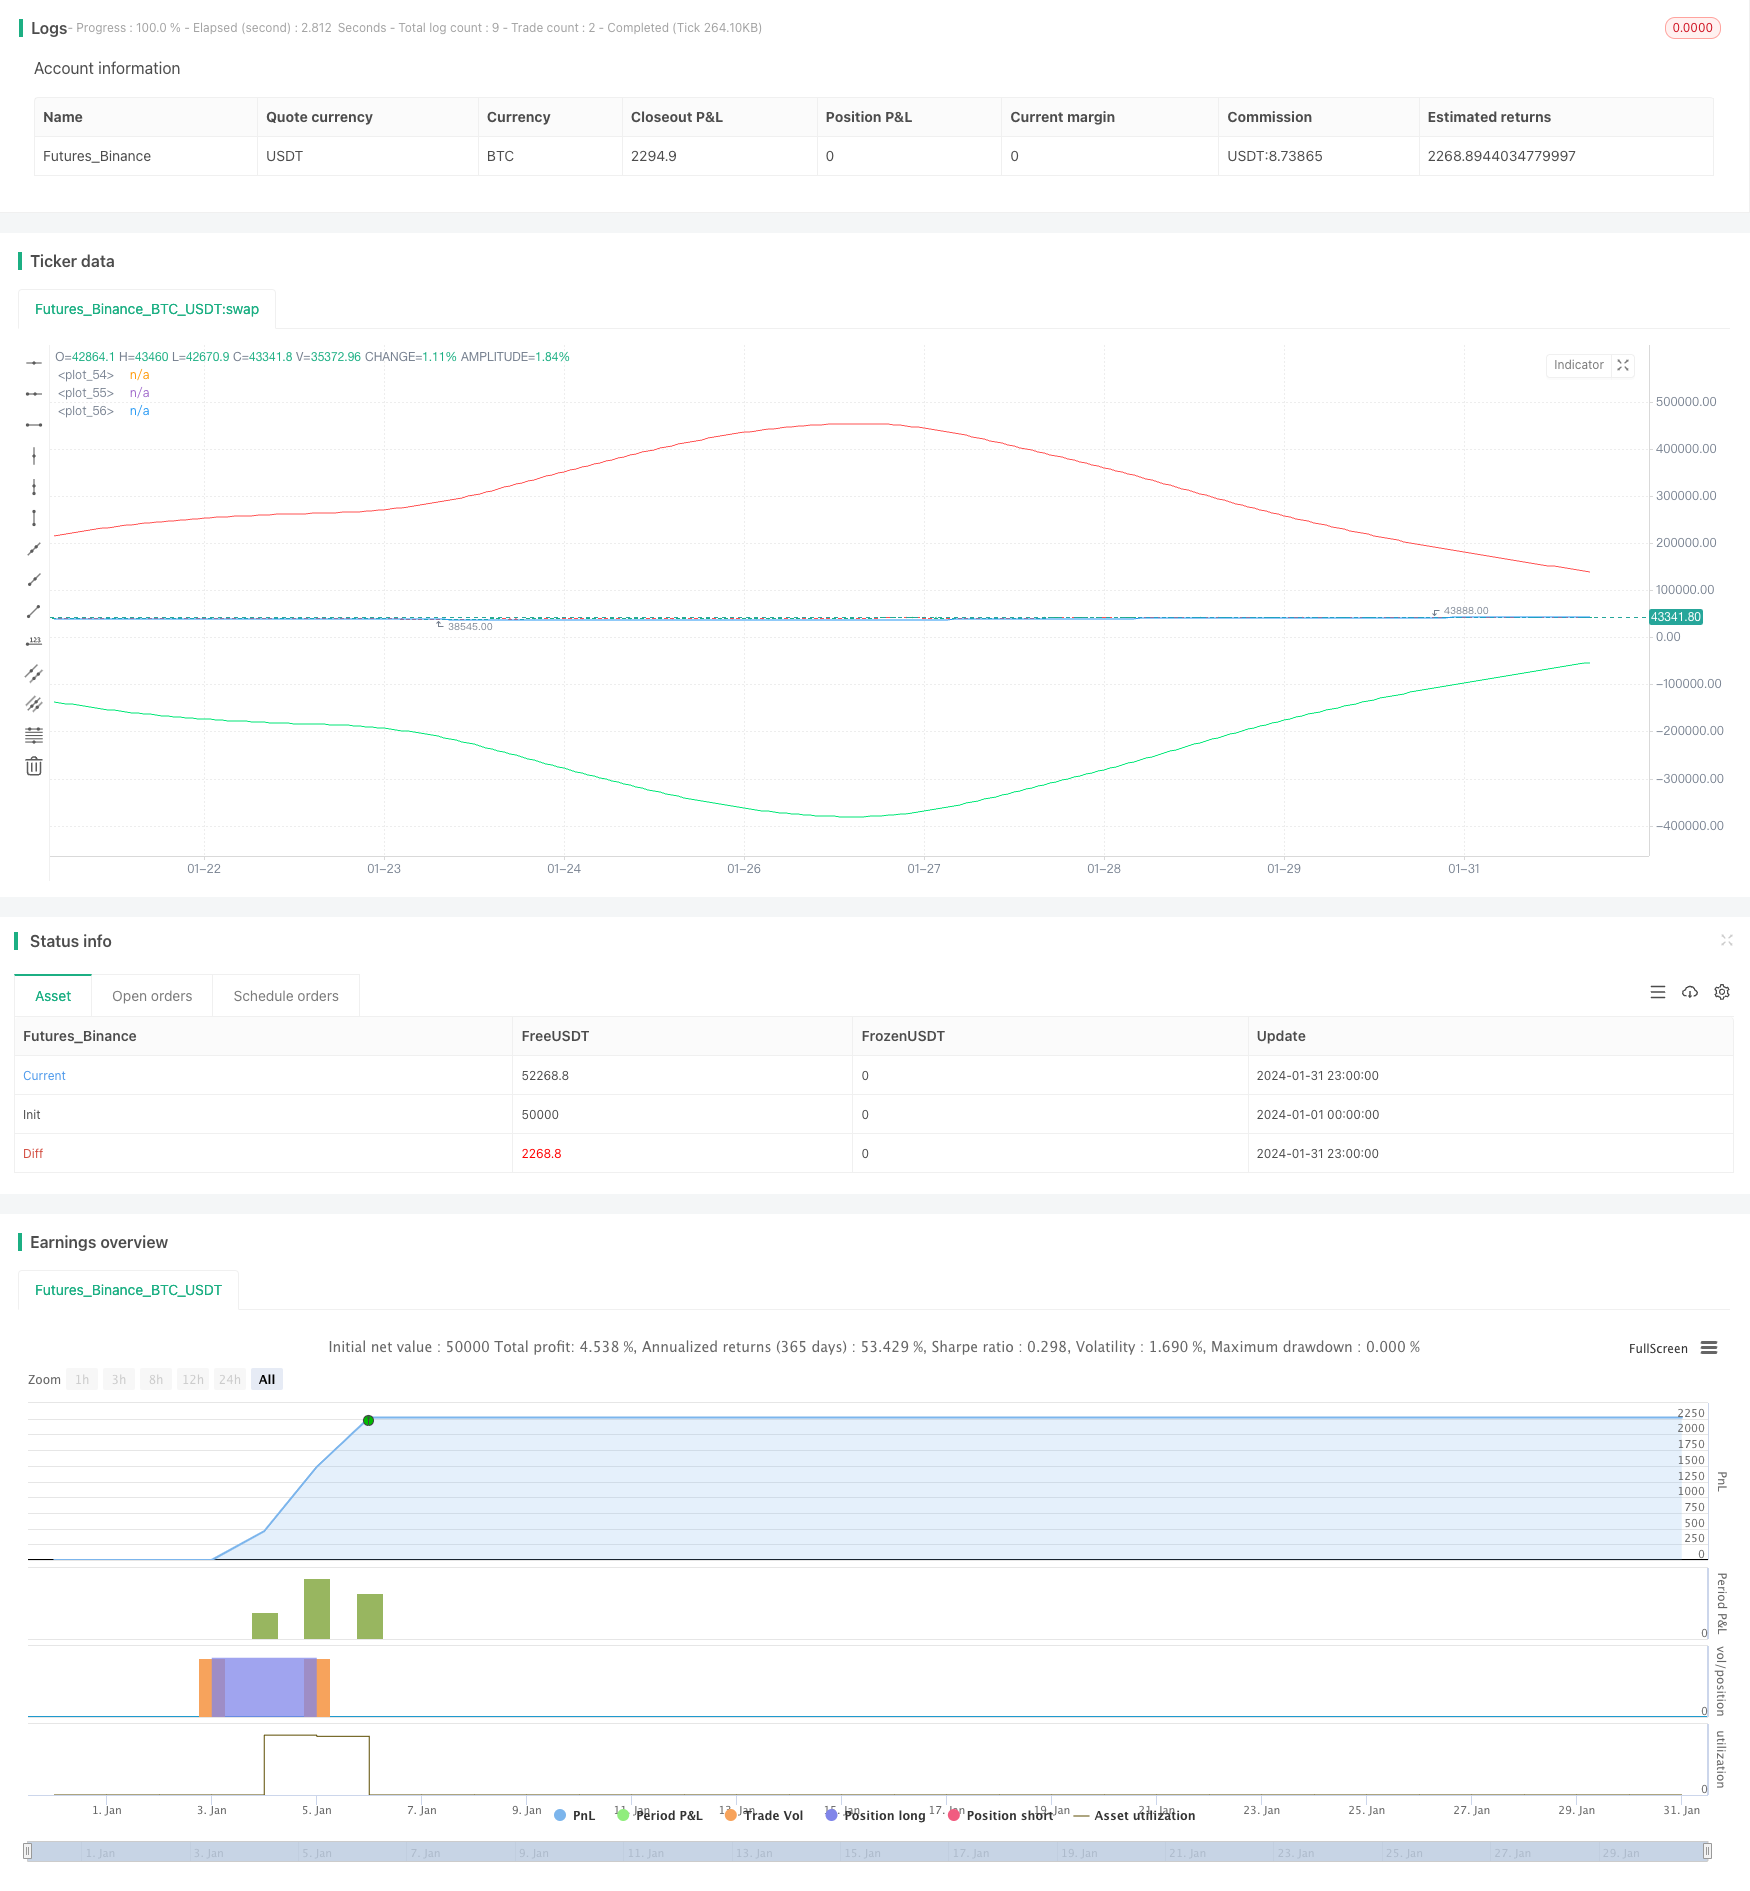
Overview
This strategy uses the upper and lower bands of the linear regression channel, combined with double standard deviation to set breakout buy and sell signals, to establish positions when prices break out. It also uses the crossover of the middle line of the channel as the profit-taking signal to lock in profits.
Strategy Logic
The core logic of this strategy is based on the upper band, lower band and middle line of the linear regression channel. The specific calculation process is as follows:
Calculate the linear regression value linreg of prices, and the next period's linear regression value linreg_p
Calculate the slope slope and intercept intercept of the linear regression line based on linreg
Calculate the deviation deviation of prices relative to the regression line
Set the multiple dev of the deviation to get the offset of the upper and lower bands
When price breaks out upwards from the lower band, set buy signal buy
When price breaks out downwards from the upper band, set sell signal sell
When price reverses from the middle line of the channel, set take profit signal exit
Set up trading logic based on buy, sell and exit signals
Advantage Analysis
The biggest advantage of this strategy is that it utilizes the medium and long term trend reflected by the linear regression channel. Specifically:
The upper and lower bands can effectively reflect the normal range of price fluctuations. Using them to set trading signals can reduce false signals.
The middle line crossover as the profit-taking signal can maximize profits and avoid losses caused by reversals after making profits.
The linear regression channel has some lag, which can effectively filter out short-term market noise and make trading signals more reliable.
This strategy has few parameters and is easy to implement, suitable for algorithmic trading.
Risk Analysis
There are some risks to this strategy:
The lag of the linear regression channel may miss trends after drastic short-term changes. The period can be shortened to optimize.
Improper setting of the deviation multiplier can also lead to false signals. Parameters can be optimized through backtesting.
Relying solely on breakout signals can lead to whipsaw losses. Other indicators can be used for signal filtering.
There are some curve fitting risks. Combining with other channel indicators or testing different data sources may help.
Optimization Directions
The main optimization directions for this strategy:
Optimize the length of the linear regression channel to balance lag and sensitivity.
Optimize the deviation multiplier to improve signal quality while maximizing risk control.
Add other indicators for signal filtering to improve win rate, e.g. EMA, KDJ etc.
Add stop loss mechanisms such as ATR trailing stop loss.
Test the impact of different data sources on the strategy, e.g. adjusted close, index data etc.
Dynamically adjust parameters or signal weights based on market conditions.
Conclusion
In summary, this is a breakout system using linear regression channel as the signal indicator. The strategy logic is clear and easy to understand, with few parameters, making live trading relatively easy to implement. However, how to dynamically optimize parameters based on changing market conditions and combine other indicators for signal filtering is key to the success of this strategy. Through continuous testing and optimization, this strategy can become a stable profit-generating quantitative system.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 100 | length |
| v_input_3 | false | offset |
| v_input_4 | 2 | Deviation |
| v_input_5 | true | smoothing |
| v_input_6 | Resolution | |
| v_input_7 | 0 | Signals Display: Recent | All |
| v_input_8 | false | End At Bar Index |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Robotrading
//@version=4

strategy("robotrading linreg", "linreg", overlay=true, default_qty_type = strategy.percent_of_equity, default_qty_value = 10, commission_value = 0.1)

//Settings
source      = input(close)
length      = input(100, minval=1)
offset      = input(0, minval=0)
dev         = input(2.0, "Deviation")
smoothing   = input(1, minval=1)
mtf_val     = input("", "Resolution", input.resolution)
signals     = input("Recent", "Signals Display", options=["Recent", "All"])
goto        = input(0, "End At Bar Index")

//Lin.reg.
cc(x) => x=="Red"?color.red:x=="Lime"?color.lime:x=="Orange"?color.orange:x=="Teal"?color.teal:x=="Yellow"?color.yellow:x=="Black"?color.black:color.white
data(x) => sma(security(syminfo.tickerid, mtf_val!="" ? mtf_val : timeframe.period, x), smoothing)
linreg = data(linreg(source, length, offset))
linreg_p = data(linreg(source, length, offset+1))

//Deviation
x = bar_index
slope = linreg - linreg_p
intercept = linreg - x*slope
deviationSum = 0.0
for i = 0 to length-1
    deviationSum:= deviationSum + pow(source[i]-(slope*(x-i)+intercept), 2)
deviation = sqrt(deviationSum/(length))
x1 = x-length
x2 = x
y1 = slope*(x-length)+intercept
y2 = linreg

//Cross
dm_current = -deviation*dev + y2
dp_current = deviation*dev + y2
ex_current = (dm_current + dp_current) / 2
buy = crossunder(close, dm_current)
sell = crossover(close, dp_current)
exit = crossover(close, ex_current) or crossunder(close, ex_current)

//Channel
updating = goto <= 0 or x < goto
// if updating
//     line b = line.new(x1, y1, x2, y2, xloc.bar_index, extend.right, color.aqua, width = 3)
//     line.delete(b[1])
//     line dp = line.new(x1, deviation*dev + y1, x2, deviation*dev + y2, xloc.bar_index, extend.right, color.red, width = 3)
//     line.delete(dp[1])
//     line dm = line.new(x1, -deviation*dev + y1, x2, -deviation*dev + y2, xloc.bar_index, extend.right, color.lime, width = 3)
//     line.delete(dm[1])

//Lines
plot(dm_current, color = color.lime)
plot(dp_current, color = color.red)
plot(ex_current)

//Trading
if ex_current > 0
    strategy.entry("Long", strategy.long, na, limit = dm_current)
    strategy.entry("Short", strategy.short, na, limit = dp_current)
    strategy.exit("ExitLong", "Long", limit = ex_current)
strategy.exit("ExitShort", "Short", limit = ex_current)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Linear-Regression-Channel-Breakout-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- Adaptive Trading Strategy Based on ADX IndicatorPine Script · Breakout · 1d
- Average Line Breakthrough StrategyPine Script · Breakout · 1d
- BB Breakout StrategyPine Script · Breakout · 1d