Strategy vault / Machine learning
London MACD RSI Bitcoin Trading Strategy
This strategy is a London session bitcoin trading strategy based on the technical indicators MACD and RSI. It only opens positions during the London session, using MACD to determine the trend direction and RSI to…
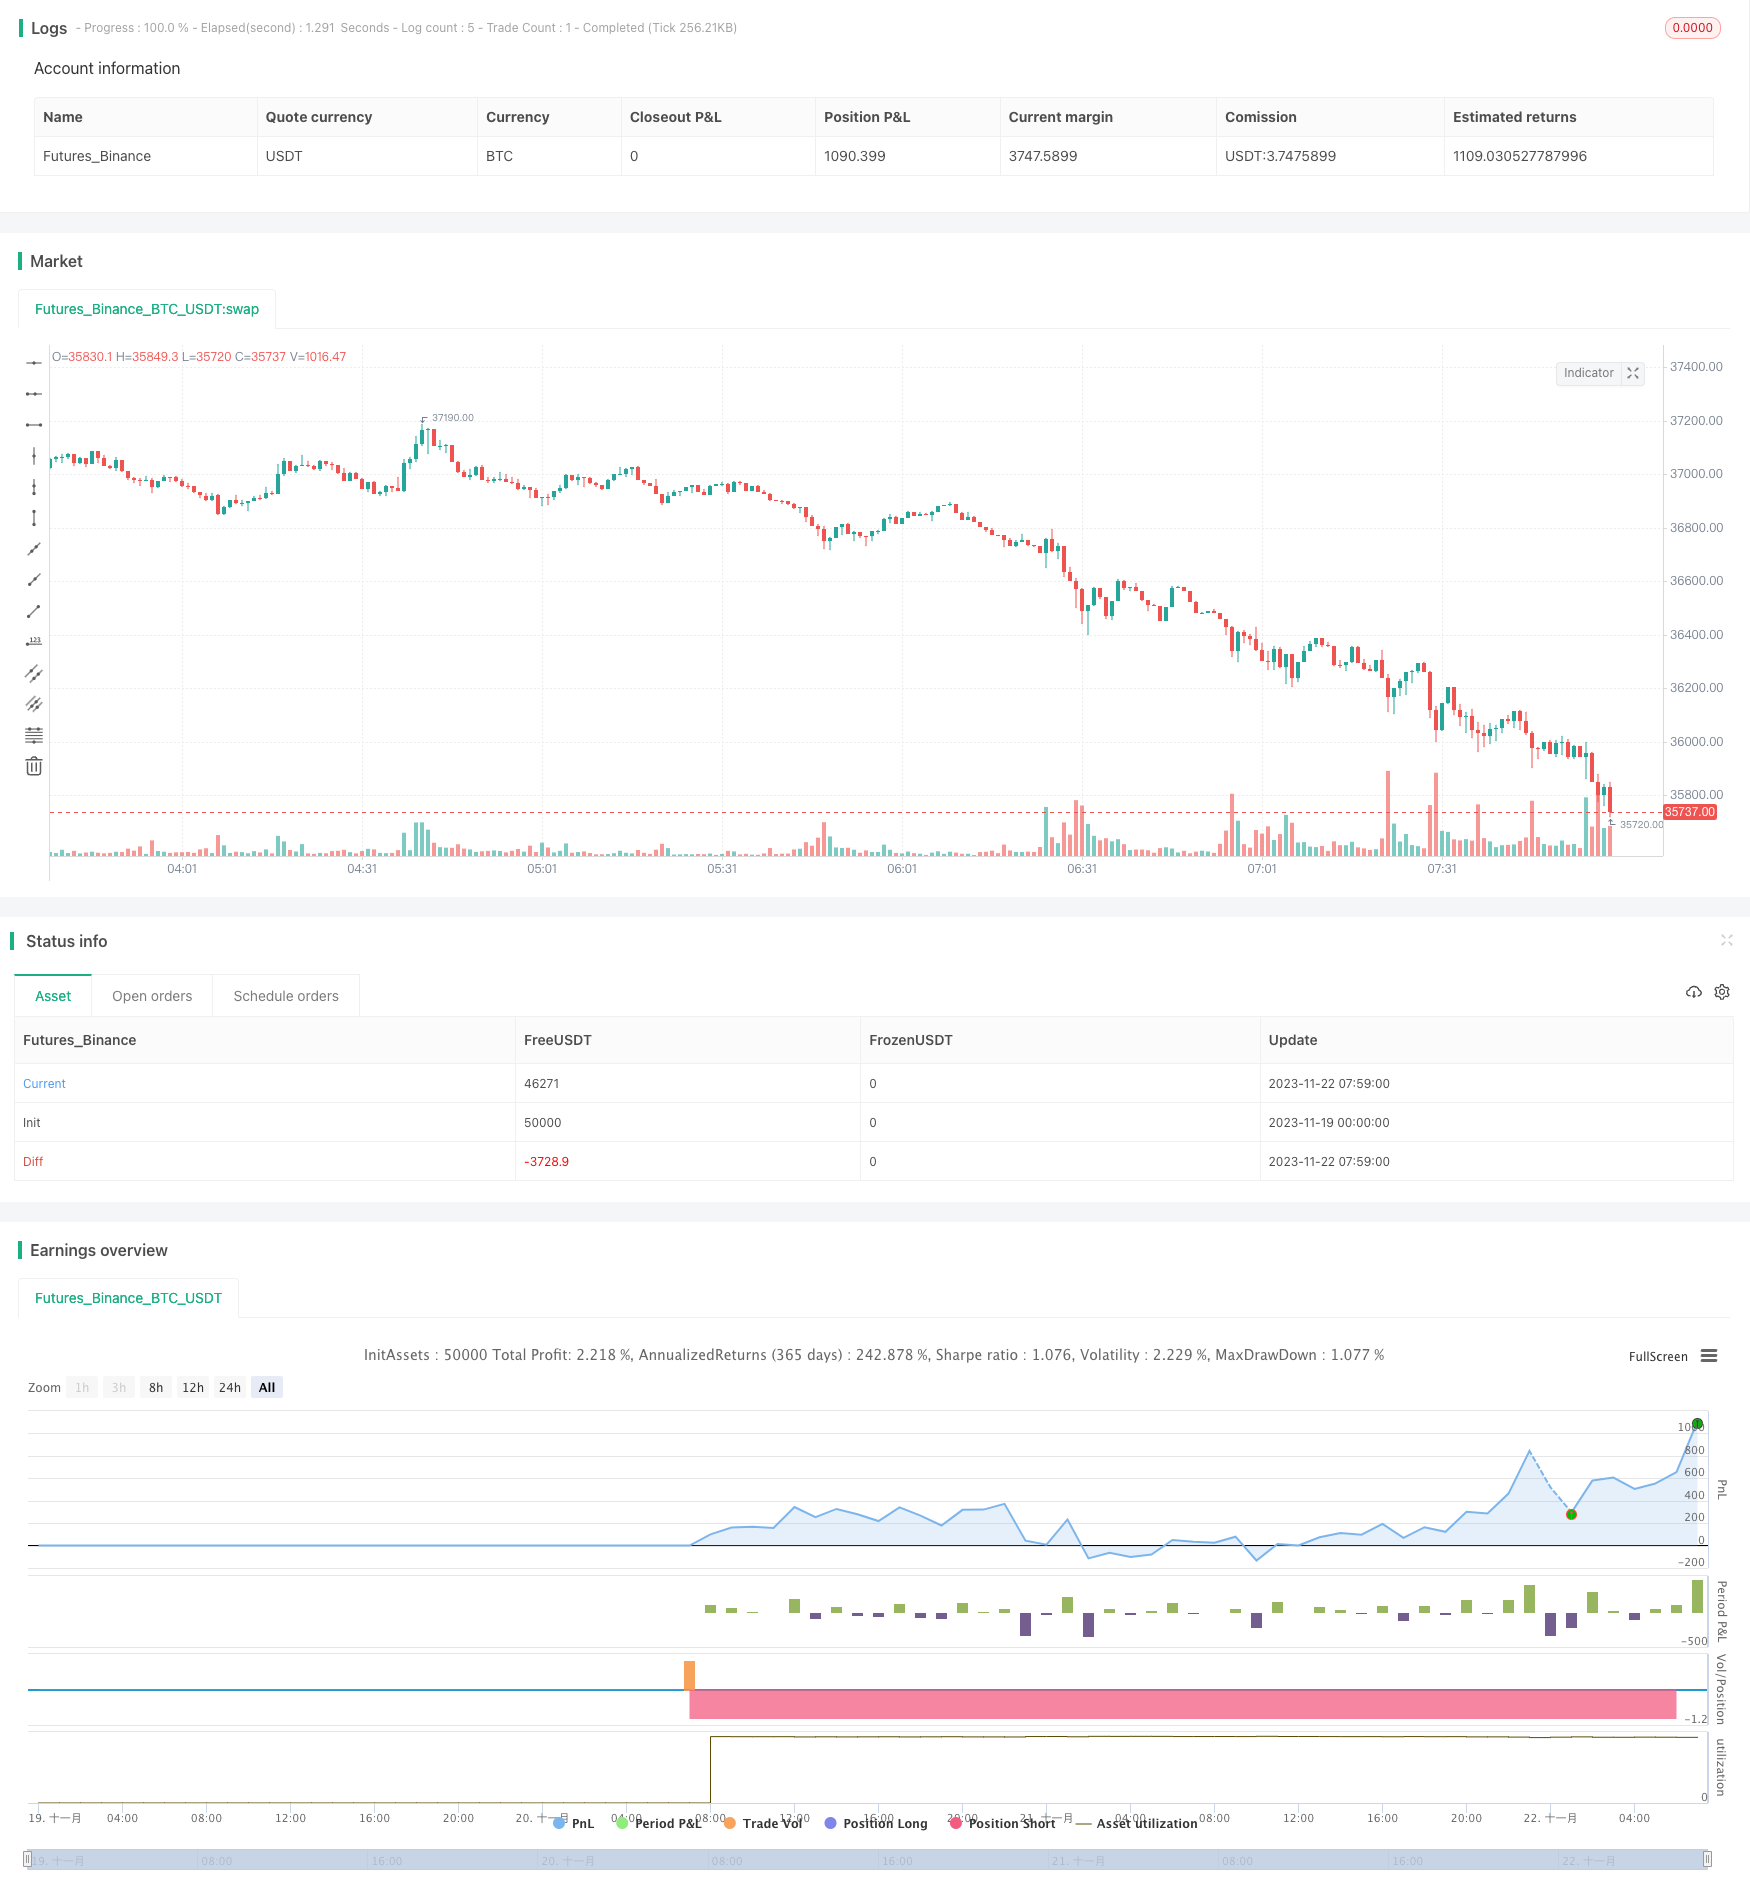
Overview
This strategy is a London session bitcoin trading strategy based on the technical indicators MACD and RSI. It only opens positions during the London session, using MACD to determine the trend direction and RSI to judge overbought and oversold conditions. The strategy is suitable for medium and short-term bitcoin trading.
Principles
London Trading Session
The London trading session is very active in the forex market, with most institutions participating. This strategy sets the London session from 7 am to 4 pm, and only opens positions during this period.
MACD to Determine Trend
MACD can generally determine the trend direction. When the fast line crosses above the slow line, it is a golden cross, indicating an uptrend to go long. When the fast line crosses below the slow line, it is a death cross, indicating a downtrend to go short. This strategy utilizes this principle to determine the trend direction.
RSI to Judge Overbought/Oversold
RSI can judge whether the market is overbought or oversold. Above 70 indicates overbought, while below 30 oversold. This strategy uses this to set stop loss exit points.
Advantage Analysis
The biggest advantage of this strategy is that it combines trend trading and rhythm trading based on overbought/oversold conditions. When the trend is unclear, it can use MACD to judge the possible trend; use RSI to control risks and avoid chasing rises and selling falls blindly without a clear trend. In addition, this strategy only opens positions during the London session dominated by institutions, reducing the impact of irrational price fluctuations.
Risk Analysis
The main risk of this strategy is that MACD, as a technical indicator for range-bound markets, does not work very well in apparent trends. If faced with a prolonged one-way trend, the MACD golden/death crosses may frequently fail. In addition, RSI can also fail when hovering at high or low levels for extended periods. To reduce these risks, we can appropriately adjust parameters or add other filters to ensure opening positions only on high probability signals.
Optimization
This strategy can be optimized in several aspects:
Add other technical filters like Bollinger Bands and KDJ to avoid false breakouts.
Add profit taking mechanisms like trailing stop loss or price gap take profit to lock in more profits.
Optimize parameters by adjusting MACD and RSI parameters to suit different market conditions.
Add machine learning elements, using LSTM models etc to determine trend.
Conclusion
Overall this is a reliable London session bitcoin trading strategy. It combines trend and rhythm, filtering out invalid signals while ensuring relatively high profitability. Through continuous optimization of parameters and integrating more technical indicators, this strategy can further enhance stability and profitability. It suits investors with some knowledge of the London session, MACD and RSI technical indicators.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 6 | London Session Start Hour |
| v_input_2 | 59 | London Session Start Minute |
| v_input_3 | 15 | London Session End Hour |
| v_input_4 | 59 | London Session End Minute |
| v_input_5 | 12 | Fast Length |
| v_input_6 | 26 | Slow Length |
| v_input_7 | 9 | Signal SMA |
| v_input_8 | 14 | RSI Length |
| v_input_9 | 65 | RSI Overbought |
| v_input_10 | 35 | RSI Oversold |
Source Pine Script
/*backtest
start: 2023-11-19 00:00:00
end: 2023-11-22 08:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("London MACD RSI Strategy -1H BTC", overlay=true)

// Define London session times
london_session_start_hour = input(6, title="London Session Start Hour")
london_session_start_minute = input(59, title="London Session Start Minute")
london_session_end_hour = input(15, title="London Session End Hour")
london_session_end_minute = input(59, title="London Session End Minute")

// Define MACD settings
fastLength = input(12, title="Fast Length")
slowLength = input(26, title="Slow Length")
signalSMA = input(9, title="Signal SMA")

// RSI settings
rsiLength = input(14, title="RSI Length")
rsiOverbought = input(65, title="RSI Overbought")
rsiOversold = input(35, title="RSI Oversold")

// Calculate MACD
[macdLine, signalLine, _] = ta.macd(close, fastLength, slowLength, signalSMA)

// Calculate RSI
rsi = ta.rsi(close, rsiLength)

// Convert input values to timestamps
london_session_start_timestamp = timestamp(year, month, dayofmonth, london_session_start_hour, london_session_start_minute)
london_session_end_timestamp = timestamp(year, month, dayofmonth, london_session_end_hour, london_session_end_minute)

// Filter for London session
in_london_session = time >= london_session_start_timestamp and time <= london_session_end_timestamp

// Long and Short Conditions
longCondition = ta.crossover(macdLine, signalLine) and rsi < rsiOversold and in_london_session
shortCondition = ta.crossunder(macdLine, signalLine) and rsi > rsiOverbought and in_london_session

// Strategy entries and exits
if (longCondition)
    strategy.entry("Long", strategy.long)
if (shortCondition)
    strategy.entry("Short", strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/London-MACD-RSI-Bitcoin-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA and RSI Quantitative Trading StrategyPine Script · Machine learning · 1h
- Triple Moving Average Combined with MACD Quantitative StrategyPine Script · Machine learning · 1d
- Multi indicator Assisted StrategyPine Script · Machine learning · 1d
- SMA and RSI Combination Trading StrategyPine Script · Machine learning · 2d
- Market Structure Swing Trading StrategyPine Script · Machine learning · 1d
- ADX EFI 50 Moving Average Channel Pullback StrategyPine Script · Machine learning · 1h