LPB Microcycles Adaptive Oscillation Contour Tracking Strategy
The strategy uses the Hodrick-Prescott (HP) filter to smooth the price and extract the price trend. Then it calculates a customized weighted average price (VWAP) based on the user-defined time range. It goes long…
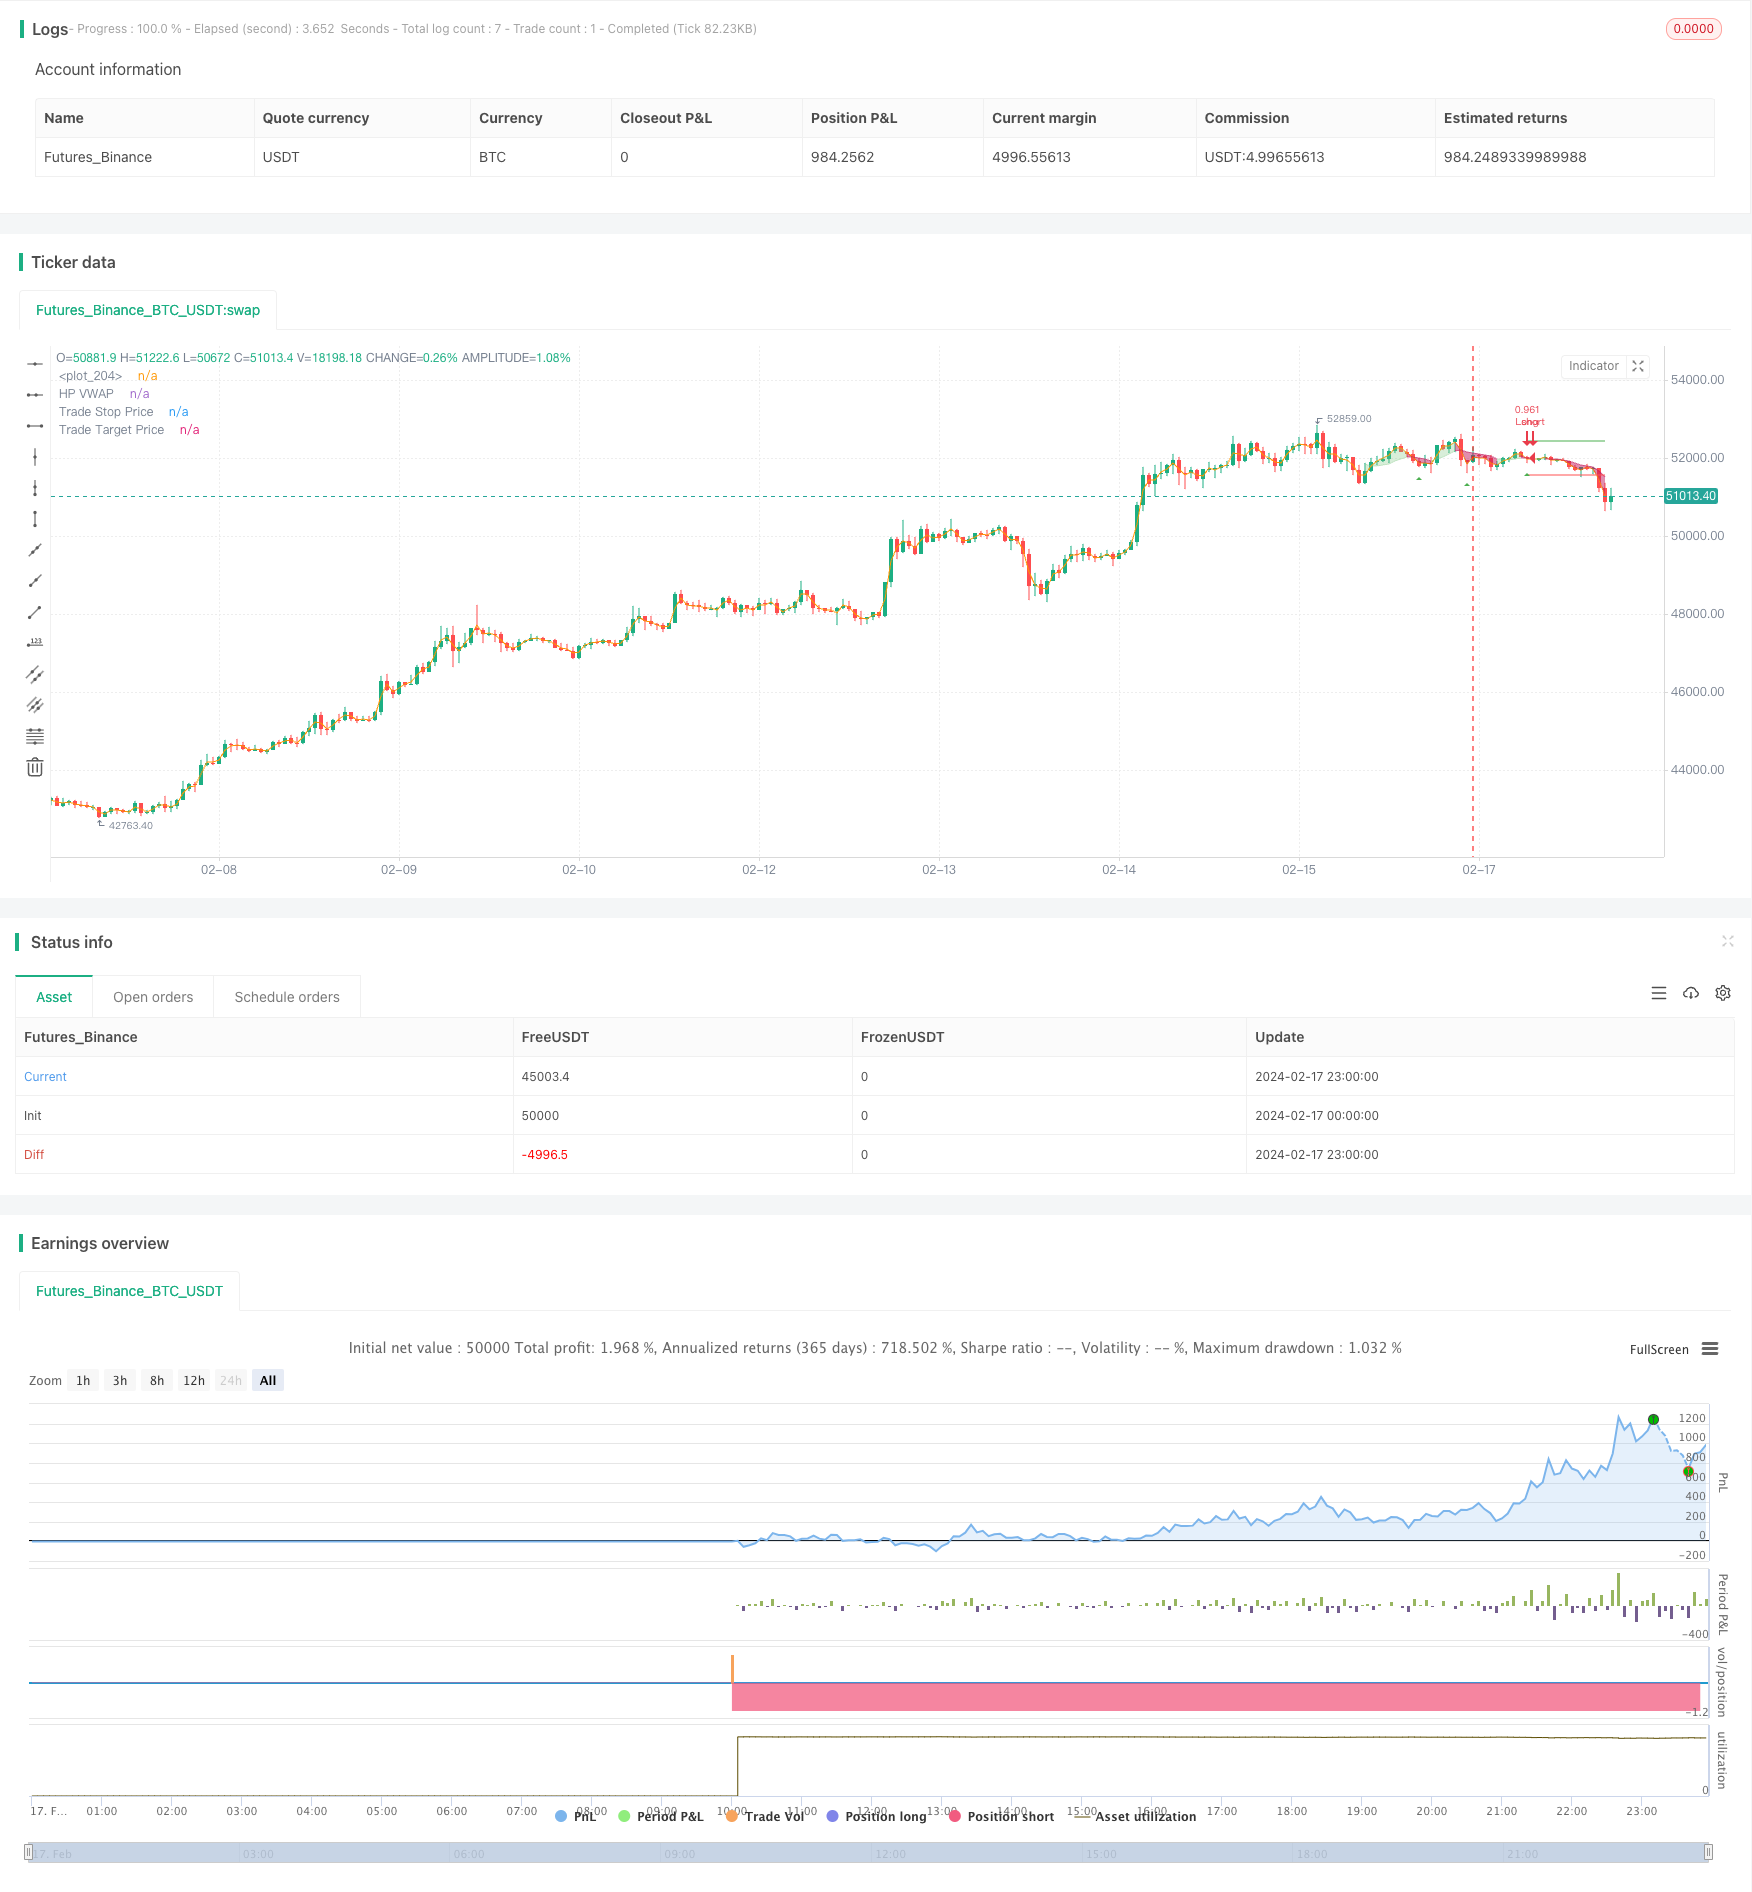
Overview
The strategy uses the Hodrick-Prescott (HP) filter to smooth the price and extract the price trend. Then it calculates a customized weighted average price (VWAP) based on the user-defined time range. It goes long when the price is above the trendline and goes short when below. It also incorporates ATR stop loss to control trading risk.
Strategy Principles
Use HP filter to extract price trend. HP filter uses optimization methods to extract the long-term trend component of prices while filtering out short-term fluctuations.
Calculate VWAP based on user-customized time range. VWAP can reflect average prices across periods more accurately.
Meet the long condition when price is above HP trendline; meet the short condition when price is below. This captures upside breakouts or downside breakdowns.
ATR stop loss assumes reasonable risk and prevents excessive losses.
Advantage Analysis
HP filter extracts smoother price trends than MA-based indicators, avoiding distraction from short-term price swings.
Customizable VWAP periods adapt better to changing market cycles.
Trading along the trend direction aligns with trend trading concepts and has higher win rates.
ATR stop loss controls loss per trade, preventing oversized losses.
Highly adjustable parameters provide greater optimization space for different markets.
Risks & Solutions
Stop loss may get hit frequently during range-bound consolidations. Can loosen stop loss slightly.
End-of-trend retracements often produce false breakouts that trap the strategy. Should combine with other indicators to identify end of trends and close positions timely.
Improper VWAP period settings may miss more effective trading opportunities. Should dynamically adjust VWAP period with trend indicators.
Optimization Directions
HP filter parameter λ adjusts the smoothing intensity. Larger λ makes trendline smoother and better captures long-term trends; smaller λ makes it more responsive to price changes and suits middle-short opportunities.
ATR multiplier tunes stop loss range. Can coordinate with λ parameter for optimization. Larger λ warrants wider stops; smaller λ allows tighter stops and locks in more profits.
Risk:Reward ratio directly impacts P&L ratio. Can test different ratios for drawdown control and profit potential.
Conclusion
The strategy overall adopts a trend following approach. Extensive parameter tuning targets optimization across long, medium and short timeframes, with strong win rates and profit potential. Reasonable risk control prevents oversized losses per trade. In summary, by extracting price trends scientifically and highly adjustable parameters, the strategy has good application prospects.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Start Date |
| v_input_2 | true | Start Month |
| v_input_3 | 2010 | Start Year |
| v_input_4 | 31 | End Date |
| v_input_5 | 12 | End Month |
| v_input_6 | 2021 | End Year |
| v_input_12 | 1000 | Smoothing Factor (Lambda) |
| v_input_13 | 100 | Filter Length |
| v_input_14 | 1 | TimeFrame |
| v_input_15 | true | Show barcolors |
| v_input_7 | true | (?Strategy Settings)Stop Loss ATR |
| v_input_8 | true | R:R |
| v_input_9 | 10000 | (?Backtester Settings)Starting Balance |
| v_input_10 | true | Risk Per Trade |
| v_input_11 | true | Draw Backtester |
Source Pine Script
/*backtest
start: 2024-02-17 00:00:00
end: 2024-02-18 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © tathal animouse hajixde

//@version=4
strategy("LPB MicroCycles Strategy", "HPVWAP", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100, max_bars_back=5000)
startDate = input(title="Start Date", type=input.integer,
     defval=1, minval=1, maxval=31)
startMonth = input(title="Start Month", type=input.integer,
     defval=1, minval=1, maxval=12)
startYear = input(title="Start Year", type=input.integer,
     defval=2010, minval=1800, maxval=2100)

endDate = input(title="End Date", type=input.integer,
     defval=31, minval=1, maxval=31)
endMonth = input(title="End Month", type=input.integer,
     defval=12, minval=1, maxval=12)
endYear = input(title="End Year", type=input.integer,
     defval=2021, minval=1800, maxval=2100)

// STEP 2:
// Look if the close time of the current bar
// falls inside the date range
inDateRange = true

///

// Strategy Settings
var g_strategy      = "Strategy Settings"
stopMultiplier      = input(title="Stop Loss ATR", type=input.float, defval=1.0, group=g_strategy, tooltip="Stop loss multiplier (x ATR)")
rr                  = input(title="R:R", type=input.float, defval=1.0, group=g_strategy, tooltip="Risk:Reward profile")

/// Backtester Settings
var g_tester        = "Backtester Settings"
startBalance        = input(title="Starting Balance", type=input.float, defval=10000.0, group=g_tester, tooltip="Your starting balance for the custom inbuilt tester system")
riskPerTrade        = input(title="Risk Per Trade", type=input.float, defval=1.0, group=g_tester, tooltip="Your desired % risk per trade (as a whole number)")
drawTester          = input(title="Draw Backtester", type=input.bool, defval=true, group=g_tester, tooltip="Turn on/off inbuilt backtester display")

////////////////INPUTS///////////////////
lambda = input(defval = 1000, type = input.float, title = "Smoothing Factor (Lambda)", minval = 1)
leng = input(defval = 100, type = input.integer, title = "Filter Length", minval = 1)
src = ohlc4
atr = atr(14)

///////////Construct Arrays///////////////
a = array.new_float(leng, 0.0)
b = array.new_float(leng, 0.0)
c = array.new_float(leng, 0.0)
d = array.new_float(leng, 0.0)
e = array.new_float(leng, 0.0)
f = array.new_float(leng, 0.0)

/////////Initialize the Values///////////

ll1 = leng-1
ll2 = leng-2

for i = 0 to ll1
    array.set(a,i, lambda*(-4))
    array.set(b,i, src[i])
    array.set(c,i, lambda*(-4))
    array.set(d,i, lambda*6 + 1)
    array.set(e,i, lambda)
    array.set(f,i, lambda)

array.set(d, 0,  lambda + 1.0)
array.set(d, ll1, lambda + 1.0)
array.set(d, 1,  lambda * 5.0 + 1.0)
array.set(d, ll2, lambda * 5.0 + 1.0)

array.set(c, 0 , lambda * (-2.0))
array.set(c, ll2, lambda * (-2.0))

array.set(a, 0 , lambda * (-2.0))
array.set(a, ll2, lambda * (-2.0))

//////////////Solve the optimization issue/////////////////////
float r = array.get(a, 0)
float s = array.get(a, 1)
float t = array.get(e, 0)
float xmult = 0.0

for i = 1 to ll2
    xmult := r / array.get(d, i-1)
    array.set(d, i, array.get(d, i) - xmult * array.get(c, i-1))
    array.set(c, i, array.get(c, i) - xmult * array.get(f, i-1))
    array.set(b, i, array.get(b, i) - xmult * array.get(b, i-1))

    xmult := t / array.get(d, i-1)
    r     := s - xmult*array.get(c, i-1)
    array.set(d, i+1, array.get(d, i+1) - xmult * array.get(f, i-1))
    array.set(b, i+1, array.get(b, i+1) - xmult * array.get(b, i-1))

    s     := array.get(a, i+1)
    t     := array.get(e, i)

xmult := r / array.get(d, ll2)
array.set(d, ll1, array.get(d, ll1) - xmult * array.get(c, ll2))

x = array.new_float(leng, 0)
array.set(x, ll1, (array.get(b, ll1) - xmult * array.get(b, ll2)) / array.get(d, ll1))
array.set(x, ll2, (array.get(b, ll2) - array.get(c, ll2) * array.get(x, ll1)) / array.get(d, ll2))

for j = 0 to leng-3
    i = leng-3 - j
    array.set(x, i, (array.get(b,i) - array.get(f,i)*array.get(x,i+2) - array.get(c,i)*array.get(x,i+1)) / array.get(d, i))


//////////////Construct the output///////////////////
HP = array.get(x,0)

///////////////Custom VWAP////////////////////////
TimeFrame = input('1', type=input.resolution)
start = security(syminfo.tickerid, TimeFrame, time)

//------------------------------------------------
newSession = iff(change(start), 1, 0)
//------------------------------------------------
vwapsum = 0.0
vwapsum := iff(newSession, HP*volume, vwapsum[1]+HP*volume)
volumesum = 0.0
volumesum := iff(newSession, volume, volumesum[1]+volume)
v2sum = 0.0
v2sum := iff(newSession, volume*HP*HP, v2sum[1]+volume*HP*HP)
myvwap = vwapsum/volumesum
dev = sqrt(max(v2sum/volumesum - myvwap*myvwap, 0))
Coloring=close>myvwap?color.new(#81c784, 62):color.new(#c2185b, 38)
av=myvwap
showBcol = input(true, type=input.bool, title="Show barcolors")


///////////////Entry & Exit///////////////////

// Custom function to convert pips into whole numbers
toWhole(number) =>
    return = atr < 1.0 ? (number / syminfo.mintick) / (10 / syminfo.pointvalue) : number
    return := atr >= 1.0 and atr < 100.0 and syminfo.currency == "JPY" ? return * 100 : return

// Custom function to convert whole numbers back into pips
toPips(number) =>
    return = atr >= 1.0 ? number : (number * syminfo.mintick) * (10 / syminfo.pointvalue)
    return := atr >= 1.0 and atr < 100.0 and syminfo.currency == "JPY" ? return / 100 : return

// Custom function to truncate (cut) excess decimal places
truncate(_number, _decimalPlaces) =>
    _factor = pow(10, _decimalPlaces)
    int(_number * _factor) / _factor


///////////////Conditional Strategy Logic//////////////
Long = crossover(av, ohlc4)
Sell = crossunder(av, ohlc4)

// Check if we have confirmation for our setup
validLong = Long and strategy.position_size == 0 and inDateRange and barstate.isconfirmed
validShort = Sell and strategy.position_size == 0 and inDateRange and barstate.isconfirmed


// Calculate our stop distance & size for the current bar
stopSize = atr * stopMultiplier
longStopPrice = low < low[1] ? low - stopSize : low[1] - stopSize
longStopDistance = close - longStopPrice
longTargetPrice = close + (longStopDistance * rr)


// Save trade stop & target & position size if a valid setup is detected
var t_entry = 0.0
var t_stop = 0.0
var t_target = 0.0
var t_direction = 0

// Detect valid long setups & trigger alert
if validLong
    t_entry := close
    t_stop := longStopPrice
    t_target := longTargetPrice
    t_direction := 1
    strategy.entry(id="Long", long=strategy.long, when=validLong, comment="(SL=" + tostring(truncate(toWhole(longStopDistance),2)) + " pips)")
    // Fire alerts
    alert(message="Long Detected", freq=alert.freq_once_per_bar_close)

// Check if price has hit long stop loss or target
if t_direction == 1 and (low <= t_stop or high >= t_target)
    t_direction := 0

// Check if price has hit short stop loss or target
if t_direction == -1 and (high >= t_stop or low <= t_target)
    t_direction := 0


// Exit trades whenever our stop or target is hit
strategy.exit(id="Long Exit", from_entry="Long", limit=t_target, stop=t_stop, when=strategy.position_size > 0)

// Draw trade data
plot(strategy.position_size != 0 or validLong? t_stop : na, title="Trade Stop Price", color=color.red, style=plot.style_linebr)
plot(strategy.position_size != 0 or validLong? t_target : na, title="Trade Target Price", color=color.green, style=plot.style_linebr)

/////////////////////Plotting//////////////////////////

A=plot(av, color=Coloring, title="HP VWAP")

barcolor(showBcol?Coloring:na)

fill(A, plot(ohlc4), Coloring)

// Draw price action setup arrows
plotshape(validLong ? 1 : na, style=shape.triangleup, location=location.belowbar, color=color.green, title="Bullish Setup")

// // --- BEGIN TESTER CODE --- //
// // Declare performance tracking variables
// var balance = startBalance
// var drawdown = 0.0
// var maxDrawdown = 0.0
// var maxBalance = 0.0
// var totalPips = 0.0
// var totalWins = 0
// var totalLoss = 0

// // Detect winning trades
// if strategy.wintrades != strategy.wintrades[1]
//     balance := balance + ((riskPerTrade / 100) * balance) * rr
//     totalPips := totalPips + abs(t_entry - t_target)
//     totalWins := totalWins + 1
//     if balance > maxBalance
//         maxBalance := balance

// // Detect losing trades
// if strategy.losstrades != strategy.losstrades[1]
//     balance := balance - ((riskPerTrade / 100) * balance)
//     totalPips := totalPips - abs(t_entry - t_stop)
//     totalLoss := totalLoss + 1
//     // Update drawdown
//     drawdown := (balance / maxBalance) - 1
//     if drawdown < maxDrawdown
//         maxDrawdown := drawdown

// // Prepare stats table
// var table testTable = table.new(position.top_right, 5, 2, border_width=1)
// f_fillCell(_table, _column, _row, _title, _value, _bgcolor, _txtcolor) =>
//     _cellText = _title + "\n" + _value
//     table.cell(_table, _column, _row, _cellText, bgcolor=_bgcolor, text_color=_txtcolor)

// // Draw stats table
// var bgcolor = color.new(color.black,0)
// if drawTester
//     if barstate.islastconfirmedhistory
//         // Update table
//         dollarReturn = balance - startBalance
//         f_fillCell(testTable, 0, 0, "Total Trades:", tostring(strategy.closedtrades), bgcolor, color.white)
//         f_fillCell(testTable, 0, 1, "Win Rate:", tostring(truncate((strategy.wintrades/strategy.closedtrades)*100,2)) + "%", bgcolor, color.white)
//         f_fillCell(testTable, 1, 0, "Starting:", "$" + tostring(startBalance), bgcolor, color.white)
//         f_fillCell(testTable, 1, 1, "Ending:", "$" + tostring(truncate(balance,2)), bgcolor, color.white)
//         f_fillCell(testTable, 2, 0, "Return:", "$" + tostring(truncate(dollarReturn,2)), dollarReturn > 0 ? color.green : color.red, color.white)
//         f_fillCell(testTable, 2, 1, "Pips:", (totalPips > 0 ? "+" : "") + tostring(truncate(toWhole(totalPips),2)), bgcolor, color.white)
//         f_fillCell(testTable, 3, 0, "Return:", (dollarReturn > 0 ? "+" : "") + tostring(truncate((dollarReturn / startBalance)*100,2)) + "%", dollarReturn > 0 ? color.green : color.red, color.white)
//         f_fillCell(testTable, 3, 1, "Max DD:", tostring(truncate(maxDrawdown*100,2)) + "%", color.red, color.white)
// // --- END TESTER CODE --- //Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/LPB-Microcycles-Adaptive-Oscillation-Contour-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h
- Quantitative Breakout Strategy First Hour ATR Stop Loss with EMA Slope OptimizationPine Script · Breakout · 1h
- Dynamic Buying Selling Volume Breakout StrategyPine Script · Breakout · 1d
- Multi Timeframe VWAP and EMA Breakout Trading StrategyPine Script · Breakout · 2h
- Dynamic Moving Averages and Keltner Channel Trading StrategyPine Script · Breakout · 1h
- Dynamic Multi indicator Quantitative Trading StrategyPine Script · Breakout · 1d