Strategy vault / Trend following
MACD Based Al Brooks Price Action Trend Following Strategy
This strategy is a trend-following trading system based on Al Brooks' price action theory and the MACD indicator. It identifies market trends by combining Simple Moving Average (SMA) and MACD indicators, executing…
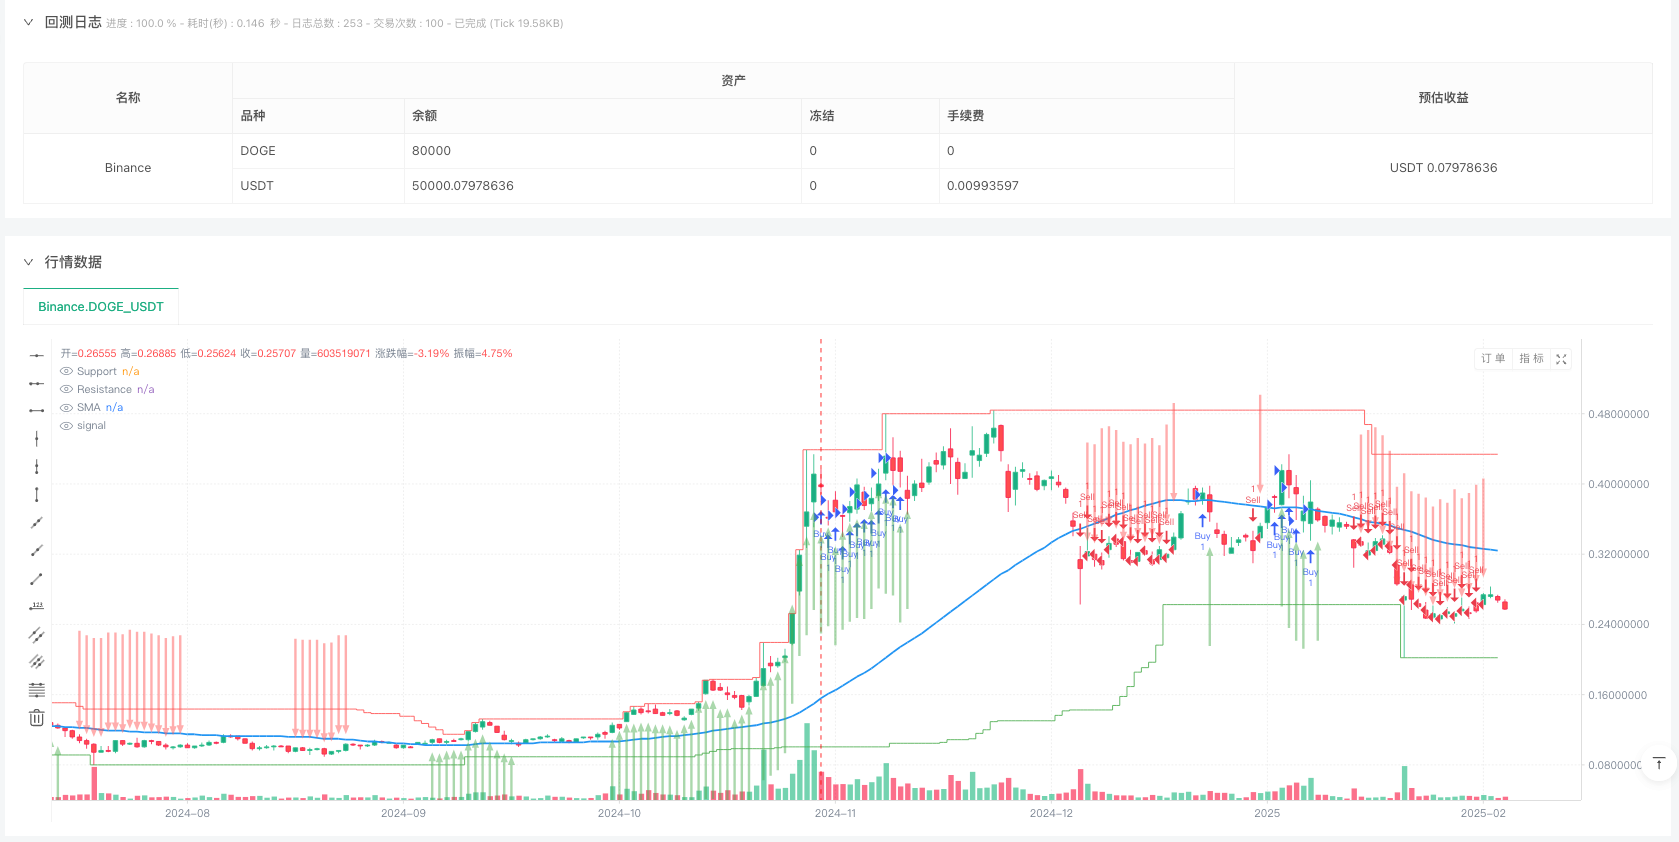
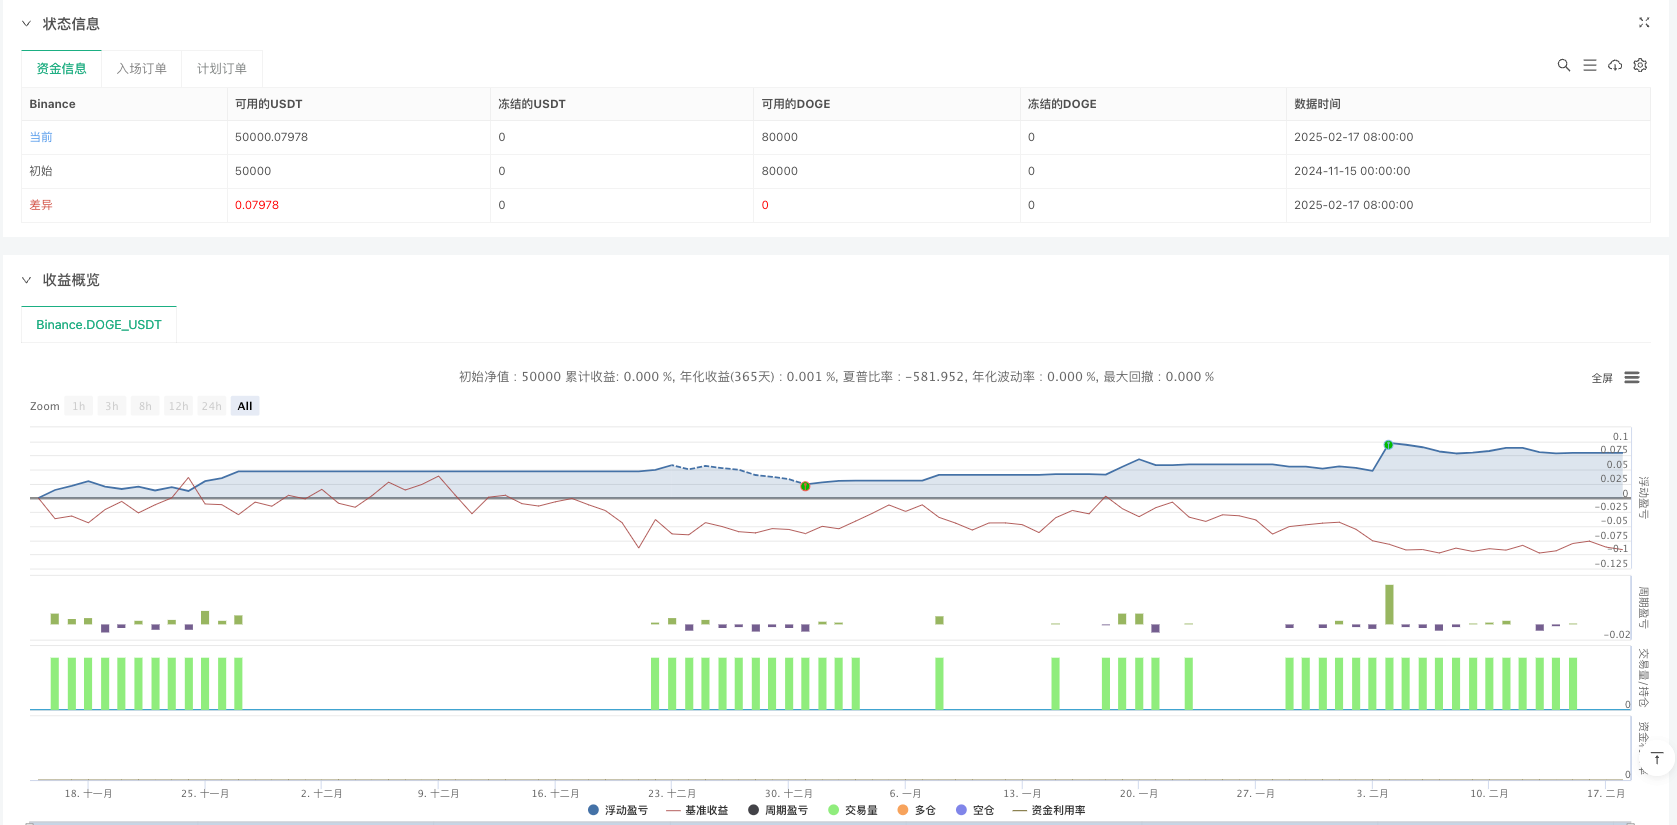
Overview
This strategy is a trend-following trading system based on Al Brooks' price action theory and the MACD indicator. It identifies market trends by combining Simple Moving Average (SMA) and MACD indicators, executing trades at appropriate times. The strategy employs a fixed risk-reward ratio to manage stop-loss and take-profit levels for each trade, ensuring effective risk control.
Strategy Principles
The core logic includes the following key elements:
- Trend Identification: Uses Simple Moving Average (SMA) as a benchmark for trend determination, identifying uptrends when price is above SMA and downtrends when below.
- Entry Signals:
- Long Entry: Price above SMA, MACD line above 0 and crosses above signal line
- Short Entry: Price below SMA, MACD line below 0 and crosses below signal line
- Risk Management:
- Uses fixed percentage as stop-loss buffer
- Calculates take-profit levels based on preset risk-reward ratio
- Exit Mechanism: Automatically closes positions when buy or sell signals disappear
Strategy Advantages
- Trend Following Reliability: Combines price action and technical indicators for improved trend accuracy
- Scientific Risk Control: Implements fixed risk-reward ratio for trade management
- Comprehensive Signal Confirmation: Reduces false signals through multiple condition verification
- High Automation Level: Includes complete entry, exit, and risk management mechanisms
- Excellent Visualization: Provides clear support and resistance level display
Strategy Risks
- Trend Reversal Risk: May generate consecutive false signals at trend turning points
- Lag Risk: Both moving average and MACD have inherent lag
- Parameter Sensitivity: Strategy performance is sensitive to parameter settings
- Market Environment Dependency: May generate more losing trades in ranging markets
Strategy Optimization Directions
- Signal Filtering: Add volume or volatility indicators to filter signals
- Dynamic Parameters: Convert fixed risk-reward ratio to dynamic parameters based on market volatility
- Time Filtering: Add trading time window restrictions to avoid unfavorable trading periods
- Market Sentiment Integration: Incorporate market sentiment indicators to assist in trend strength assessment
Summary
This is a complete trading system that combines classical price action theory with technical indicators. The strategy achieves relatively stable trading performance through strict signal confirmation mechanisms and risk management methods. While there are some inherent risks, the suggested optimization directions can further enhance the strategy's stability and profitability.
Source Pine Script
/*backtest
start: 2024-11-15 00:00:00
end: 2025-02-18 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Binance","currency":"DOGE_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Abdulhossein

//@version=6
strategy(title="Al Brooks Price Action with MACD Signals", shorttitle="Al Brooks PA + MACD", overlay=true)

// Inputs
length = input.int(52, title="Moving Average Length", minval=1)
riskRewardRatio = input.float(2.0, title="Risk/Reward Ratio", minval=1.0)
stopLossBuffer = input.float(0.01, title="Stop Loss Buffer (in %)", minval=0.001)
candleType = input.string("Close", title="Candle Type", options=["Close", "Open"])

// Indicators
sma = ta.sma(close, length)
[macdLine, signalLine, _] = ta.macd(close, 12, 26, 9)
price = candleType == "Close" ? close : open

// Trend Conditions
uptrend = price > sma
downtrend = price < sma

// Buy/Sell Signals
buySignal = price > sma and macdLine > 0 and macdLine > signalLine
sellSignal = price < sma and macdLine < 0 and macdLine < signalLine

// Trade Execution
if (buySignal)
    longStopLoss = close * (1 - stopLossBuffer)
    longTakeProfit = close + (close - longStopLoss) * riskRewardRatio
    strategy.entry("Buy", strategy.long)
    strategy.exit("Take Profit", "Buy", limit=longTakeProfit, stop=longStopLoss)

if (sellSignal)
    shortStopLoss = close * (1 + stopLossBuffer)
    shortTakeProfit = close - (shortStopLoss - close) * riskRewardRatio
    strategy.entry("Sell", strategy.short)
    strategy.exit("Take Profit", "Sell", limit=shortTakeProfit, stop=shortStopLoss)

// Plot Signals
plotarrow(buySignal[2] ? 1 : na, colorup=color.new(color.green, 50), title="Buy Signal Arrow", offset=-1)
plotarrow(sellSignal[2] ? -1 : na, colordown=color.new(color.red, 50), title="Sell Signal Arrow", offset=-1)

// Close Positions
if (not buySignal and not sellSignal)
    strategy.close("Sell")
    strategy.close("Buy")

// Support and Resistance
support = ta.lowest(low, length)
resistance = ta.highest(high, length)
plot(support, title="Support", color=color.green, linewidth=1, style=plot.style_stepline)
plot(resistance, title="Resistance", color=color.red, linewidth=1, style=plot.style_stepline)
plot(sma, title="SMA", color=color.blue, linewidth=2)

// Alerts
alertcondition(buySignal[2], title="Buy Alert", message="Buy Signal Triggered")
alertcondition(sellSignal[2], title="Sell Alert", message="Sell Signal Triggered")Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MACD-Based-Al-Brooks-Price-Action-Trend-Following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Going with the Trend Moving Average Crossover StrategyPine Script · Trend following · 1d
- Concise Dynamic Trend StrategyPine Script · Trend following · 2h
- Price Drop Buy Strategy in Downtrend with Stop LossPine Script · Trend following · 30m
- SMA Based Dual Thrust StrategyPine Script · Trend following · 10m