Strategy vault / Mean reversion
MACD Double Optimization Trading Strategy
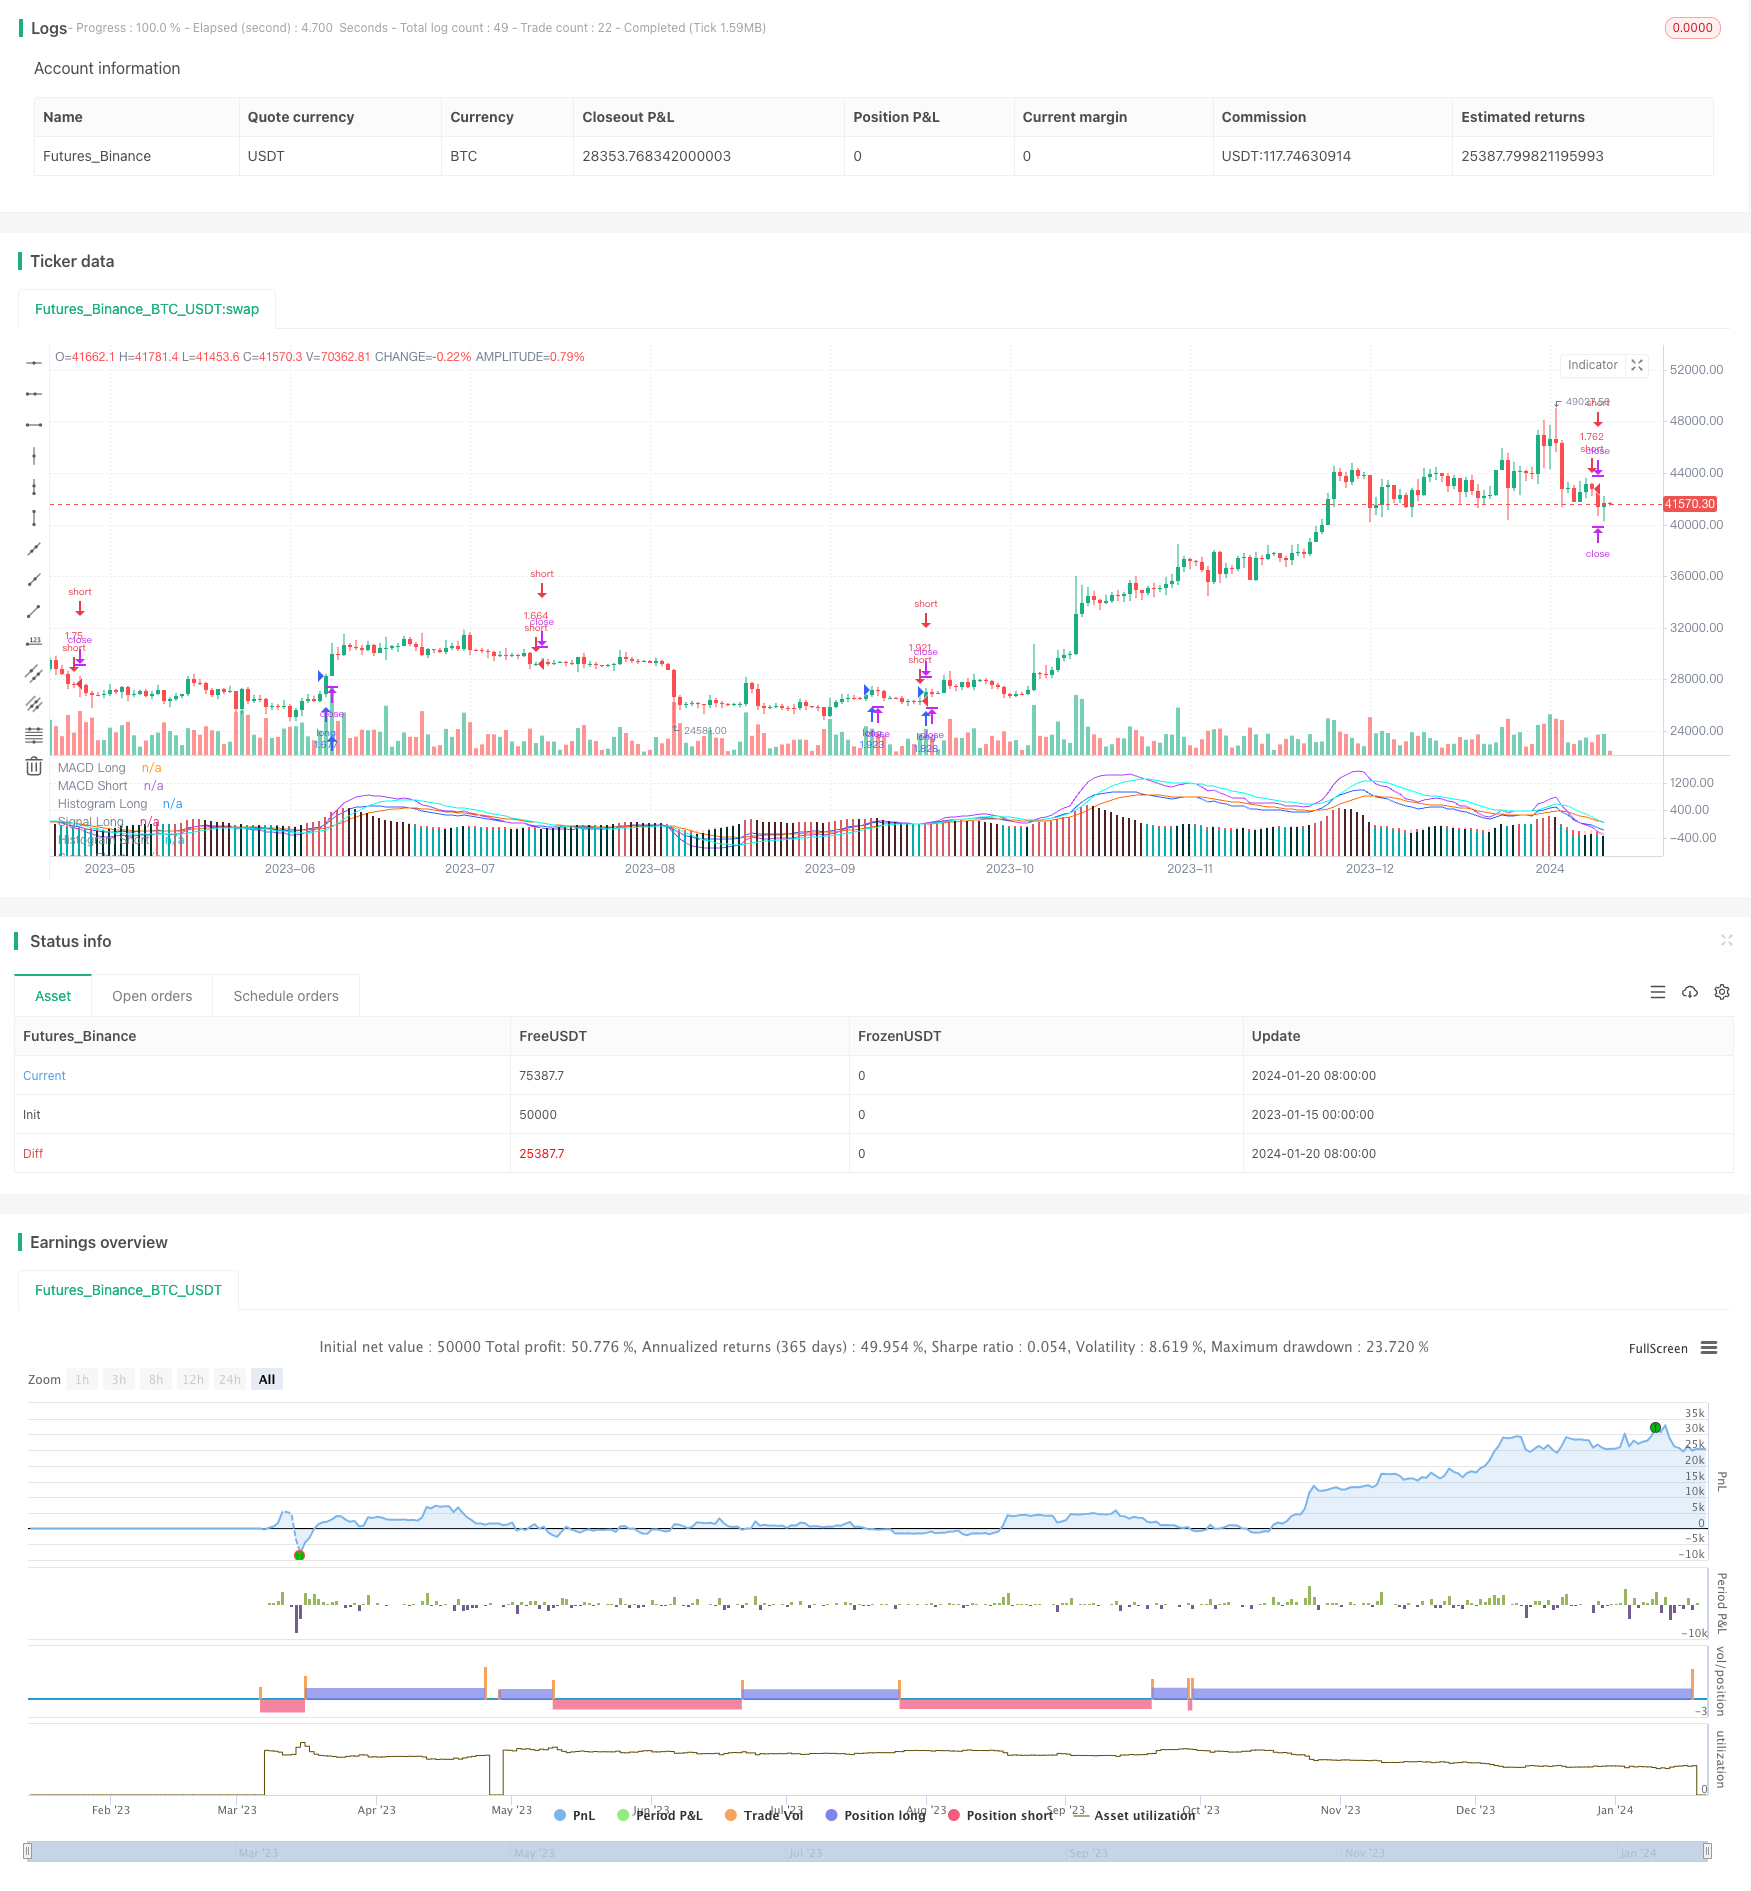
This strategy uses the MACD indicator and moving average cross principles to construct trading signals. Its advantage is that it can optimize the parameters of MACD separately for long and short directions, so that…
II. Strategy Overview
This strategy uses the MACD indicator and moving average cross principles to construct trading signals. Its advantage is that it can optimize the parameters of MACD separately for long and short directions, so that the parameters can be optimally configured for different market directions.
III. Strategy Principle
Calculate the MACD indicator separately for long and short directions. One set of parameters is used for long, and another set of parameters is used for short, which can be freely configured.
Judge the trading signals generated by the crossover of the MACD line and the Signal line. Look for bullish crossover for long, and bearish crossover for short.
You can configure whether the Signal line also needs to cross to trigger the signal, so as to avoid false signals.
After entering long or short position, close the position when a reverse crossover occurs.
IV. Advantages of the Strategy
Two-way parameter optimization: parameters for long and short can be freely optimized to be optimally configured for market directions separately.
Configurable signal smoothing: The Signal parameter can control the smoothness of the signal line to filter out false signals.
Configurable signal filtering: Can be configured whether the Signal line crossover is required to trigger to avoid false signals.
Fine-tuned position control: Long or short alone can be enabled separately, or long and short can be done at the same time.
V. Risks of the Strategy
MACD lag: MACD itself has some lag which may miss fast reversals.
Risk of switching between long and short: Frequent position switching may occur when the market changes rapidly.
Parameter risk: Improper parameter configurations may fail to capture market characteristics.
Lack of stop loss protection: Reasonable stop loss should be set to control single loss.
Methods to manage risks:
Combine with other indicators to judge the big picture and avoid chasing highs and selling lows.
Set signal delay and smoothing parameters to reduce error signals.
Repeatedly test and optimize parameters to match the rhythm of the market in different cycles.
Set up stop loss and take profit mechanism to control single loss.
VI. Directions for Optimization
Some ways this strategy can be further optimized:
Test different combinations of fast line and slow line length parameters to find the optimal parameters for market conditions in different cycles.
Test different Signal line parameters. Smoother signal lines can filter out more noise.
Test the difference between turning on and off the Signal line crossover filter to find the optimal balance.
Set the optimal stop loss and take profit ratio based on backtest results.
Try only long or only short to see if the strategy effect can be maximized.
VII. Summary
By configuring long and short parameters separately, this MACD Double Optimization Trading Strategy realizes optimization tailored to different market directions, and allows free adjustment of the participation direction. At the same time, signal filtering mechanisms are introduced to avoid erroneous signals. Through parameter optimization and risk management measures, the strategy effect can be further improved.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_bool_1 | true | (?inputs long)Allow Long |
| v_input_int_1 | 13 | Fast Length Long |
| v_input_int_2 | 19 | Slow Length Long |
| v_input_source_1_close | 0 | Source Long: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_int_3 | 9 | Signal Smoothing Long |
| v_input_string_1 | 0 | Oscillator MA Type Long: EMA | SMA |
| v_input_string_2 | 0 | Signal Line MA Type Long: EMA | SMA |
| v_input_int_4 | false | Cross Point Long |
| v_input_int_5 | false | MacD Cross Delay Long |
| v_input_bool_2 | false | Signal Must Also Cross Long |
| v_input_int_6 | false | Signal Cross Delay Long |
| v_input_bool_3 | true | (?inputs short)Allow Short |
| v_input_int_7 | 11 | Fast Length Short |
| v_input_int_8 | 20 | Slow Length Short |
| v_input_source_2_close | 0 | Source Short: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_int_9 | 9 | Signal Smoothing Short |
| v_input_string_3 | 0 | Oscillator MA Type Short: EMA | SMA |
| v_input_string_4 | 0 | Signal Line MA Type Short: EMA | SMA |
| v_input_int_10 | false | Cross Point Short |
| v_input_int_11 | true | MacD Cross Delay Short |
| v_input_bool_4 | false | Signal Must Also Cross Short |
| v_input_int_12 | false | Signal Cross Delay Short |
| v_input_bool_5 | false | (?Stop/Profit Long)Use Stop Loss Long |
| v_input_float_1 | true | Stop Loss % Long |
| v_input_bool_6 | false | Use Take Profit Long |
| v_input_float_2 | true | Take Profit % Long |
| v_input_bool_7 | true | (?Stop/Profit Short)Use Stop Loss Short |
| v_input_float_3 | 21 | Stop Loss % Short |
| v_input_bool_8 | true | Use Take Profit Short |
| v_input_float_4 | 20 | Take Profit % Short |
| v_input_color_1 | #2962FF | (?Color Settings)MACD Line Long |
| v_input_color_2 | #FF6D00 | Signal Line Long |
| v_input_color_7 | #B03DFF | MACD Line Short |
| v_input_color_8 | #00FFE8 | Signal Line Short |
| v_input_color_3 | #26A69A | (?Histogram Color Settings)Grow Above Long |
| v_input_color_4 | #B2DFDB | Fall Above Long |
| v_input_color_5 | #FFCDD2 | Grow Below Long |
| v_input_color_6 | #FF5252 | Fall Below Long |
| v_input_color_9 | #D95965 | Grow Above Short |
| v_input_color_10 | #4D2024 | Fall Above Short |
| v_input_color_11 | #00322D | Grow Below Short |
| v_input_color_12 | #00ADAD | Fall Below Short |
Source Pine Script
/*backtest
start: 2023-01-15 00:00:00
end: 2024-01-21 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Gentleman-Goat & TradingTools.Software/Optimizer
strategy(title="MACD Short/Long Strategy for TradingView Input Optimizer", shorttitle="MACD Short/Long TVIO", initial_capital=1000, default_qty_value=100, default_qty_type=strategy.percent_of_equity)

// Get Inputs Long
allow_long                  = input.bool(title="Allow Long", defval=true, group="inputs long")
fast_length_long            = input.int(title="Fast Length Long", defval=13, group="inputs long")
slow_length_long            = input.int(title="Slow Length Long", defval=19, group="inputs long")
src_long                    = input.source(title="Source Long", defval=close, group="inputs long")
signal_length_long          = input.int(title="Signal Smoothing Long", minval = 1, maxval = 50, defval = 9, group="inputs long")
sma_source_long             = input.string(title="Oscillator MA Type Long", defval="EMA", options=["SMA", "EMA"], group="inputs long")
sma_signal_long             = input.string(title="Signal Line MA Type Long", defval="EMA", options=["SMA", "EMA"], group="inputs long")
cross_point_long            = input.int(title="Cross Point Long", defval=0, group="inputs long")
cross_delay_macd_long       = input.int(title="MacD Cross Delay Long", defval=0, group="inputs long")
signal_must_cross_long      = input.bool(title="Signal Must Also Cross Long", defval=false, group="inputs long")
cross_delay_signal_long     = input.int(title="Signal Cross Delay Long", defval=0, group="inputs long")

//Get Inputs Short
allow_short                 = input.bool(title="Allow Short", defval=true, group="inputs short")
fast_length_short           = input.int(title="Fast Length Short", defval=11, group="inputs short")
slow_length_short           = input.int(title="Slow Length Short", defval=20, group="inputs short")
src_short                   = input.source(title="Source Short", defval=close, group="inputs short")
signal_length_short         = input.int(title="Signal Smoothing Short", minval = 1, maxval = 50, defval = 9, group="inputs short")
sma_source_short            = input.string(title="Oscillator MA Type Short", defval="EMA", options=["SMA", "EMA"], group="inputs short")
sma_signal_short            = input.string(title="Signal Line MA Type Short", defval="EMA", options=["SMA", "EMA"], group="inputs short")
cross_point_short           = input.int(title="Cross Point Short", defval=0, group="inputs short")
cross_delay_macd_short      = input.int(title="MacD Cross Delay Short", defval=1, group="inputs short")
signal_must_cross_short     = input.bool(title="Signal Must Also Cross Short", defval=false, group="inputs short")
cross_delay_signal_short    = input.int(title="Signal Cross Delay Short", defval=0, group="inputs short")

use_stop_loss_long          = input.bool(defval=false,title="Use Stop Loss Long", group="Stop/Profit Long")
stop_loss_long_percentage   = input.float(defval=1,title="Stop Loss % Long",minval=0.0,step=0.1, group="Stop/Profit Long") * .01
use_take_profit_long        = input.bool(defval=false,title="Use Take Profit Long", group="Stop/Profit Long")
take_profit_long_percentage = input.float(defval=1,title="Take Profit % Long",minval=0.0,step=0.1, group="Stop/Profit Long") * .01
use_stop_loss_short         = input.bool(defval=true,title="Use Stop Loss Short", group="Stop/Profit Short")
stop_loss_short_percentage  = input.float(defval=21,title="Stop Loss % Short",minval=0.0,step=0.1, group="Stop/Profit Short") * .01
use_take_profit_short       = input.bool(defval=true,title="Use Take Profit Short", group="Stop/Profit Short")
take_profit_short_percentage= input.float(defval=20,title="Take Profit % Short",minval=0.0,step=0.1, group="Stop/Profit Short") * .01
//------------------------------------------------------------------------------

// Plot colors Long
col_macd_long        = input.color(#2962FF, "MACD Line Long", group="Color Settings", inline="MACD")
col_signal_long      = input.color(#FF6D00, "Signal Line Long", group="Color Settings", inline="Signal")
col_grow_above_long  = input.color(#26A69A, "Grow Above Long", group="Histogram Color Settings", inline="Above Long")
col_fall_above_long  = input.color(#B2DFDB, "Fall Above Long", group="Histogram Color Settings", inline="Above Long")
col_grow_below_long  = input.color(#FFCDD2, "Grow Below Long", group="Histogram Color Settings", inline="Below Long")
col_fall_below_long  = input.color(#FF5252, "Fall Below Long", group="Histogram Color Settings", inline="Below Long")

// Plot colors Short
col_macd_short        = input.color(#B03DFF, "MACD Line Short", group="Color Settings", inline="MACD")
col_signal_short      = input.color(#00FFE8, "Signal Line Short", group="Color Settings", inline="Signal")
col_grow_above_short  = input.color(#D95965, "Grow Above Short", group="Histogram Color Settings", inline="Above Short")
col_fall_above_short  = input.color(#4D2024, "Fall Above Short", group="Histogram Color Settings", inline="Above Short")
col_grow_below_short  = input.color(#00322D, "Grow Below Short", group="Histogram Color Settings", inline="Below Short")
col_fall_below_short  = input.color(#00ADAD, "Fall Below Short", group="Histogram Color Settings", inline="Below Short")

// Calculate Long
fast_ma_long = sma_source_long == "SMA" ? ta.sma(src_long, fast_length_long) : ta.ema(src_long, fast_length_long)
slow_ma_long = sma_source_long == "SMA" ? ta.sma(src_long, slow_length_long) : ta.ema(src_long, slow_length_long)
macd_long    = fast_ma_long - slow_ma_long
signal_long  = sma_signal_long == "SMA" ? ta.sma(macd_long, signal_length_long) : ta.ema(macd_long, signal_length_long)
hist_long    = macd_long - signal_long

// Calculate Short
fast_ma_short = sma_source_short == "SMA" ? ta.sma(src_short, fast_length_short) : ta.ema(src_short, fast_length_short)
slow_ma_short = sma_source_short == "SMA" ? ta.sma(src_short, slow_length_short) : ta.ema(src_short, slow_length_short)
macd_short    = fast_ma_short - slow_ma_short
signal_short  = sma_signal_short == "SMA" ? ta.sma(macd_short, signal_length_short) : ta.ema(macd_short, signal_length_short)
hist_short    = macd_short - signal_short

//Plot Long
plot(hist_long, title="Histogram Long", style=plot.style_columns, color=(hist_long>=0 ? (hist_long[1] < hist_long ? col_grow_above_long : col_fall_above_long) : (hist_long[1] < hist_long ? col_grow_below_long : col_fall_below_long)))
plot(macd_long, title="MACD Long", color=col_macd_long)
plot(signal_long, title="Signal Long", color=col_signal_long)

//Plot Short
plot(hist_short, title="Histogram Short", style=plot.style_columns, color=(hist_short>=0 ? (hist_short[1] < hist_short ? col_grow_above_short : col_fall_above_short) : (hist_short[1] < hist_short ? col_grow_below_short : col_fall_below_short)))
plot(macd_short, title="MACD Short", color=col_macd_short)
plot(signal_short, title="Signal Short", color=col_signal_short)

var detectedLongCrossOver = false
var detectedShortCrossUnder = false

if(ta.crossunder(macd_short,cross_point_short))
    detectedShortCrossUnder := true
if(ta.crossover(macd_short,cross_point_short))
    detectedShortCrossUnder := false

if(ta.crossover(macd_long,cross_point_long))
    detectedLongCrossOver := true
if(ta.crossunder(macd_long,cross_point_long))
    detectedLongCrossOver := false

crossover_signal_long = ta.crossover(signal_long,cross_point_long)
crossunder_signal_long = ta.crossunder(signal_long,cross_point_long)

crossunder_signal_short = ta.crossunder(signal_short,cross_point_short)
crossover_signal_short = ta.crossover(signal_short,cross_point_short)

crossover_macd_long = ta.crossover(macd_long,cross_point_long)
crossunder_macd_long = ta.crossunder(macd_long,cross_point_long)

crossunder_macd_short = ta.crossunder(macd_short,cross_point_short)
crossover_macd_short = ta.crossover(macd_short,cross_point_short)

inEntry = false
//Strategy Entries
if (strategy.equity > 0) //This is required for the input optimizer to work since it will fail if the strategy fails to succeed by not having enough equity.

    if (strategy.position_size <= 0 and allow_long==true and inEntry==false)
        if(signal_must_cross_long==true)
            longSignalCondition = detectedLongCrossOver==true and crossover_signal_long[cross_delay_signal_long]
            strategy.entry(id="long", direction=strategy.long, when=longSignalCondition)
            if(longSignalCondition)
                inEntry:=true
        else
            longMacDCondition = crossover_macd_long[cross_delay_macd_long]
            strategy.entry(id="long", direction=strategy.long, when=longMacDCondition)
            if(longMacDCondition)
                inEntry:=true
    if (strategy.position_size >= 0 and allow_short==true and inEntry==false)
        if(signal_must_cross_short==true)
            shortSignalCondition = detectedShortCrossUnder and crossunder_signal_short[cross_delay_signal_short]
            strategy.entry(id="short", direction=strategy.short, when=shortSignalCondition)
            if(shortSignalCondition)
                inEntry:=true
        else
            shortMacDCondition = crossunder_macd_short[cross_delay_macd_short]
            strategy.entry(id="short", direction=strategy.short, when=shortMacDCondition)
            if(shortMacDCondition)
                inEntry:=true
    if(strategy.position_size > 0 and allow_long==true and allow_short==false)
        if(signal_must_cross_long==true)
            strategy.close(id="long", when=detectedLongCrossOver==false and crossunder_signal_long)
        else
            strategy.close(id="long", when=crossunder_macd_long)
    if(strategy.position_size < 0 and allow_short==true and allow_long==false)
        if(signal_must_cross_short==true)
            strategy.close(id="short", when=detectedShortCrossUnder==false and crossover_signal_short)
        else
            strategy.close(id="short", when=crossover_macd_short)

stop_loss_value_long    = strategy.position_avg_price*(1 - stop_loss_long_percentage)
take_profit_value_long  = strategy.position_avg_price*(1 + take_profit_long_percentage)
stop_loss_value_short   = strategy.position_avg_price*(1 + stop_loss_short_percentage)
take_profit_value_short = strategy.position_avg_price*(1 - take_profit_short_percentage)

if(strategy.position_size>0) //Long positions only
    strategy.exit(id="TP/SL Long",from_entry="long", limit=use_take_profit_long ? take_profit_value_long : na, stop=use_stop_loss_long ? stop_loss_value_long : na)
if(strategy.position_size<0) //Short positions only
strategy.exit(id="TP/SL Short",from_entry="short", limit=use_take_profit_short ? take_profit_value_short : na, stop=use_stop_loss_short ? stop_loss_value_short : na)Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MACD-Double-Optimization-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- MACD Cross Period Trading StrategyPine Script · Mean reversion · 1d
- MACD Long Reversal StrategyPine Script · Mean reversion · 1d