MACD Momentum with MA Strategy
The Trend Hunter - MACD Momentum with MA strategy is an exquisite trading tool designed for traders seeking to capitalize on trending markets. Built on the robust combination of Average True Range (ATR), Simple…
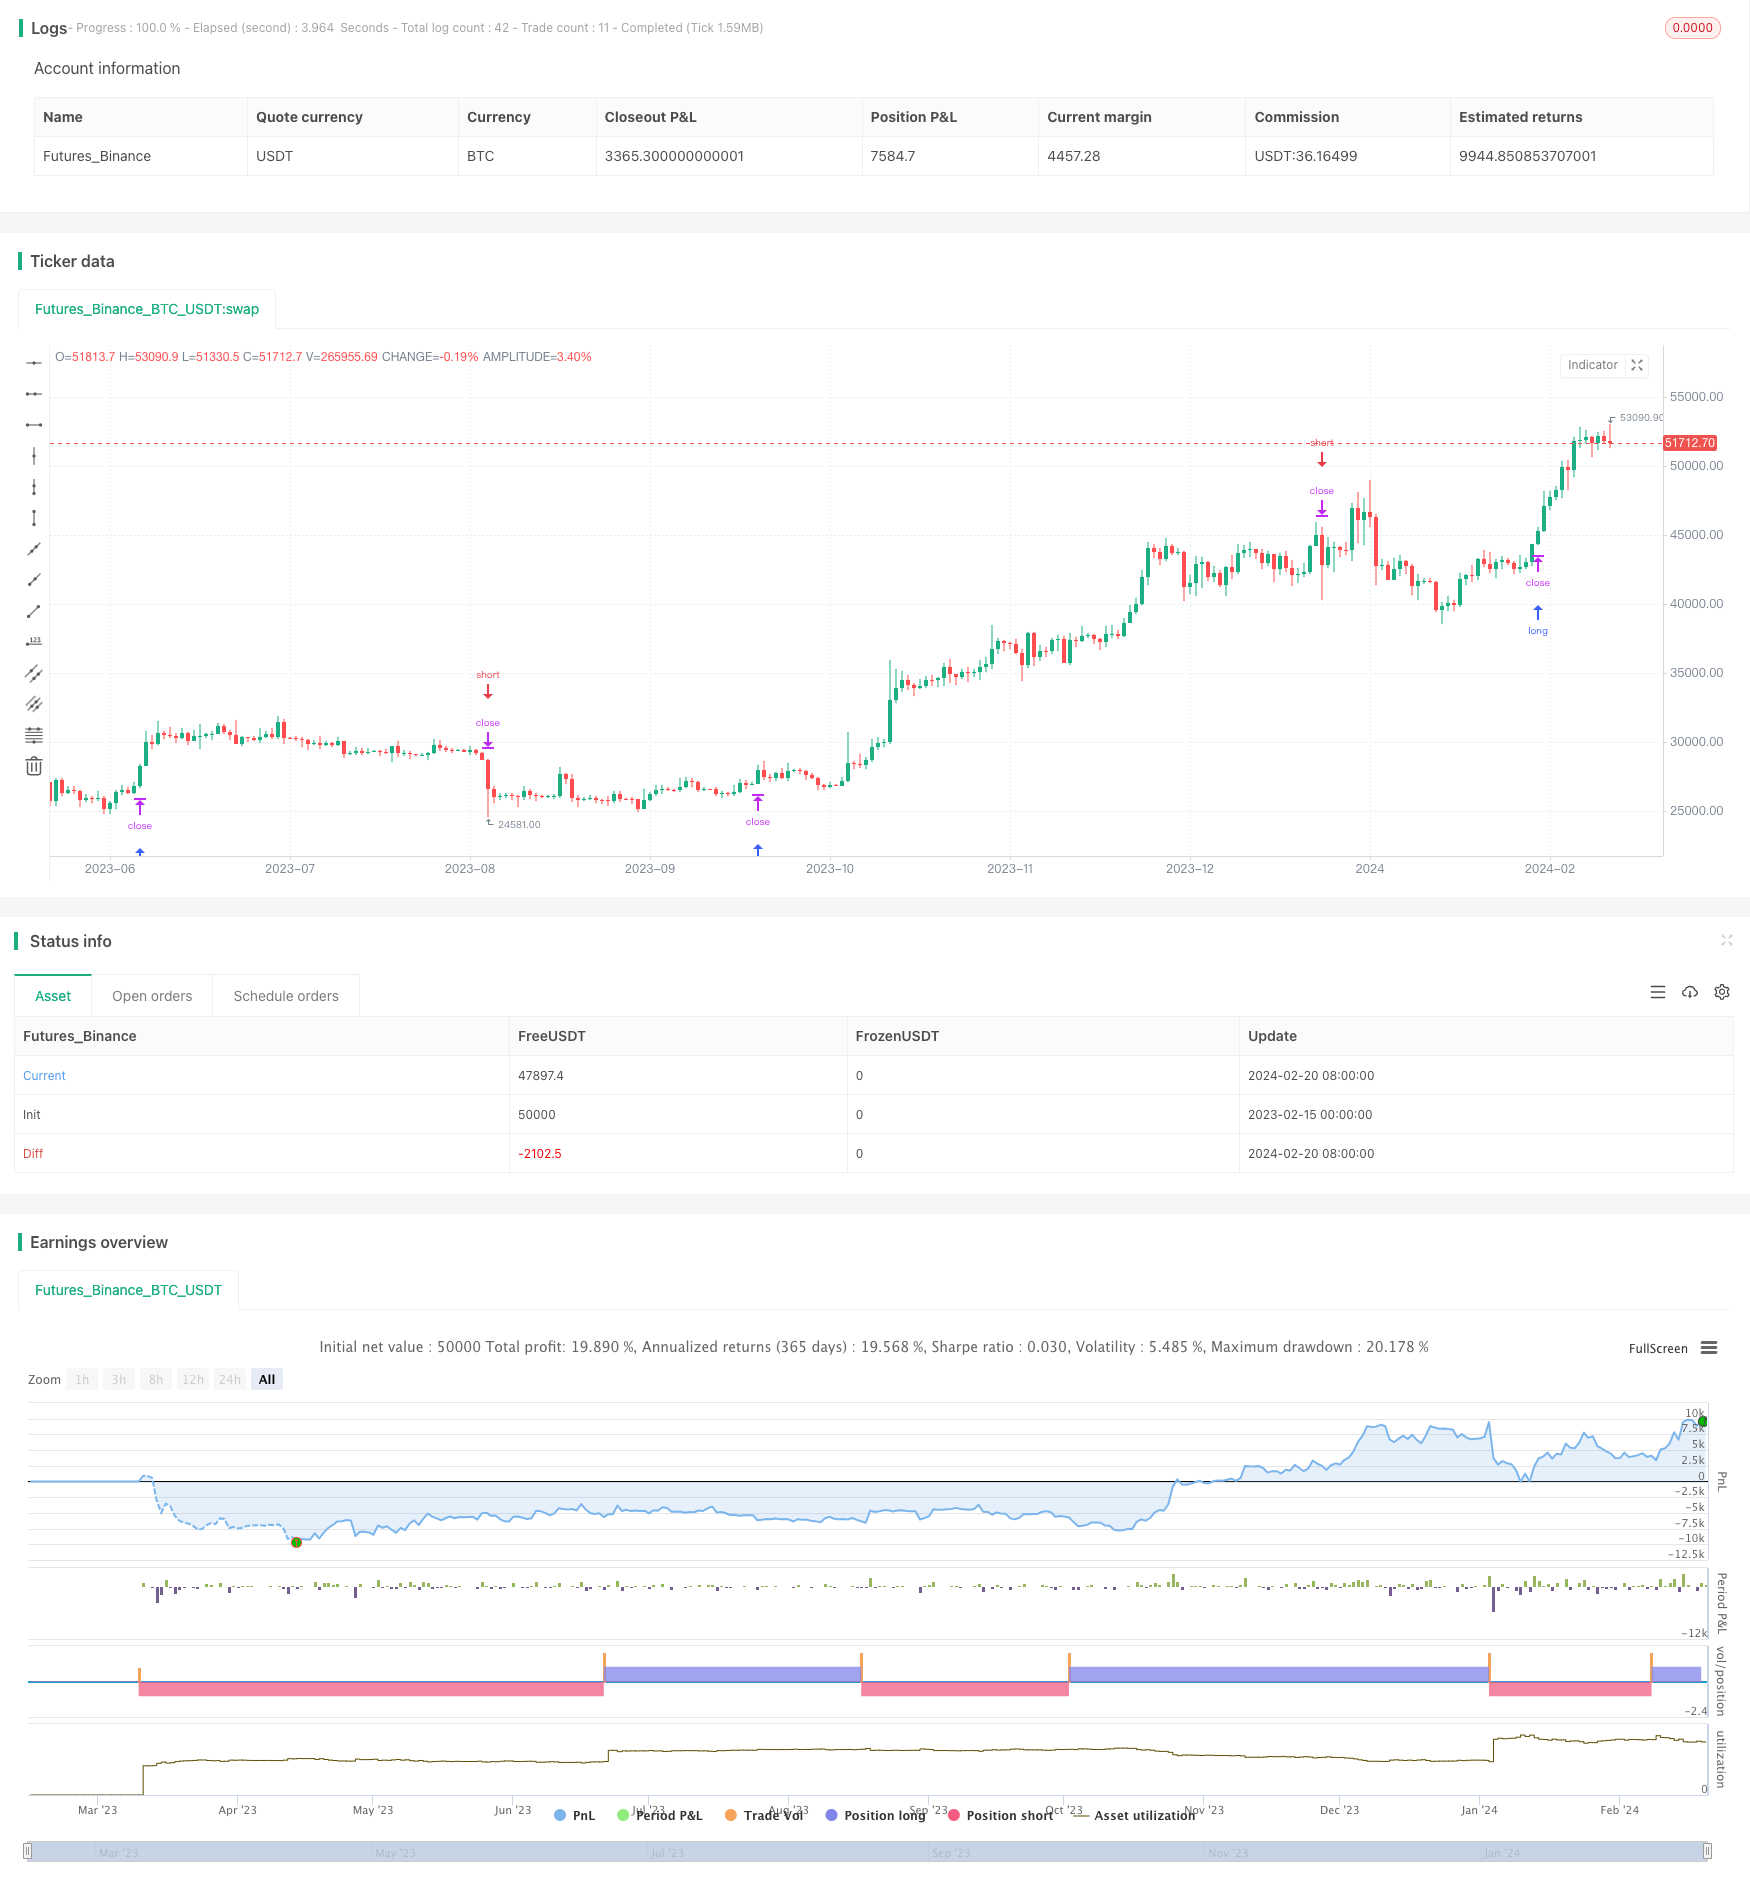
Overview
The Trend Hunter - MACD Momentum with MA strategy is an exquisite trading tool designed for traders seeking to capitalize on trending markets. Built on the robust combination of Average True Range (ATR), Simple Moving Average (SMA) and Moving Average Convergence Divergence (MACD), it filters and confirms trade entries with precision.
Strategy Logic
ATR Stop Loss
Utilizes the ATR indicator to dynamically tune stop levels, adapting to market volatility by customizing ATR Length and Multiplier, providing balanced risk management.
SMA Trend Filter
Employs SMA as a trend filter. By tuning SMA Period, users align the strategy timeframe with their preferred market trend, enhancing adaptability.
MACD Entry Confirmation
Incorporates MACD to refine entry signals by comparing the MACD line against its signal line, ensuring alignment with momentum.
Entry Logic
Long: Triggered when price closes above SMA, having closed below in the prior period, with MACD line crossing above signal line. Entry set at current price plus ATR stop distance.
Short: Triggered when price closes below SMA, after closing above in previous period, with MACD line falling below signal line. Entry set at current price minus ATR stop distance.
Advantages
This strategy harnesses volatility, trend and momentum dynamics to construct systematic entry and risk rules. Its blend of indicators enhances adaptability across various market conditions, making it an ideal tool for trend-following.
By tracking trend momentum, the Trend Hunter aids in uncovering profit opportunities. Fine-tuning parameters to match trading style allows observing how the strategy plays a vital role in signaling favorable trading junctures.
Risk Analysis
The strategy relies on indicator combinations to gauge market conditions, risking misjudgments in certain situations. Trend reversals may also lead to increased losses.
Lowering false signals through parameter adjustments or wider stop distances provides solutions. Pausing strategies during abnormal volatility also averts anomalies.
Optimization Paths
Parameter Tuning
Testing and optimizing ATR Length, SMA Period and MACD inputs finds ideal values matching trading style.
More Filters
Adding indicators like KDJ, OBV etc as auxiliary filters improves accuracy. Extra conditions like volume spikes also prevent whipsaws.
Stop Loss Strategies
Trailing or volatility stops that dynamically adjust stop distance minimizes losses by tracking prices.
Conclusion
The Trend Hunter strategy amalgamates volatility, trend and momentum dynamics into a precise entry confirmation and risk management system. Parameter adjustments cater to individual trading styles, aiding in capitalizing on opportunities. Worthwhile for quants to further explore and apply.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 20 | ATR Length |
| v_input_2 | 0.75 | ATR Multiplier |
| v_input_3 | 32 | SMA Period |
| v_input_4 | 12 | MACD Short Term |
| v_input_5 | 26 | MACD Long Term |
| v_input_6 | 9 | MACD Signal Smoothing |
Source Pine Script
/*backtest
start: 2023-02-15 00:00:00
end: 2024-02-21 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("trend_hunter", overlay=true)

length = input(20, title="ATR Length")
numATRs = input(0.75, title="ATR Multiplier")
atrs = ta.sma(ta.tr, length) * numATRs

// Trend Filter
smaPeriod = input(32, title="SMA Period")
sma = ta.sma(close, smaPeriod)

// MACD Filter
macdShortTerm = input(12, title="MACD Short Term")
macdLongTerm = input(26, title="MACD Long Term")
macdSignalSmoothing = input(9, title="MACD Signal Smoothing")

[macdLine, signalLine, _] = ta.macd(close, macdShortTerm, macdLongTerm, macdSignalSmoothing)

// Long Entry with Trend and MACD Filter
longCondition = close > sma and close[1] <= sma[1] and macdLine > signalLine
strategy.entry("Long", strategy.long, stop=close + atrs, when=longCondition, comment="Long")

// Short Entry with Trend and MACD Filter
shortCondition = close < sma and close[1] >= sma[1] and macdLine < signalLine
strategy.entry("Short", strategy.short, stop=close - atrs, when=shortCondition, comment="Short")

//plot(strategy.equity, title="equity", color=color.red, linewidth=2, style=plot.style_area)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MACD-Momentum-with-MA-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- Multi Indicator Trend Momentum Trading Strategy with Dynamic Risk Management SystemPine Script · Momentum · 1h
- Multi MA Trend Strength Capture with Momentum Profit Taking StrategyPine Script · Momentum · 2h
- Multi Trend Momentum Crossover Strategy with Volatility Optimization SystemPine Script · Momentum · 1d
- Enhanced Price Volume Trend Momentum StrategyPine Script · Momentum · 1d
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m