Strategy vault / Mean reversion
MACD Quantitative Trading Strategy
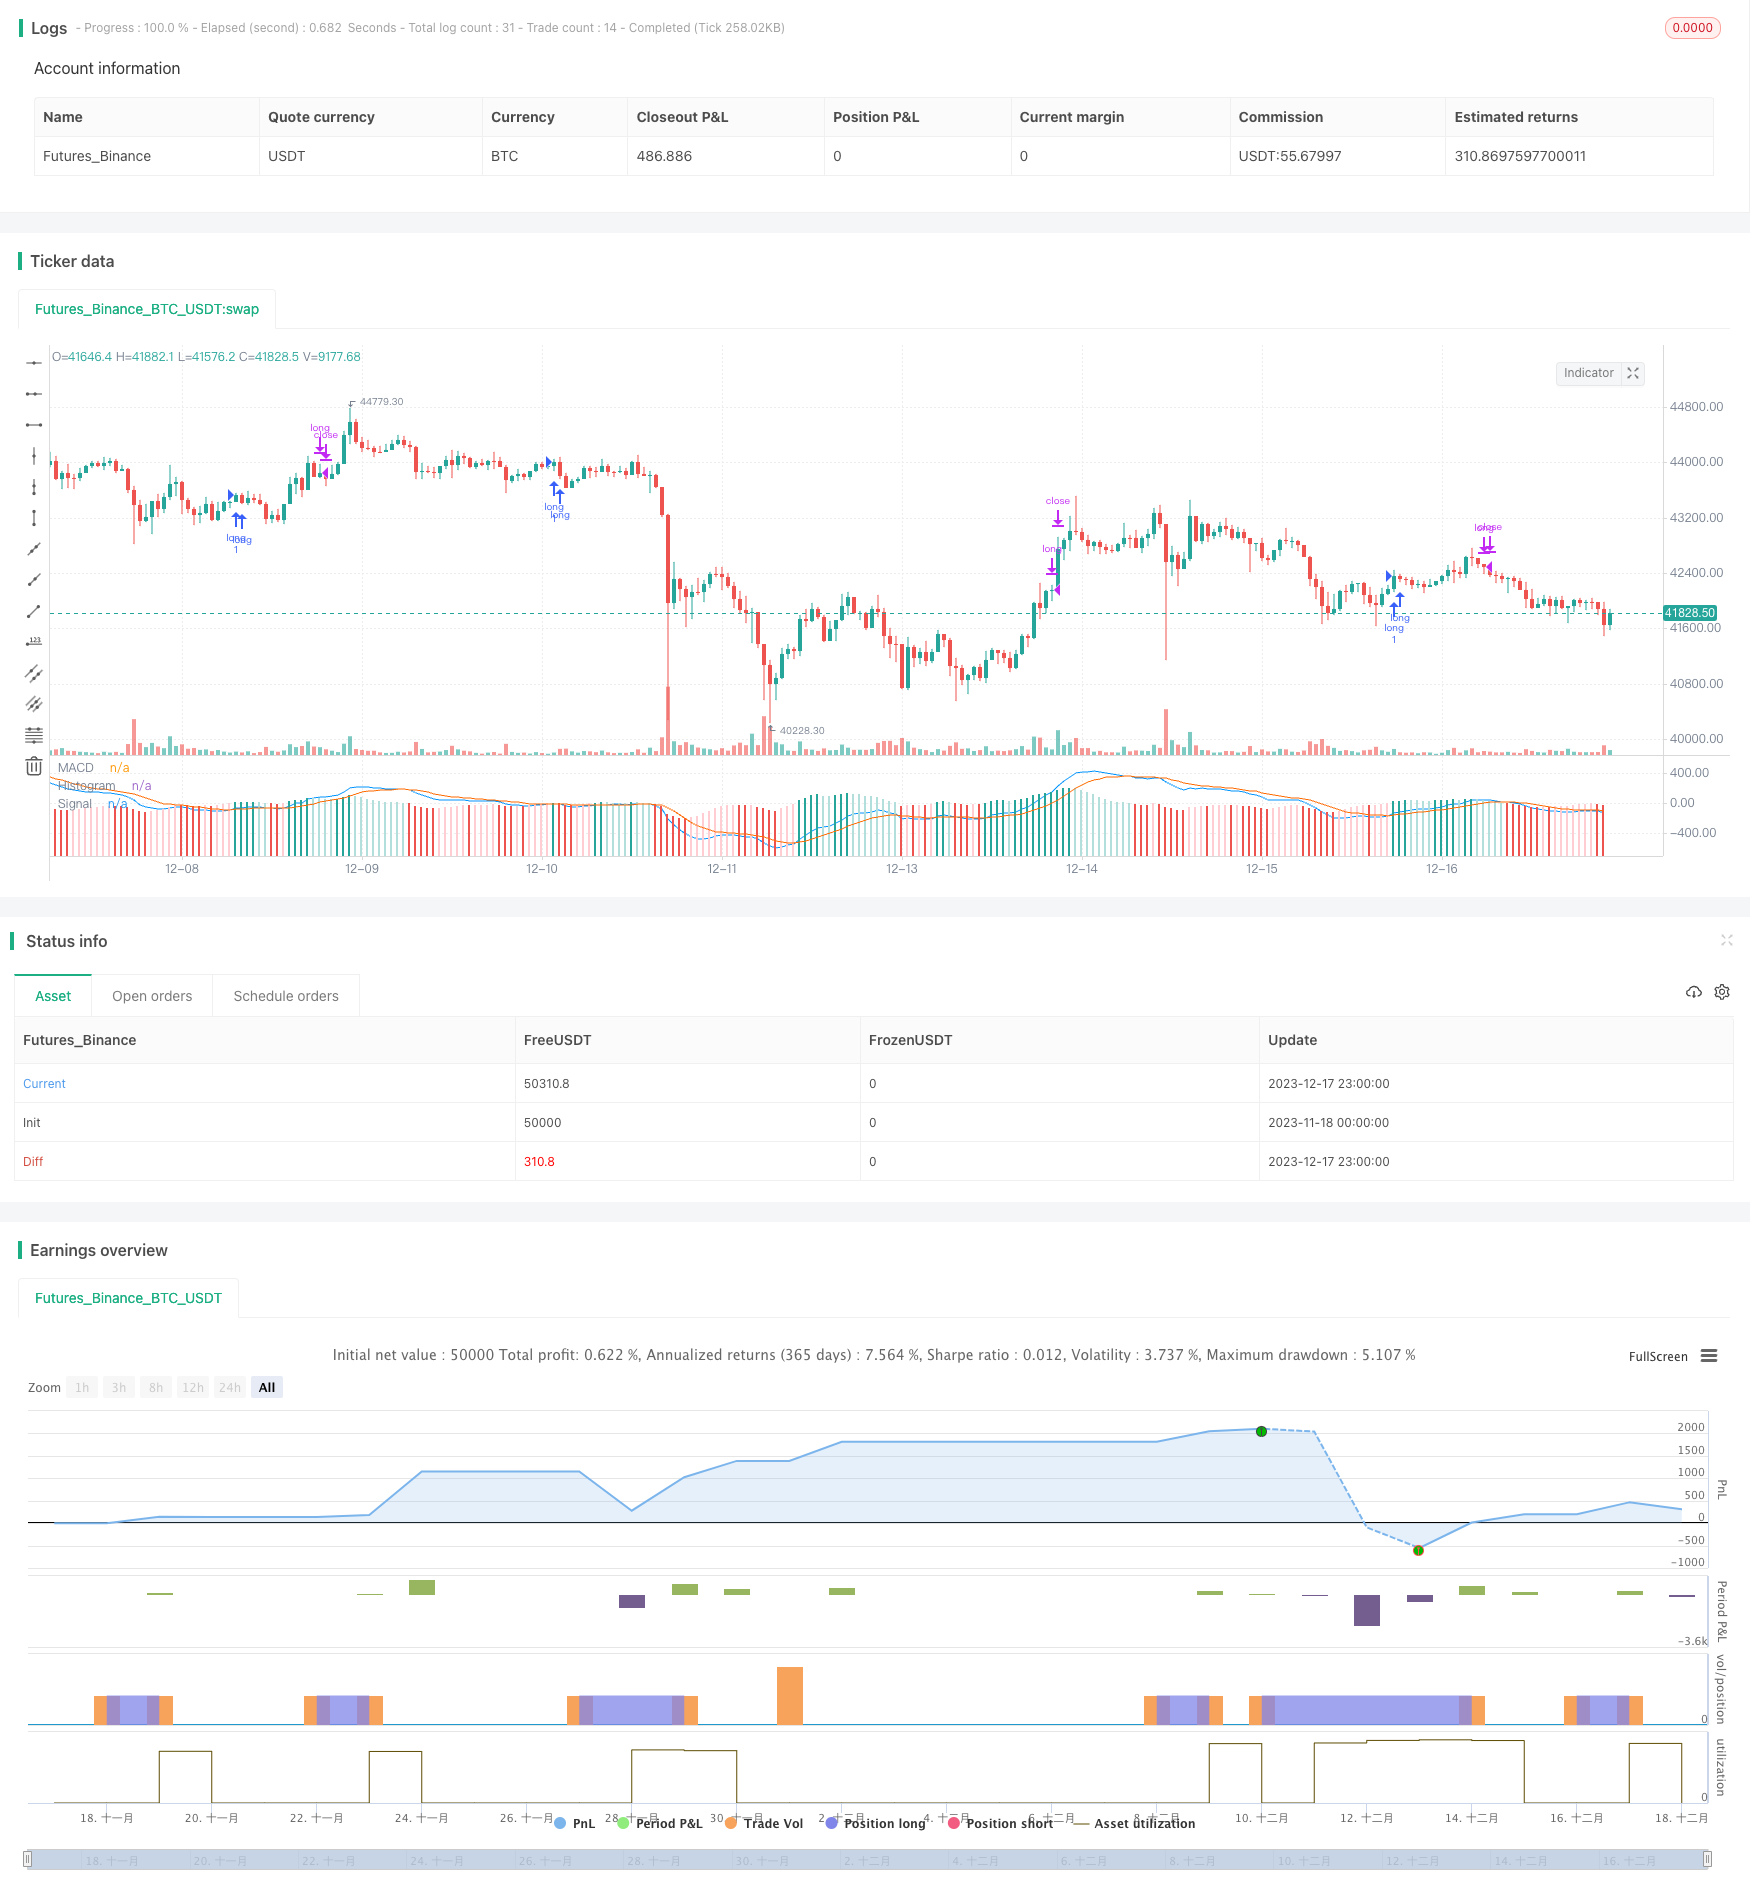
This strategy uses the MACD indicator to build long position trading signals when the MACD is below a certain level to take advantage of mean reversion opportunities.
Overview
This strategy uses the MACD indicator to build long position trading signals when the MACD is below a certain level to take advantage of mean reversion opportunities.
Strategy Logic
A long signal is generated when the MACD line is below the SIGNAL line and the absolute value of MACD is below -0.00025. After taking a long position, if the MACD line crosses above the SIGNAL line again, the position will be closed.
This strategy utilizes the MACD indicator to detect oversold zones. According to the theory of moving averages, there is a probability of mean reversion in the short term, and a long signal is established based on this probability.
Advantages
- Utilizes the MACD indicator to judge oversold levels, which has a certain reliability.
- Simple trading signals and rules that are easy to implement.
- Long holding periods means less frequent trading, reducing transaction costs and slippage.
Risks
- Risk of failed mean reversion. It will lead to losses if no reversion happens.
- Invalid signals from poor MACD parameter selection.
This risk can be reduced through parameter optimization.
Enhancements
- Optimize MACD parameters to find best combinations.
- Test different holding periods to find optimal duration.
- Add stop loss mechanisms.
Summary
This strategy utilizes the probability of mean reversions from oversold levels identified by the MACD indicator to generate long signals, and profits through long holding periods. Optimizing MACD parameters and adding stop losses improves reliability. In summary, it uses relatively simple indicators and rules to construct an easy to understand and implement quantitative strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 12 | Fast Length |
| v_input_2 | 26 | Slow Length |
| v_input_3_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_4 | 9 | Signal Smoothing |
| v_input_5 | false | Simple MA(Oscillator) |
| v_input_6 | false | Simple MA(Signal Line) |
Source Pine Script
//@version=3
strategy(title="MACD - EURUSD", shorttitle="MACD EURUSD")

// Getting inputs
fast_length = input(title="Fast Length",  defval=12)
slow_length = input(title="Slow Length",  defval=26)
src = input(title="Source", defval=close)
signal_length = input(title="Signal Smoothing",  minval = 1, maxval = 50, defval =9)
sma_source = input(title="Simple MA(Oscillator)", type=bool, defval=false)
sma_signal = input(title="Simple MA(Signal Line)", type=bool, defval=false)

// Plot colors
col_grow_above = #26A69A
col_grow_below = #FFCDD2
col_fall_above = #B2DFDB
col_fall_below = #EF5350
col_macd = #0094ff
col_signal = #ff6a00

// Calculating
fast_ma = sma_source ? sma(src, fast_length) : ema(src, fast_length)
slow_ma = sma_source ? sma(src, slow_length) : ema(src, slow_length)
macd = fast_ma - slow_ma
signal = sma_signal ? sma(macd, signal_length) : ema(macd, signal_length)
hist = macd - signal

plot(hist, title="Histogram", style=columns, color=(hist>=0 ? (hist[1] < hist ? col_grow_above : col_fall_above) : (hist[1] < hist ? col_grow_below : col_fall_below) ), transp=0 )
plot(macd, title="MACD", color=col_macd, transp=0)
plot(signal, title="Signal", color=col_signal, transp=0)

longCond = crossover(macd, signal) and macd < -0.00025
exitLong = crossover(macd, hist)


strategy.entry("long", strategy.long,  when=longCond==true)
strategy.close("long", when=exitLong==true)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MACD-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- MACD Cross Period Trading StrategyPine Script · Mean reversion · 1d
- MACD Double Optimization Trading StrategyPine Script · Mean reversion · 1d