MACD Willy Strategy
This strategy is mainly developed for scalping / intraday trading. It could potentially be used to identify entry/exit signals for short term options trading. It performs decently well on popular stocks when used on…
This strategy is mainly developed for scalping / intraday trading. It could potentially be used to identify entry/exit signals for short term options trading. It performs decently well on popular stocks when used on time frames between 5 min to 15 min using regular session bar data. It combines 3 popular indicators, EMA , MACD , and William %range, to generate both long and short signals.
EMA: Default is 200 EMA line.
MACD: Default is 12/26 lengths for fast/slow signal inputs.
William %R - Smoothed (Published): This is a custom indicator that generates two moving average lines from the original William %R line.
How it works: Entry conditions:
- Long/short entries when bar closes above/below EMA line
- Long/short entries when MACD line is above/below signal line (histogram > 0 for long, < 0 for short)
- Long/short entries when William %R fast MA line is above/below slow MA line
Exit conditions:
- Exit long when MACD line is below signal line, vise versa for exit short
- Exit long when William %R fast MA line is below slow MA line, vise versa for exit short
- Exit long when William %R fast MA line must in below the overbought (-20) limit, exit short when above the oversold (-80) limit.
Note that parameters are NOT optimized for any particular stocks / instruments.
Enjoy~~!!
backtest
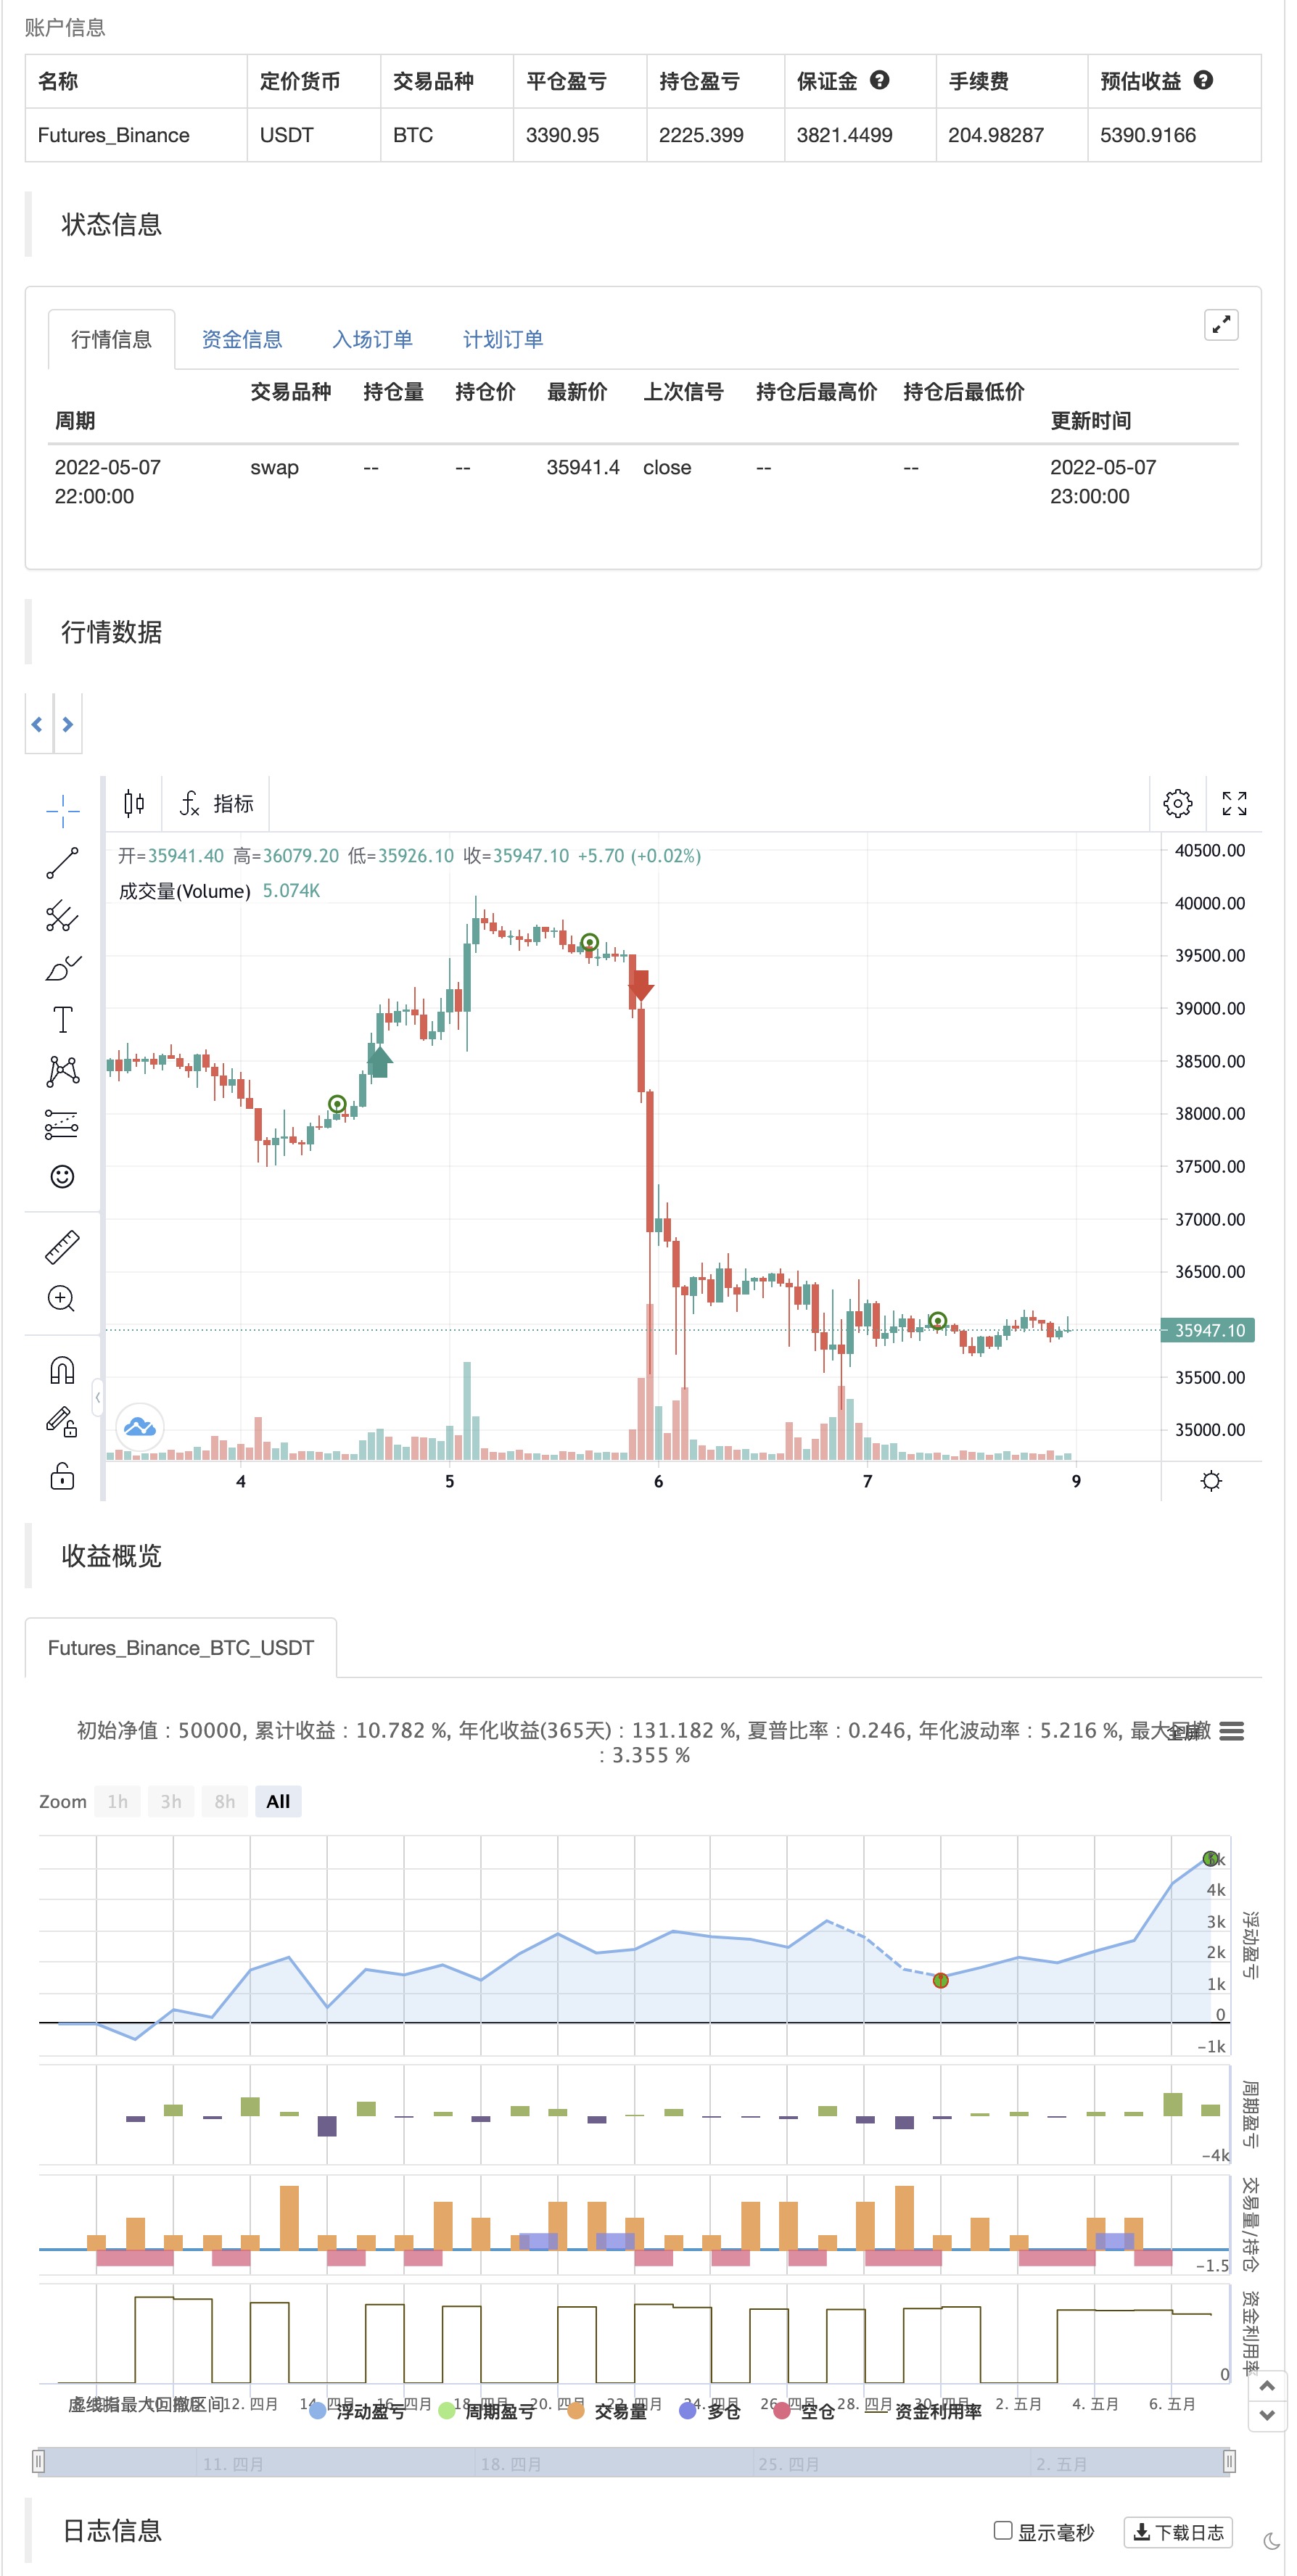
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_3_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_4 | 50 | Volume MA Period |
| v_input_5 | 12 | Fast Length |
| v_input_6 | 26 | Slow Length |
| v_input_int_7 | 9 | Signal Smoothing |
| v_input_string_1 | 0 | Oscillator MA Type: EMA | SMA |
| v_input_string_2 | 0 | Signal Line MA Type: EMA | SMA |
| v_input_int_8 | 34 | w_length |
| v_input_13 | 5 | Smoothed %R Length |
| v_input_14 | 13 | Slow EMA Length |
| v_input_1 | 2011 | (?Trading window)Start Year |
| v_input_int_1 | true | Start Month |
| v_input_int_2 | true | Start Day |
| v_input_2 | 2050 | Finish Year |
| v_input_int_3 | 12 | Finish Month |
| v_input_int_4 | 31 | Finish Day |
| v_input_float_1 | true | (?Trading Options)Leverage (if applicable) |
| v_input_bool_1 | false | Reinvest profit |
| v_input_float_2 | 20 | Reinvest percentage |
| v_input_int_5 | 14 | (?Daily ATR)ATR period |
| v_input_float_3 | 5 | % ATR to use for SL / PT |
| v_input_int_6 | 200 | (?Moving Averages)EMA |
| v_input_7 | #2962FF | (?Color Settings)MACD Line |
| v_input_8 | #FF6D00 | Signal Line |
| v_input_9 | #26A69A | (?Histogram)Above Grow |
| v_input_10 | #B2DFDB | Fall |
| v_input_11 | #FFCDD2 | Below Grow |
| v_input_12 | #FF5252 | Fall |
Source Pine Script
/*backtest
start: 2022-04-08 00:00:00
end: 2022-05-07 23:59:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © platsn

//@version=5
strategy("MACD Willy Strategy", overlay=true, pyramiding=1, initial_capital=10000)

// ******************** Trade Period **************************************
startY = input(title='Start Year', defval=2011, group = "Trading window")
startM = input.int(title='Start Month', defval=1, minval=1, maxval=12, group = "Trading window")
startD = input.int(title='Start Day', defval=1, minval=1, maxval=31, group = "Trading window")
finishY = input(title='Finish Year', defval=2050, group = "Trading window")
finishM = input.int(title='Finish Month', defval=12, minval=1, maxval=12, group = "Trading window")
finishD = input.int(title='Finish Day', defval=31, minval=1, maxval=31, group = "Trading window")
//timestart = timestamp(startY, startM, startD, 00, 00)
//timefinish = timestamp(finishY, finishM, finishD, 23, 59)
// t1 = time(timeframe.period, "0945-1545:23456")
// window = time >= timestart and time <= timefinish and t1 ? true : false
// t2 = time(timeframe.period, "0930-1555:23456")
// window2 = time >= timestart and time <= timefinish and t2 ? true : false

leverage = input.float(1, title="Leverage (if applicable)", step=0.1, group = "Trading Options")
reinvest = input.bool(defval=false,title="Reinvest profit", group = "Trading Options")
reinvest_percent = input.float(defval=20, title = "Reinvest percentage", group="Trading Options")
// entry_lookback = input.int(defval=10, title="Lookback period for entry condition", group = "Trading Options")

// -------------------------------------------- Data Source --------------------------------------------

src = input(title="Source", defval=close)

// ***************************************************************************************************** Daily ATR *****************************************************
atrlen = input.int(14, minval=1, title="ATR period", group = "Daily ATR")
iPercent = input.float(5, minval=1, maxval=100, step=0.1, title="% ATR to use for SL / PT", group = "Daily ATR")

percentage = iPercent * 0.01
datr = request.security(syminfo.tickerid, "1D", ta.rma(ta.tr, atrlen))
datrp = datr * percentage

// plot(datr,"Daily ATR")
// plot(datrp, "Daily % ATR")

//*********************************************************** VIX volatility index ****************************************

//VIX = request.security("VIX", timeframe.period, close)
//vix_thres = input.float(20.0, "VIX Threshold for entry", step=0.5, group="VIX Volatility Index")

// ************************************************ Volume ******************************************************

vol_len = input(50, 'Volume MA Period')
avg_vol = ta.sma(volume, vol_len)

//-------------------------------------------------------- Moving Average ------------------------------------

emalen1 = input.int(200, minval=1, title='EMA', group= "Moving Averages")
ema1 = ta.ema(src, emalen1)

// ------------------------------------------ MACD ------------------------------------------
// Getting inputs
fast_length = input(title="Fast Length", defval=12)
slow_length = input(title="Slow Length", defval=26)
signal_length = input.int(title="Signal Smoothing",  minval = 1, maxval = 50, defval = 9)
sma_source = input.string(title="Oscillator MA Type",  defval="EMA", options=["SMA", "EMA"])
sma_signal = input.string(title="Signal Line MA Type", defval="EMA", options=["SMA", "EMA"])
// Plot colors
col_macd = input(#2962FF, "MACD Line  ", group="Color Settings", inline="MACD")
col_signal = input(#FF6D00, "Signal Line  ", group="Color Settings", inline="Signal")
col_grow_above = input(#26A69A, "Above   Grow", group="Histogram", inline="Above")
col_fall_above = input(#B2DFDB, "Fall", group="Histogram", inline="Above")
col_grow_below = input(#FFCDD2, "Below Grow", group="Histogram", inline="Below")
col_fall_below = input(#FF5252, "Fall", group="Histogram", inline="Below")
// Calculating
fast_ma = sma_source == "SMA" ? ta.sma(src, fast_length) : ta.ema(src, fast_length)
slow_ma = sma_source == "SMA" ? ta.sma(src, slow_length) : ta.ema(src, slow_length)
macd = fast_ma - slow_ma
signal = sma_signal == "SMA" ? ta.sma(macd, signal_length) : ta.ema(macd, signal_length)
hist = macd - signal

// ---------------------------------------- William %R --------------------------------------
w_length = input.int(defval=34, minval=1)
w_upper = ta.highest(w_length)
w_lower = ta.lowest(w_length)

w_output = 100 * (close - w_upper) / (w_upper - w_lower)

fast_period = input(defval=5, title='Smoothed %R Length')
slow_period = input(defval=13, title='Slow EMA Length')

w_fast_ma = ta.wma(w_output,fast_period)
w_slow_ma = ta.ema(w_output,slow_period)


// ------------------------------------------------ Entry Conditions ----------------------------------------

L_entry1 = close > ema1 and hist > 0 and w_fast_ma > w_slow_ma
S_entry1 = close < ema1 and hist < 0 and w_fast_ma < w_slow_ma

// -------------------------------------------------- Entry -----------------------------------------------

//profit = strategy.netprofit
//trade_amount = math.floor(strategy.initial_capital*leverage / close)

//if strategy.netprofit > 0 and reinvest
//    trade_amount := math.floor((strategy.initial_capital+(profit*reinvest_percent*0.01))*leverage / close)
//else
//    trade_amount := math.floor(strategy.initial_capital*leverage/ close)


if L_entry1 //and window
    strategy.entry("Long", strategy.long)

if S_entry1 //and window
    strategy.entry("Short", strategy.short)

// --------------------------------------------------- Exit Conditions -------------------------------------

L_exit1 = hist < 0 and w_fast_ma < w_slow_ma and w_fast_ma < -20
S_exit1 = hist > 0 and w_fast_ma > w_slow_ma and w_fast_ma > -80

// ----------------------------------------------------- Exit ---------------------------------------------

if L_exit1 //and window2
    strategy.close("Long")

if S_exit1 //and window2
    strategy.close("Short")

// if time(timeframe.period, "1530-1600:23456")
// strategy.close_all()Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-09. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MACD-Willy-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Joanne on Crypto Dual Moving Average with MACD Scalping StrategyPine Script · Scalping · 1h
- Vitalik ScalpePine Script · Scalping
- 20Bitcoin and Gold 5 Minute Scalping Strategy 20Pine Script · Scalping · 1h
- Super ScalperPine Script · Scalping · 1m
- Advanced Multi Trend Confirmation EMA Supply Demand Zone Dynamic Scalping StrategyPine Script · Scalping · 1d
- Bollinger Awesome Alert R1Pine Script · Scalping · 1h