Strategy vault / Mean reversion
Mean Reversion with Incremental Entry Strategy
The Mean Reversion with Incremental Entry strategy designed by HedgerLabs is an advanced trading strategy script focusing on the mean reversion technique in financial markets. It is tailored for traders who prefer a…
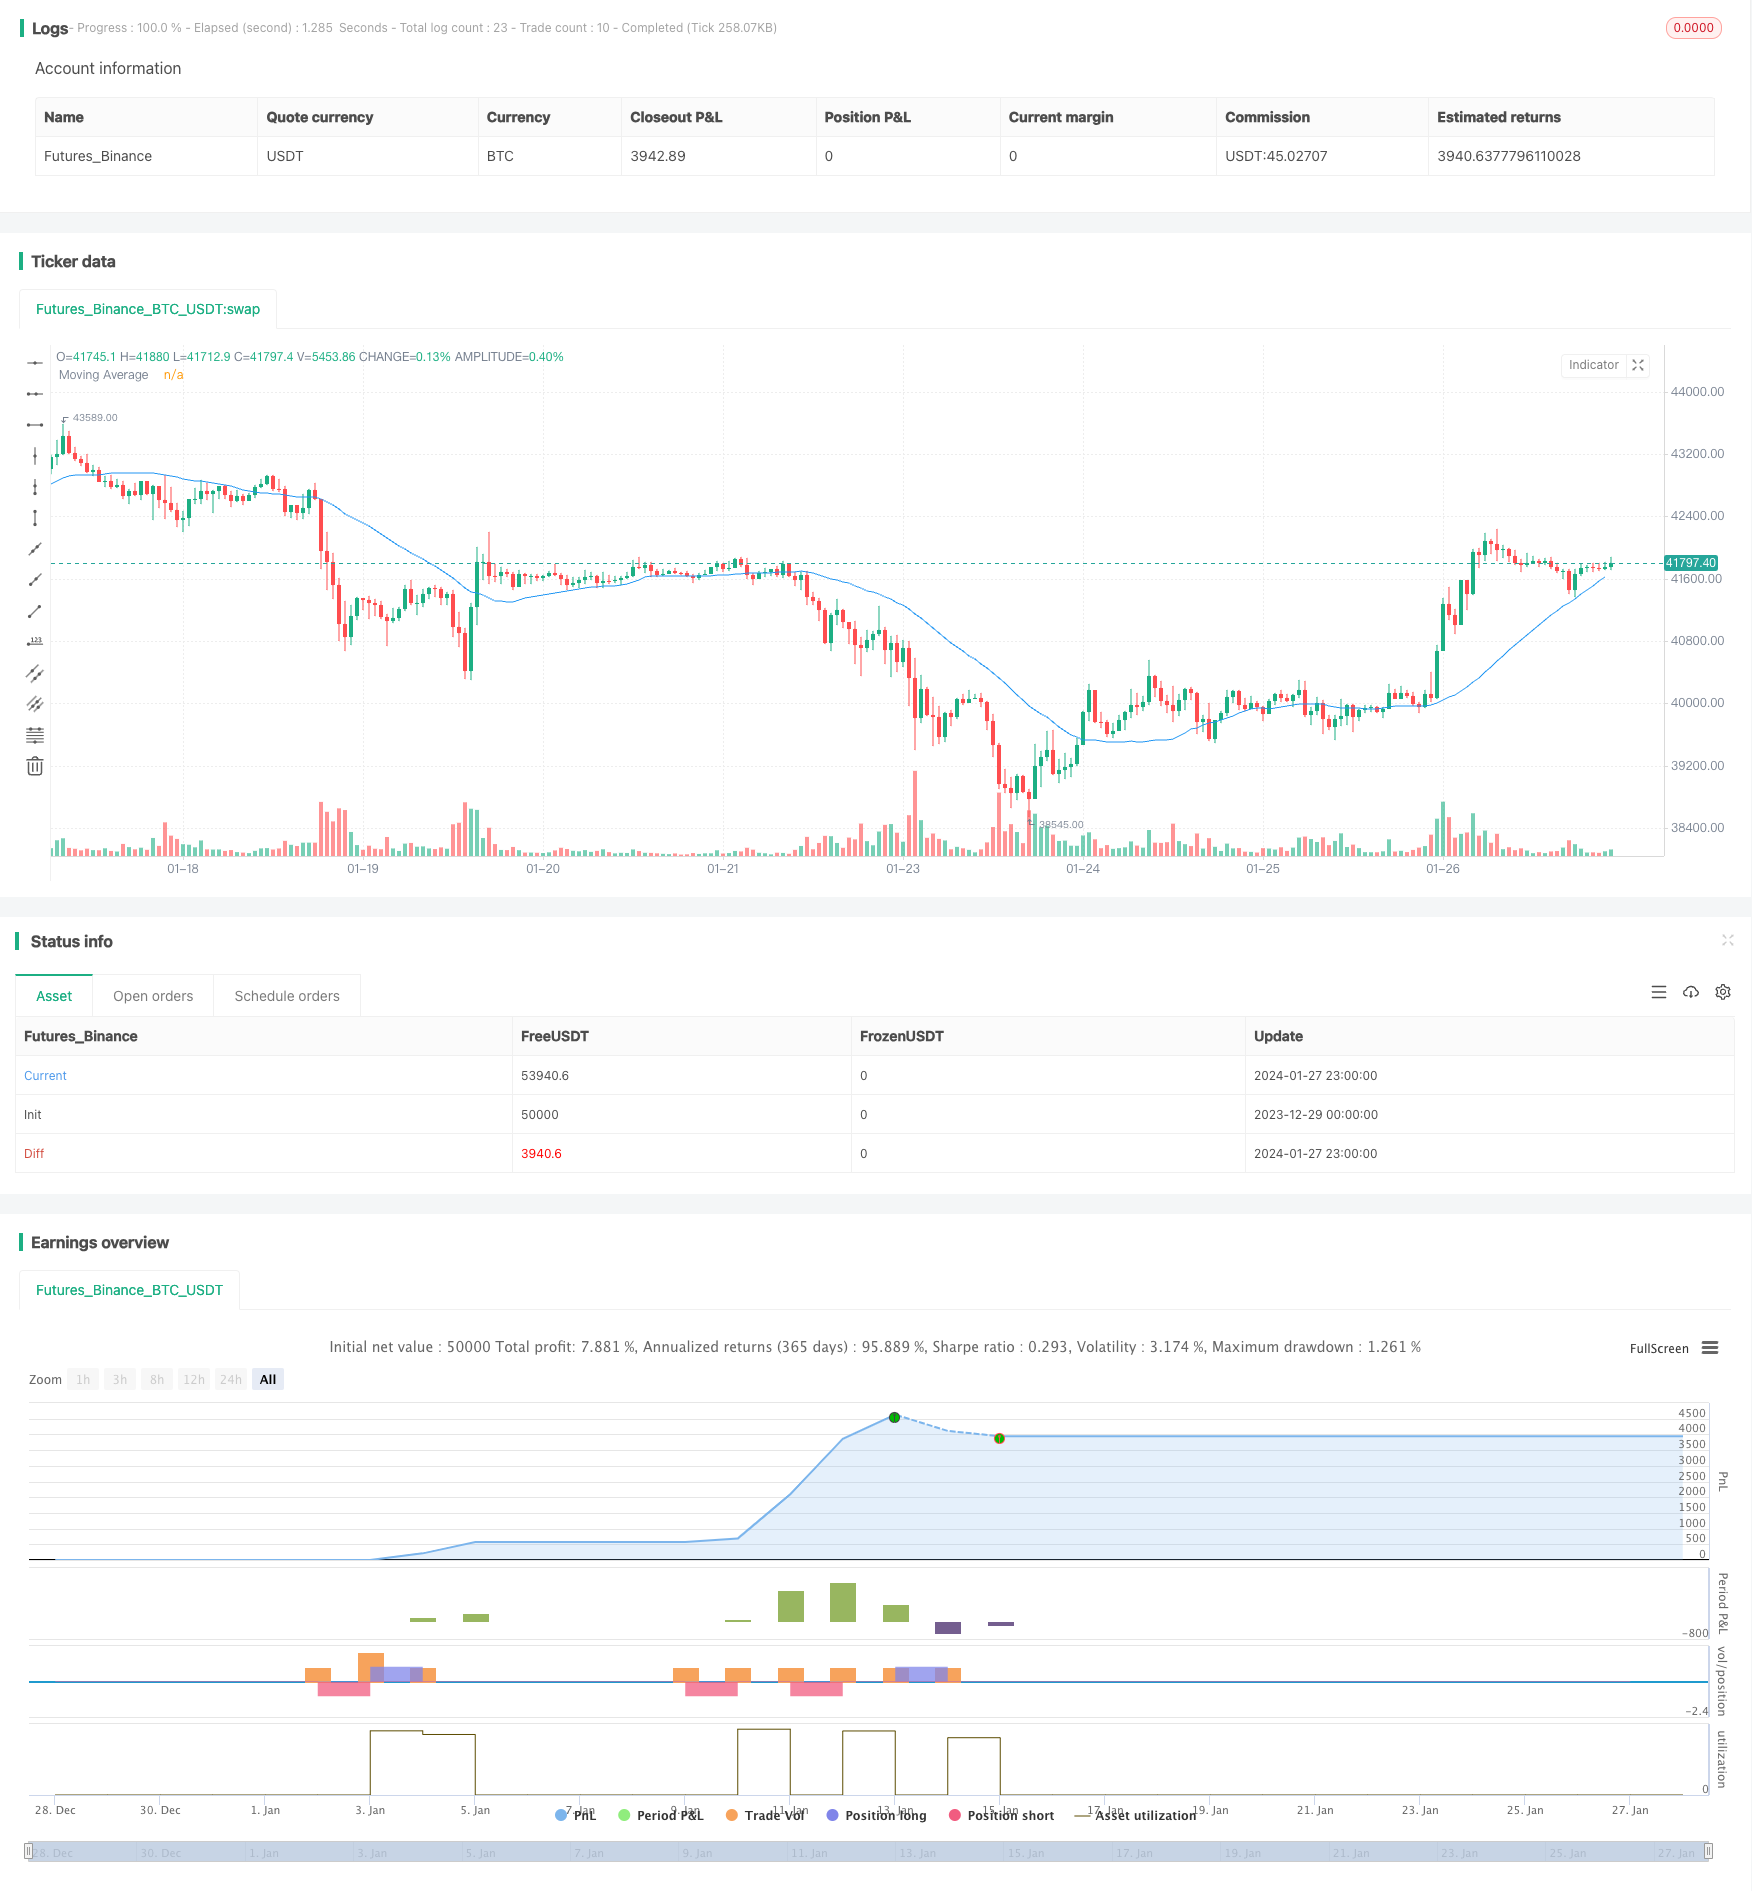
Overview
The Mean Reversion with Incremental Entry strategy designed by HedgerLabs is an advanced trading strategy script focusing on the mean reversion technique in financial markets. It is tailored for traders who prefer a systematic approach with emphasis on incremental entries based on price movements relative to a moving average.
Strategy Logic
Central to this strategy is the Simple Moving Average (SMA) which all entries and exits revolve around. Traders can customize the MA length to suit different trading styles and timeframes.
Unique to this strategy is the incremental entry system. It initiates a first position when the price deviates from the MA by a specified percentage. Subsequent entries are then made in incremental steps, as defined by the trader, as the price moves further away from the MA. This aims to capitalize on increasing volatility.
The strategy intelligently manages positions by entering long when price is below MA and short when above to adapt to changing market conditions.
Exits are determined when the price touches the MA, with the goal of closing positions at potential reversal points for optimized outcomes.
With calc_on_every_tick enabled, the strategy continually evaluates the market to ensure prompt reaction.
Advantage Analysis
The Mean Reversion with Incremental Entry strategy has the following key advantages:
- Highly systematized to reduce emotional interference
- Incremental entry captures greater profit during high volatility
- Customizable parameters like MA period suit different instruments
- Intelligent position management automatically adapts long/short
- Optimal exit targeting reversals to close positions
Risk Analysis
The risks to consider include:
- Whipsaws from technical indicator reliance
- Trendlessness causing extended drawdowns
- Poor MA settings lead to frequent stop outs
- Larger position size from incremental entry
Exits can be optimized, trend filters added, position sizing reduced to mitigate the above risks.
Enhancement Opportunities
The strategy can be enhanced by:
- Adding trend filters to avoid unfavorable trades
- Optimizing entry increments with volatility
- Incorporating trailing stops to lock in profits
- Experimenting with different moving averages
- Using filters to reduce false signals
Conclusion
The Mean Reversion with Incremental Entry strategy focuses on mean reversion techniques using a systemized incremental position sizing approach. With customizable settings, it is adaptable across different trading instruments. It performs well in ranging markets and suits short-term systematic traders.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 30 | MA Length |
| v_input_float_1 | 5 | Initial Percent for First Order |
| v_input_float_2 | true | Percent Step for Additional Orders |
Source Pine Script
/*backtest
start: 2023-12-29 00:00:00
end: 2024-01-28 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Mean Reversion with Incremental Entry by HedgerLabs", overlay=true, calc_on_every_tick=true)

// Input for adjustable settings
maLength = input.int(30, title="MA Length", minval=1)
initialPercent = input.float(5, title="Initial Percent for First Order", minval=0.01, step=0.01)
percentStep = input.float(1, title="Percent Step for Additional Orders", minval=0.01, step=0.01)

// Calculating Moving Average
ma = ta.sma(close, maLength)

// Plotting the Moving Average
plot(ma, "Moving Average", color=color.blue)

var float lastBuyPrice = na
var float lastSellPrice = na

// Function to calculate absolute price percentage difference
pricePercentDiff(price1, price2) =>
    diff = math.abs(price1 - price2) / price2 * 100
    diff

// Initial Entry Condition Check Function
initialEntryCondition(price, ma, initialPercent) =>
    pricePercentDiff(price, ma) >= initialPercent

// Enhanced Entry Logic for Buy and Sell
if (low < ma)
    if (na(lastBuyPrice))
        if (initialEntryCondition(low, ma, initialPercent))
            strategy.entry("Buy", strategy.long)
            lastBuyPrice := low
    else
        if (low < lastBuyPrice and pricePercentDiff(low, lastBuyPrice) >= percentStep)
            strategy.entry("Buy", strategy.long)
            lastBuyPrice := low

if (high > ma)
    if (na(lastSellPrice))
        if (initialEntryCondition(high, ma, initialPercent))
            strategy.entry("Sell", strategy.short)
            lastSellPrice := high
    else
        if (high > lastSellPrice and pricePercentDiff(high, lastSellPrice) >= percentStep)
            strategy.entry("Sell", strategy.short)
            lastSellPrice := high

// Exit Conditions - Close position if price touches the MA
if (close >= ma and strategy.position_size > 0)
    strategy.close("Buy")
    lastBuyPrice := na

if (close <= ma and strategy.position_size < 0)
    strategy.close("Sell")
    lastSellPrice := na

// Reset last order price when position is closed
if (strategy.position_size == 0)
    lastBuyPrice := na
    lastSellPrice := na
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Mean-Reversion-with-Incremental-Entry-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 3 10 Oscillator Profile Flagging StrategyPine Script · Mean reversion · 1d
- A Trend Reversal Strategy Based on Moving Averages Price Patterns and VolumePine Script · Mean reversion · 1d
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d