Momentum and Moving Average Combination Long Strategy
This strategy combines the MACD momentum indicator and the DMI trend indicator to go long when conditions are met. Its exits set a fixed take profit and a custom volatility trailing stop to lock in profits.
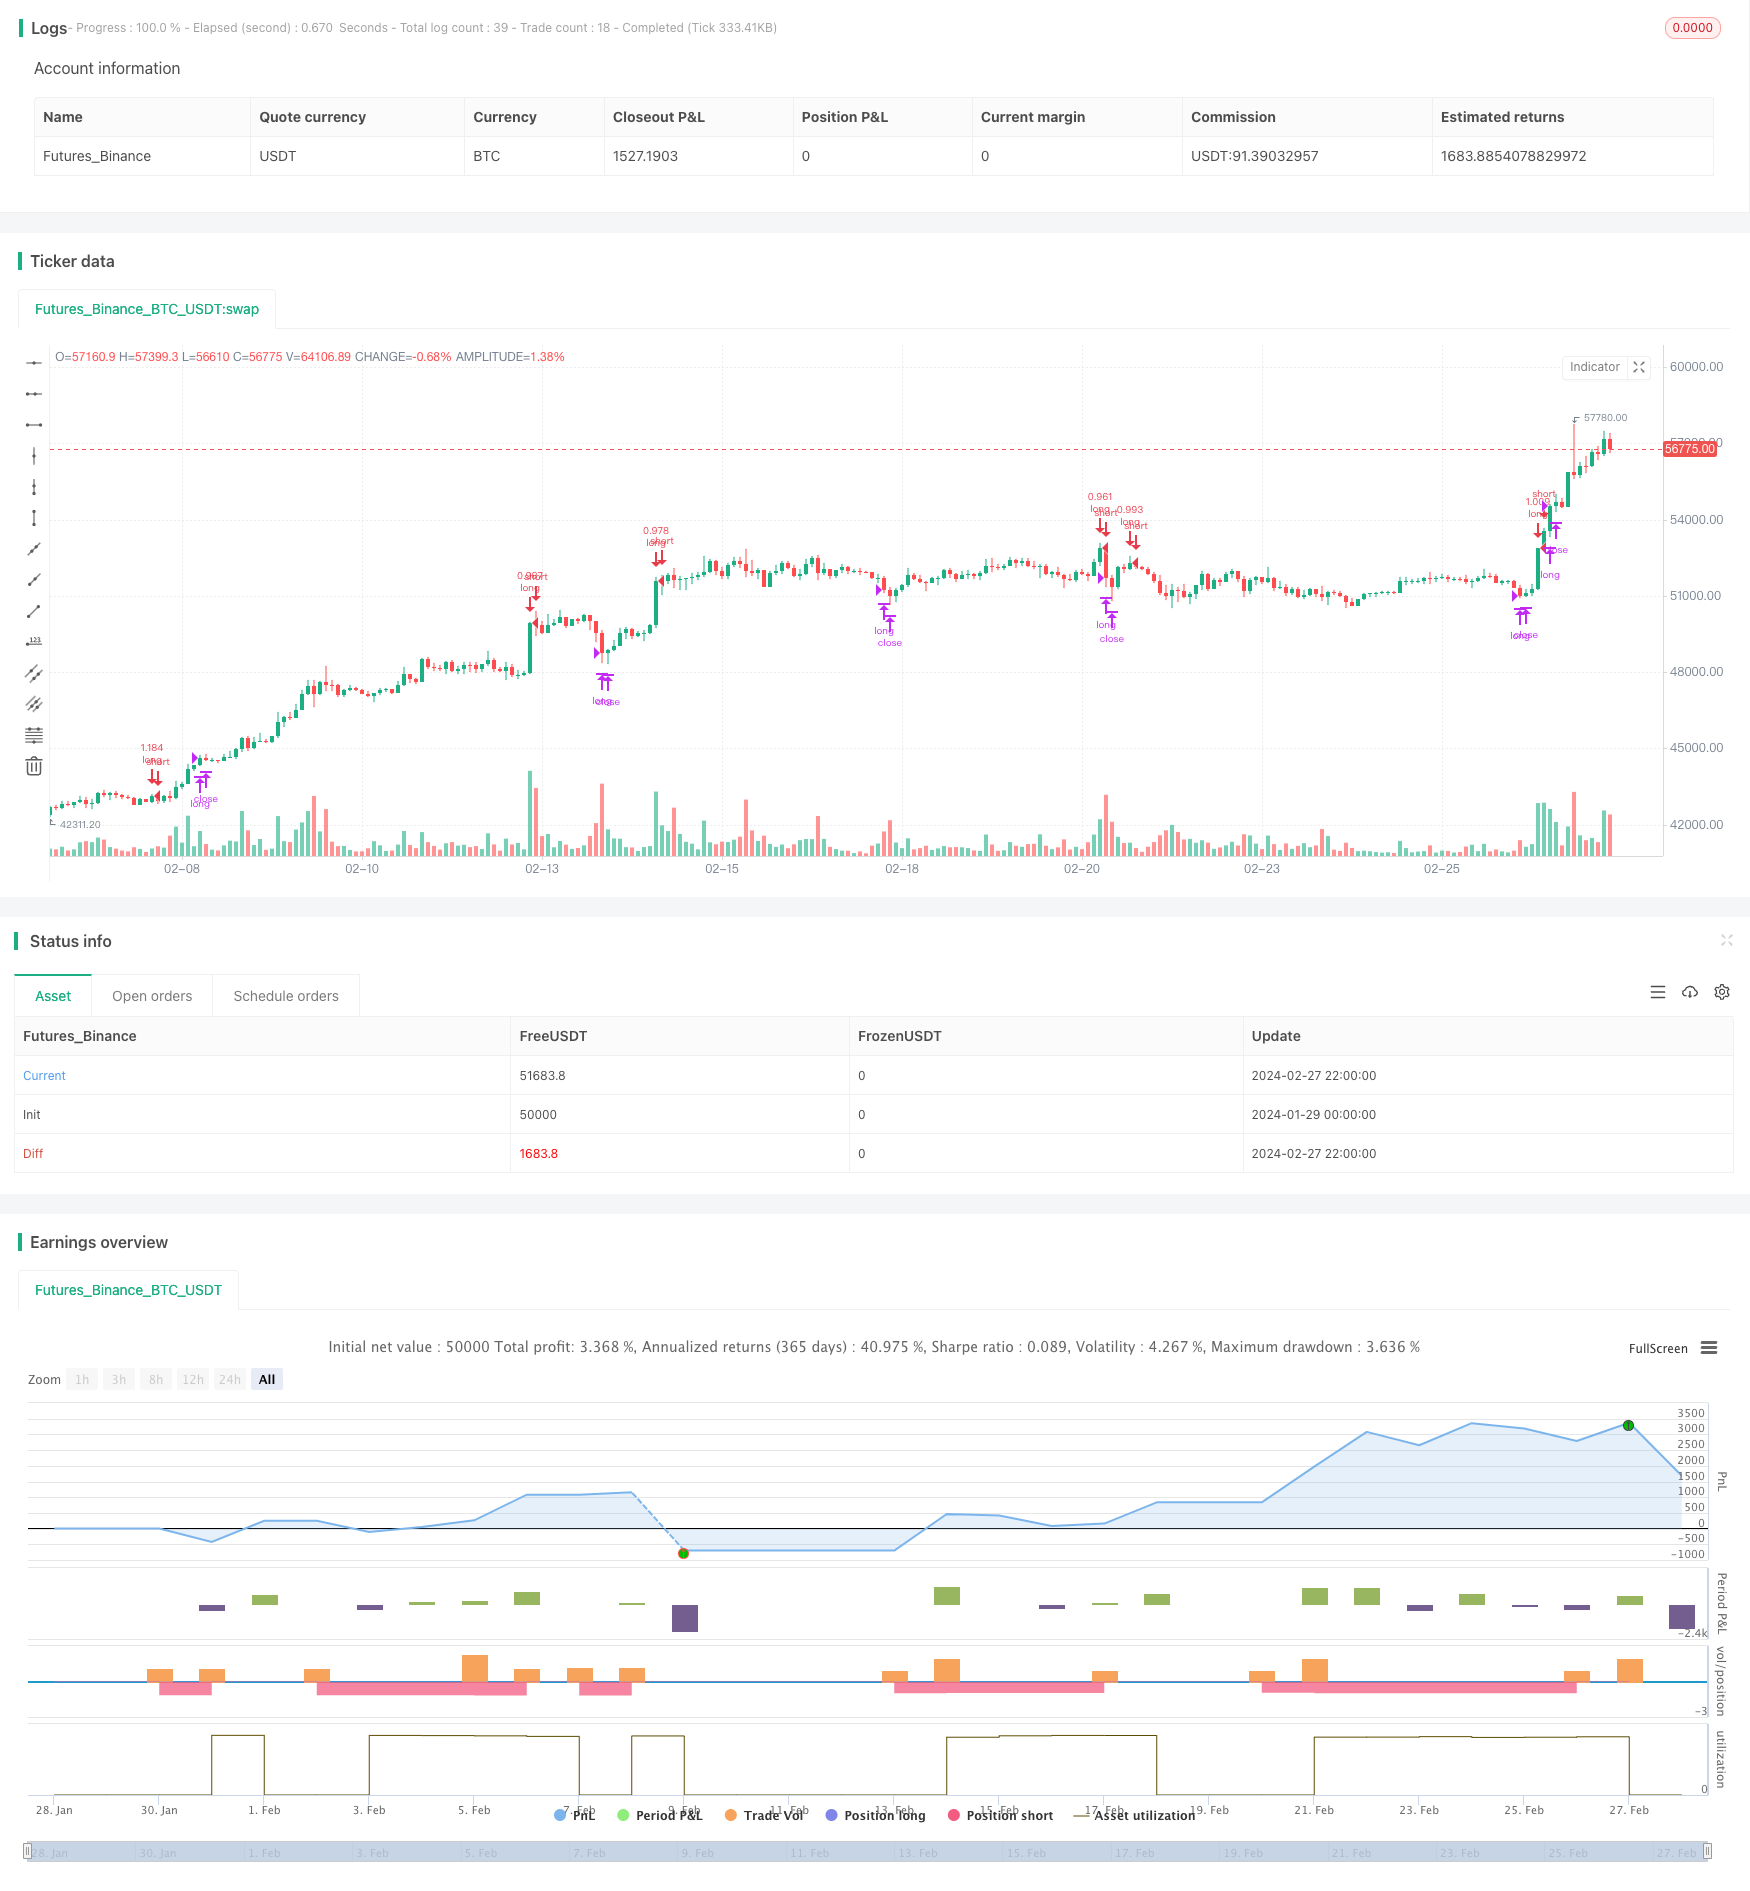
Overview
This strategy combines the MACD momentum indicator and the DMI trend indicator to go long when conditions are met. Its exits set a fixed take profit and a custom volatility trailing stop to lock in profits.
Principles
The entries of this strategy rely on the MACD and DMI indicators:
- When MACD is positive (MACD line above Signal line), it indicates strengthening upside momentum in the market
- When DI+ is higher than DI- in DMI, it indicates the market is in an uptrend
When both conditions are met at the same time, go long.
There are two standards for position exits:
- Fixed take profit: close price rises to a set percentage for profit taking
- Volatility trailing stop loss: use ATR and recent highest price to calculate a dynamically adjusted stop loss position. This can trailing stop loss according to market volatility
Advantages
- The combination of MACD and DMI can more reliably determine the trend direction of the market and reduce erroneous operations
- The profit taking conditions combine fixed take profit and volatility stop loss, which can flexibly lock in profits
Risks
- Both MACD and DMI may produce false signals, leading to unnecessary losses
- Fixed take profit may prevent profits from being maximized
- The trailing speed of volatility stops may be improperly adjusted, too aggressive or conservative
Optimization Directions
- Consider adding other indicators to filter entry signals, such as using the KDJ indicator to determine whether it is overbought or oversold
- Different parameters can be tested for better take profit and stop loss effects
- Parameters such as moving averages can be adjusted according to specific trading varieties to optimize the system
Summary
This strategy synthesizes multiple indicators to judge market trends and conditions, and intervenes in situations with a relatively large probability of favor. The profit taking conditions have also been optimally designed to ensure a certain profit while considering the flexibility of locking in gains. Through parameter adjustment and further risk management, this strategy can become a stable quantitative trading system.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | From Month |
| v_input_2 | true | From Day |
| v_input_3 | 2021 | From Year |
| v_input_4 | true | Thru Month |
| v_input_5 | true | Thru Day |
| v_input_6 | 2112 | Thru Year |
| v_input_7 | true | Show Date Range |
| v_input_8 | 3 | v_input_8 |
| v_input_9 | 20 | Length |
| v_input_10_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_11 | 2 | vStop Multiplier |
Source Pine Script
/*backtest
start: 2024-01-29 00:00:00
end: 2024-02-28 00:00:00
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
//@version=4
strategy(shorttitle='(MACD + DMI Scalping with Volatility Stop',title='MACD + DMI Scalping with Volatility Stop by (Coinrule)', overlay=true, initial_capital = 100, process_orders_on_close=true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, commission_type=strategy.commission.percent, commission_value=0.1)

// Works better on 3h, 1h, 2h, 4h

//Backtest dates
fromMonth = input(defval = 1,    title = "From Month",      type = input.integer, minval = 1, maxval = 12)
fromDay   = input(defval = 1,    title = "From Day",        type = input.integer, minval = 1, maxval = 31)
fromYear  = input(defval = 2021, title = "From Year",       type = input.integer, minval = 1970)
thruMonth = input(defval = 1,    title = "Thru Month",      type = input.integer, minval = 1, maxval = 12)
thruDay   = input(defval = 1,    title = "Thru Day",        type = input.integer, minval = 1, maxval = 31)
thruYear  = input(defval = 2112, title = "Thru Year",       type = input.integer, minval = 1970)

showDate  = input(defval = true, title = "Show Date Range", type = input.bool)

start     = timestamp(fromYear, fromMonth, fromDay, 00, 00)        // backtest start window
finish    = timestamp(thruYear, thruMonth, thruDay, 23, 59)        // backtest finish window
window()  => true

// DMI and MACD inputs and calculations

[pos_dm, neg_dm, avg_dm] = dmi(14, 14)
[macd, macd_signal, macd_histogram] = macd(close, 12, 26, 9)


Take_profit= ((input (3))/100)

longTakeProfit = strategy.position_avg_price * (1 + Take_profit)

length = input(20, "Length", minval = 2)
src = input(close, "Source")
factor = input(2.0, "vStop Multiplier", minval = 0.25, step = 0.25)
volStop(src, atrlen, atrfactor) =>
    var max     = src
    var min     = src
    var uptrend = true
    var stop    = 0.0
    atrM        = nz(atr(atrlen) * atrfactor, tr)
    max         := max(max, src)
    min         := min(min, src)
    stop        := nz(uptrend ? max(stop, max - atrM) : min(stop, min + atrM), src)
    uptrend     := src - stop >= 0.0
    if uptrend != nz(uptrend[1], true)
        max    := src
        min    := src
        stop   := uptrend ? max - atrM : min + atrM
    [stop, uptrend]

[vStop, uptrend] = volStop(src, length, factor)


closeLong = close > longTakeProfit or crossunder(close, vStop)


//Entry
strategy.entry(id="long", long = true, when = crossover(macd, macd_signal) and pos_dm > neg_dm and window())


//Exit
strategy.close("long", when = closeLong and window())
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-and-Moving-Average-Combination-Long-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Multi MA Trend Strength Capture with Momentum Profit Taking StrategyPine Script · Momentum · 2h
- Three Line Strike Momentum Trend Following Strategy with ADX FilterPine Script · Momentum · 1h
- Dynamic Momentum Weighted Moving Average Crossover StrategyPine Script · Momentum · 1h
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Dynamic Trend Momentum Crossover Strategy Quantitative Trading System Based on Dual EMA and MACD IndicatorsPine Script · Momentum · 1h