Momentum Breakout Strategy 439064
This strategy is a trend following strategy that utilizes the price momentum indicator. It judges the market trend by calculating the closing price change over a certain period and makes corresponding long or short…
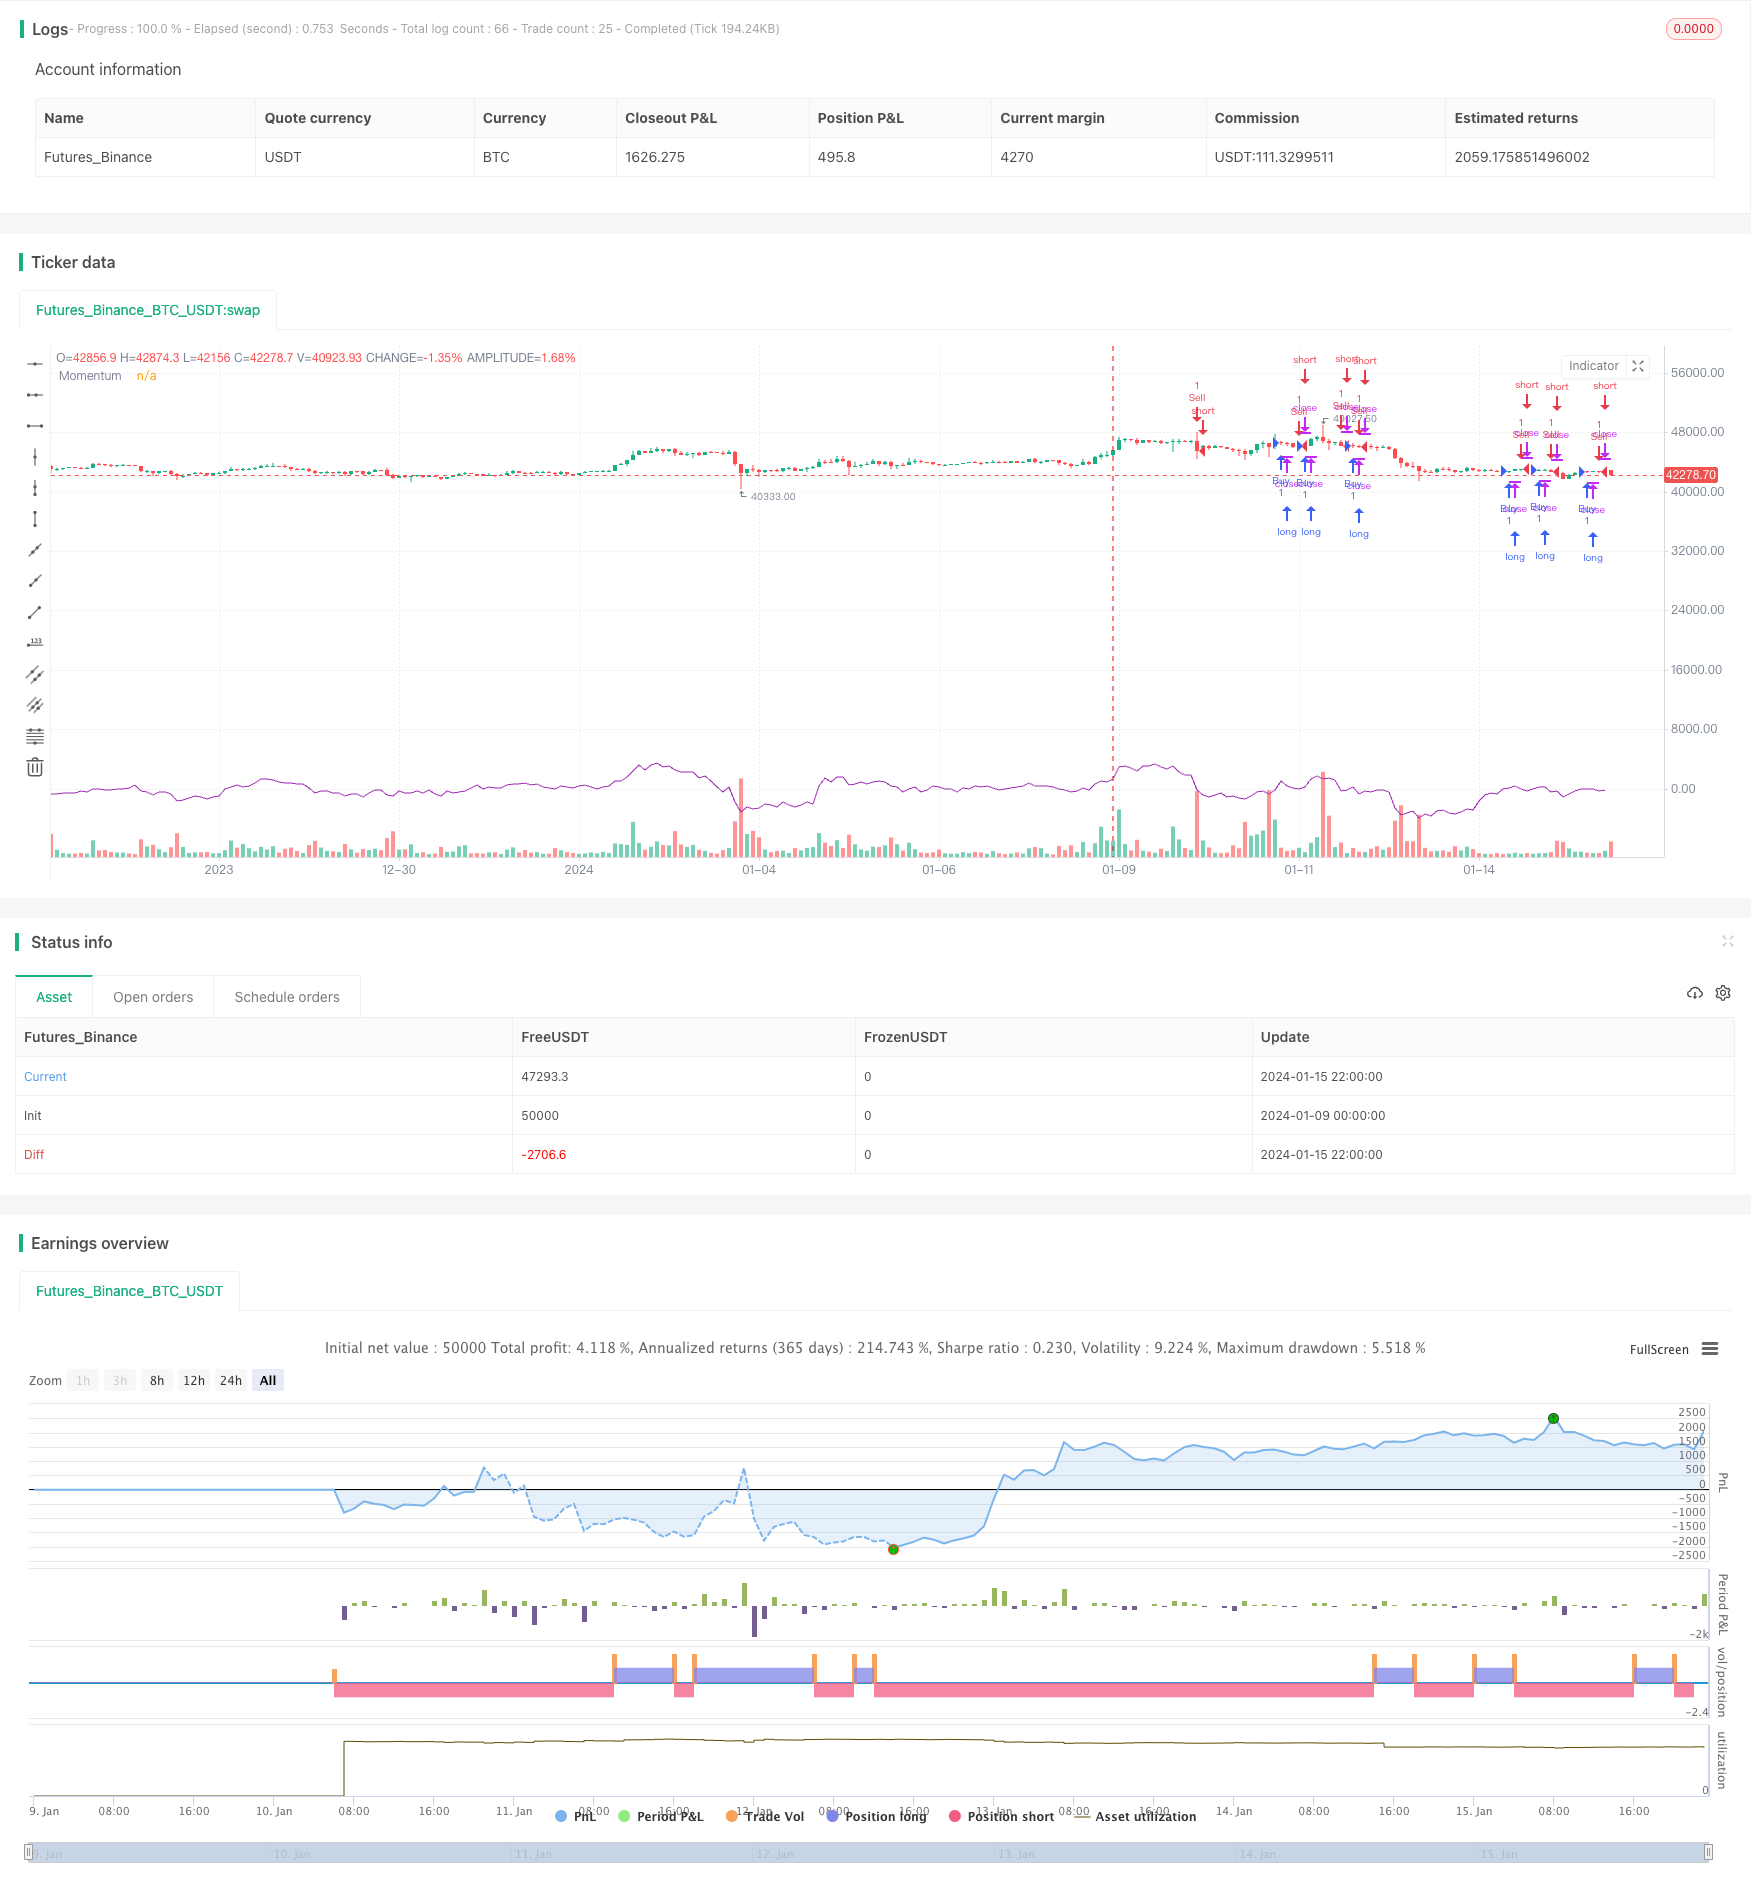
Overview
This strategy is a trend following strategy that utilizes the price momentum indicator. It judges the market trend by calculating the closing price change over a certain period and makes corresponding long or short entries when there is a persistent upward or downward price trend.
Strategy Logic
The core indicator of this strategy is price momentum. The momentum is calculated as:
momentum = close - close[n]
where n represents the length of the momentum period. When momentum > 0, it means that the price has been rising during the current period. When momentum < 0, it means the price has been falling over the current period.
The strategy first sets a confirmBars parameter, which represents the number of candlesticks needed for the trend judgment before executing trades. Within the backtest range, if momentum > 0 persists for confirmBars candlesticks, a long entry is made. If momentum < 0 persists for confirmBars candlesticks, a short entry is made.
The key to the strategy's trend judgment lies in counting the number of consecutive candlesticks where momentum is greater than or less than 0, which is accomplished through the bcount and scount variables. They are incremented by 1 when the corresponding condition is met and reset to 0 when the condition is not met. When the count reaches confirmBars, the corresponding long or short trade is executed.
Strategy Advantages
This is a relatively simple trend following strategy with the following advantages:
- Simple logic that is easy to understand and implement
- The momentum indicator is sensitive to price changes and can quickly capture trends
- Customizable parameters to adjust judgment sensitivity
- Can be used in various market environments
Strategy Risks
The strategy also has some risks:
- Prone to multiple oscillating trades and overtrading
- Reasonable parameter configuration is needed, especially confirmBars to filter oscillations
- Cannot effectively cope with the impact of sudden market events
- Differences between backtest and live trading, data and parameter optimization needed
Strategy Optimization
The strategy can be optimized in several aspects:
- Add stop loss logic to control per trade risk
- Add breakout filters to avoid false signals from price oscillations
- Adjust confirmBars etc. parameters based on different products and market environments
- Incorporate other indicators to confirm entries
- Use machine learning methods to adapt parameters and filters
Summary
In summary, this momentum breakout strategy is a simple and practical trend following strategy suitable as a introductory quant trading strategy. In application, attention is needed to control trade frequency and prevent overtrading. Meanwhile, parameters and filters need to be adjusted and optimized based on actual products and market environments for the strategy to achieve maximum performance.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | confirmBars |
| v_input_2 | 14 | Momentum Length |
| v_input_int_1 | 2019 | Backtest Start Year |
| v_input_int_2 | true | Backtest Start Month |
| v_input_int_3 | true | Backtest Start Day |
| v_input_int_4 | 2023 | Backtest End Year |
| v_input_int_5 | 12 | Backtest End Month |
| v_input_int_6 | 31 | Backtest End Day |
Source Pine Script
/*backtest
start: 2024-01-09 00:00:00
end: 2024-01-16 00:00:00
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Momentum Strategy [TS Trader]", overlay=true)

confirmBars = input(1)
momentumLength = input(14, title="Momentum Length")

price = close
momentum = close - close[momentumLength]

// === INPUT BACKTEST RANGE ===
fromYear = input.int(2019, title="Backtest Start Year")
fromMonth = input.int(1, title="Backtest Start Month", minval=1, maxval=12)
fromDay = input.int(1, title="Backtest Start Day", minval=1, maxval=31)
toYear = input.int(2023, title="Backtest End Year")
toMonth = input.int(12, title="Backtest End Month", minval=1, maxval=12)
toDay = input.int(31, title="Backtest End Day", minval=1, maxval=31)

startTimestamp = timestamp(fromYear, fromMonth, fromDay, 00, 00)
endTimestamp = timestamp(toYear, toMonth, toDay, 23, 59)

inBacktestRange = true

// === STRATEGY LOGIC ===
bcond = momentum > 0
bcount = 0
bcount := bcond ? nz(bcount[1]) + 1 : 0
if (bcount == confirmBars and inBacktestRange)
    strategy.entry("Buy", strategy.long, comment="Long")

scond = momentum < 0
scount = 0
scount := scond ? nz(scount[1]) + 1 : 0
if (scount == confirmBars and inBacktestRange)
    strategy.entry("Sell", strategy.short, comment="Short")

// Plotting Momentum
plot(momentum, title="Momentum", color=color.purple)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Breakout-Strategy-439064.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h