momentum breakout trading strategy 433512
The momentum breakout strategy mainly judges potential reversal signals by identifying bullish engulfing patterns or bearish engulfing patterns to enter the market. After identifying the signal, it quickly tracks the…
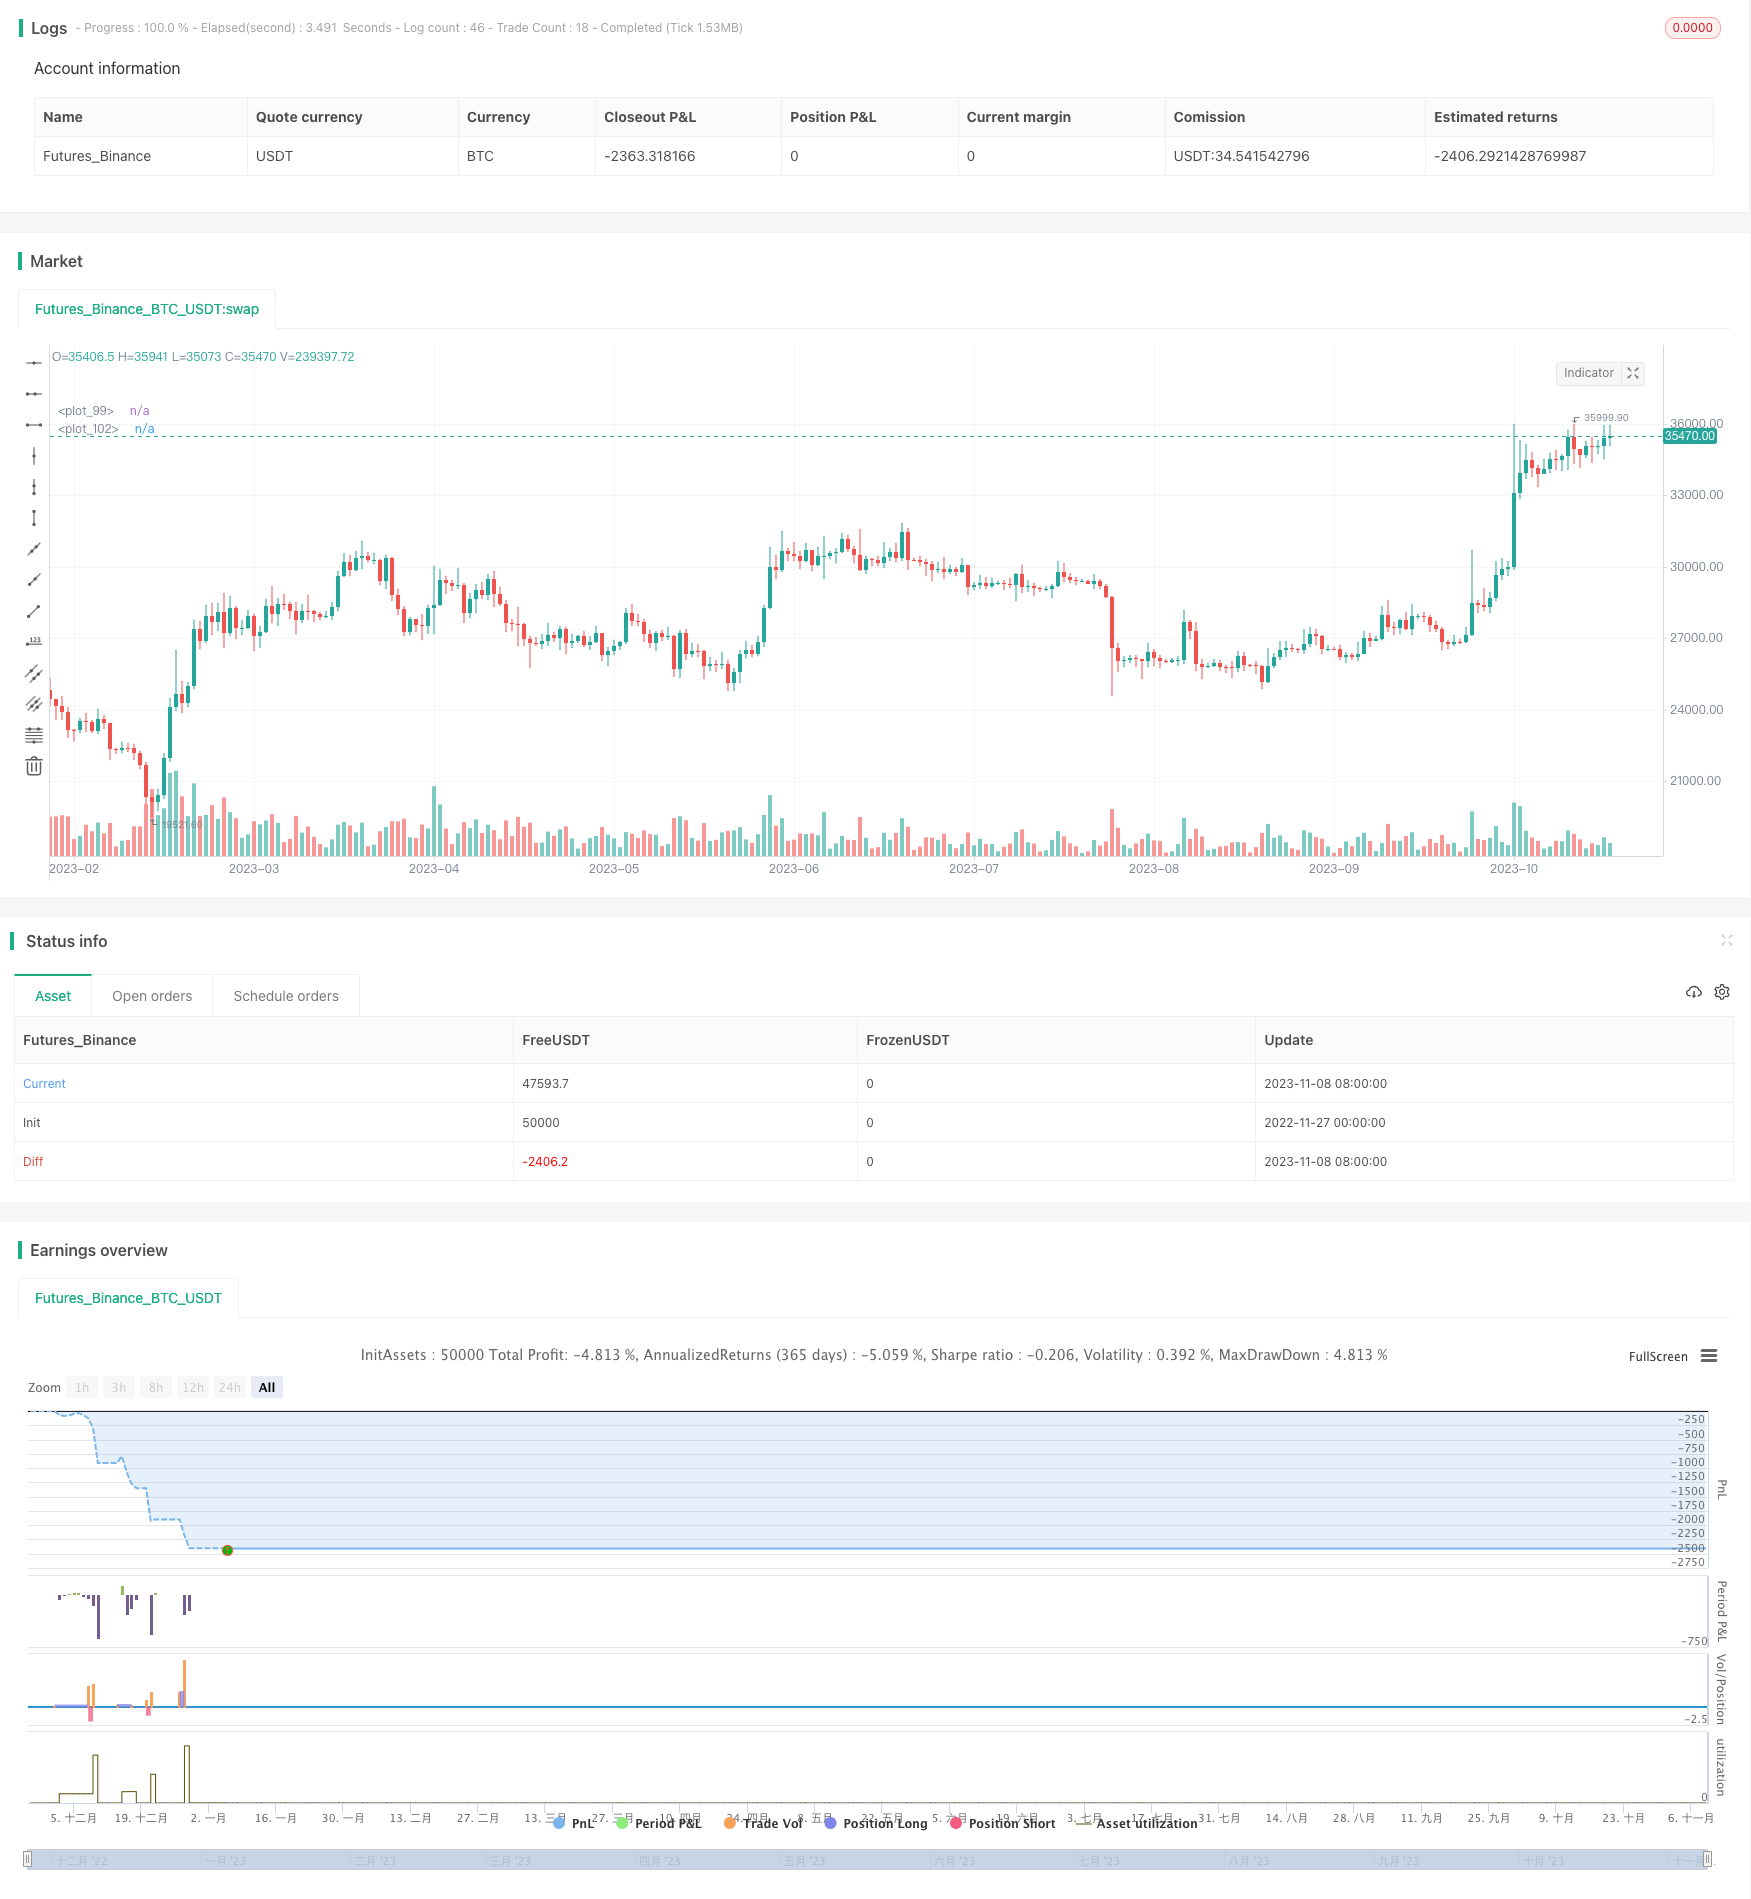
This article introduces a momentum breakout trading strategy based on candlestick patterns. The strategy identifies market trends and entry opportunities by recognizing candlestick formations.
Strategy Overview
The momentum breakout strategy mainly judges potential reversal signals by identifying bullish engulfing patterns or bearish engulfing patterns to enter the market. After identifying the signal, it quickly tracks the trend to achieve excess returns.
Strategy Principle
The core logic of the momentum breakout strategy is based on identifying engulfing patterns, including bullish engulfs and bearish engulfs.
A bullish engulfing pattern forms when the current period's closing price is higher than the opening price, and the previous period's closing price is lower than the previous period's opening price. This pattern often signals a reversal in market sentiment from bearish to bullish, making it a good opportunity to chase the uptrend.
A bearish engulfing pattern forms when the current period's closing price is lower than the opening price, and the previous period's closing price is higher than the previous period's opening price. This also signals a change in market sentiment, providing an opportunity to short the market.
After identifying an engulfing pattern, the momentum breakout strategy quickly establishes a position with excess leverage to track the potential reversal trend. It also dynamically adjusts the stop loss and take profit to control risk while locking in profits.
Advantages
- Quickly identify market reversal opportunities
- Balanced risk-reward ratio with proper stop loss and take profit
- Adjustable leverage catering to different risk appetites
- High efficiency with automated trading
Risks
- Engulfing patterns not fully ensuring reversal
- Probability of failed breakout and sideways price action
- Risk of liquidation from excess leverage
- Requiring sufficient capital to support adequate position sizing
Improvements
The strategy can be optimized in the following ways:
- Incorporate other indicators to filter signals
- Adjust leverage to limit risk
- Scale in to lower cost basis
- Optimize stop loss and take profit to lock in profits
Summary
The momentum breakout strategy is a typical mean-reversion strategy. By capturing key candlestick signals, it quickly judges and tracks market trend reversals. Although risks exist, the strategy can be effectively enhanced through multiple optimization techniques to control the risk-reward ratio. It suits aggressive investors seeking arbitrage-like returns.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2021 | syear |
| v_input_2 | true | smonth |
| v_input_3 | true | sday |
| v_input_4 | 2022 | fyear |
| v_input_5 | 12 | fmonth |
| v_input_6 | 31 | fday |
| v_input_7 | true | longs |
| v_input_8 | true | shorts |
| v_input_9 | 2.5 | rr |
| v_input_10 | true | position_risk_percent |
| v_input_string_1 | 0 | signal_bar_check: 3 | 2 | 1 |
| v_input_11 | 80 | margin_req |
| v_input_12 | 0.2 | sl_increase_factor |
| v_input_13 | false | tp_decrease_factor |
| v_input_14 | true | check_for_volume |
Source Pine Script
/*backtest
start: 2022-11-27 00:00:00
end: 2023-11-09 05:20:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy(title = "MomGulfing", shorttitle = "MomGulfing", overlay = true, initial_capital=10000, pyramiding=3, calc_on_order_fills=false, calc_on_every_tick=false, currency="USD", default_qty_type=strategy.cash, default_qty_value=1000, commission_type=strategy.commission.percent, commission_value=0.04)

syear = input(2021)
smonth = input(1)
sday = input(1)
fyear = input(2022)
fmonth = input(12)
fday = input(31)
start = timestamp(syear, smonth, sday, 01, 00)
finish = timestamp(fyear, fmonth, fday, 23, 59)
date = time >= start and time <= finish ? true : false

longs = input(true)
shorts = input(true)
rr = input(2.5)
position_risk_percent = input(1)/100
signal_bar_check = input.string(defval="3", options=["1", "2", "3"])
margin_req = input(80)
sl_increase_factor = input(0.2)
tp_decrease_factor = input(0.0)
check_for_volume = input(true)
var long_sl = 0.0
var long_tp = 0.0
var short_sl = 0.0
var short_tp = 0.0
var long_lev = 0.0
var short_lev = 0.0

initial_capital = strategy.equity
position_risk = initial_capital * position_risk_percent

bullishEngulfing_st = close[1] < open[1] and close > open and high[1] < close and (check_for_volume ? volume[1]<volume : true)
bullishEngulfing_nd = close[2] < open[2] and close[1] > open[1] and close > open and high[2] > close[1] and high[2] < close and (check_for_volume ? volume[2]<volume : true)
bullishEngulfing_rd = close[3] < open[3] and close[2] > open[2] and close[1] > open[1] and close > open and high[3] > close[2] and high[3] > close[1] and high[3] < close and (check_for_volume ? volume[3]<volume : true)
bullishEngulfing = signal_bar_check == "1" ? bullishEngulfing_st : signal_bar_check == "2" ? bullishEngulfing_st or bullishEngulfing_nd : bullishEngulfing_st or bullishEngulfing_nd or bullishEngulfing_rd
long_stop_level = bullishEngulfing_st ? math.min(low[1], low) : bullishEngulfing_nd ? math.min(low[2], low[1], low) : bullishEngulfing_rd ? math.min(low[3], low[2], low[1], low) : na
rr_amount_long = close-long_stop_level
long_exit_level = close + rr*rr_amount_long
long_leverage = math.floor(margin_req/math.floor((rr_amount_long/close)*100))

bearishEngulfing_st = close[1] > open[1] and close < open and low[1] > close and (check_for_volume ? volume[1]<volume : true)
bearishEngulfing_nd = close[2] > open[2] and close[1] < open[1] and close < open and low[2] < close[1] and low[2] > close and (check_for_volume ? volume[2]<volume : true)
bearishEngulfing_rd = close[3] > open[3] and close[2] < open[2] and close[1] < open[1] and close < open and low[3] < close[2] and low[3] < close[1] and low[3] > close and (check_for_volume ? volume[3]<volume : true)
bearishEngulfing = signal_bar_check == "1" ? bearishEngulfing_st : signal_bar_check == "2" ? bearishEngulfing_st or bearishEngulfing_nd : bearishEngulfing_st or bearishEngulfing_nd or bearishEngulfing_rd
short_stop_level = bearishEngulfing_st ? math.max(high[1], high) : bearishEngulfing_nd ? math.max(high[2], high[1], high) : bearishEngulfing_rd ? math.max(high[3], high[2], high[1], high) : na
rr_amount_short = short_stop_level-close
short_exit_level = close - rr*rr_amount_short
short_leverage = math.floor(margin_req/math.floor((rr_amount_short/short_stop_level)*100))

long = longs and date and bullishEngulfing
short = shorts and date and bearishEngulfing
bgcolor(long[1] ? color.new(color.teal, 80) : (short[1] ? color.new(color.purple, 80) : na))

if long and strategy.position_size <= 0
    long_lev := long_leverage

if short and strategy.position_size >= 0
    short_lev := short_leverage

long_pos_size = long_lev * position_risk
long_pos_qty = long_pos_size/close
short_pos_size = short_lev * position_risk
short_pos_qty = short_pos_size/close

if long
    if strategy.position_size <= 0
        long_sl := long_stop_level
        long_tp := long_exit_level

    else if strategy.position_size > 0
        long_sl := long_stop_level + sl_increase_factor*rr_amount_long
        long_tp := long_exit_level - tp_decrease_factor*rr_amount_long

    strategy.entry("L"+str.tostring(long_lev)+"X", strategy.long, qty=long_pos_qty)
    label_text = str.tostring(long_lev)+"X\nSL:"+str.tostring(long_sl)+"\nTP:"+str.tostring(long_tp)
    label.new(bar_index+1, na, text=label_text, color=color.green, style=label.style_label_up, xloc=xloc.bar_index, yloc=yloc.belowbar)

else if short
    if strategy.position_size >= 0
        short_sl := short_stop_level
        short_tp := short_exit_level

    else if strategy.position_size < 0
        short_sl := short_stop_level - sl_increase_factor*rr_amount_short
        short_tp := short_exit_level + tp_decrease_factor*rr_amount_short

    strategy.entry("S"+str.tostring(short_lev)+"X", strategy.short, qty=short_pos_qty)
    label_text = str.tostring(short_lev)+"X\nSL:"+str.tostring(short_sl)+"\nTP:"+str.tostring(short_tp)
    label.new(bar_index+1, na, text=label_text, color=color.red, style=label.style_label_down, xloc=xloc.bar_index, yloc=yloc.abovebar)

if (strategy.position_size > 0)
    strategy.exit(id="L TP/SL", stop=long_sl, limit=long_tp)

if (strategy.position_size < 0)
    strategy.exit(id="S TP/SL", stop=short_sl, limit=short_tp)

sl_level = strategy.position_size > 0 ? long_sl : strategy.position_size < 0 ? short_sl : na
plot(sl_level, color=color.red, style=plot.style_linebr)

tp_level = strategy.position_size > 0 ? long_tp : strategy.position_size < 0 ? short_tp : na
plot(tp_level, color=color.green, style=plot.style_linebr)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/momentum-breakout-trading-strategy-433512.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h