Momentum Exponential Moving Average Crossover Trading Strategy
This strategy generates trading signals based on the crossover and crossunder between two Exponential Moving Averages (EMAs), specifically the 50-period EMA and 200-period EMA. It aims to capture changes in…
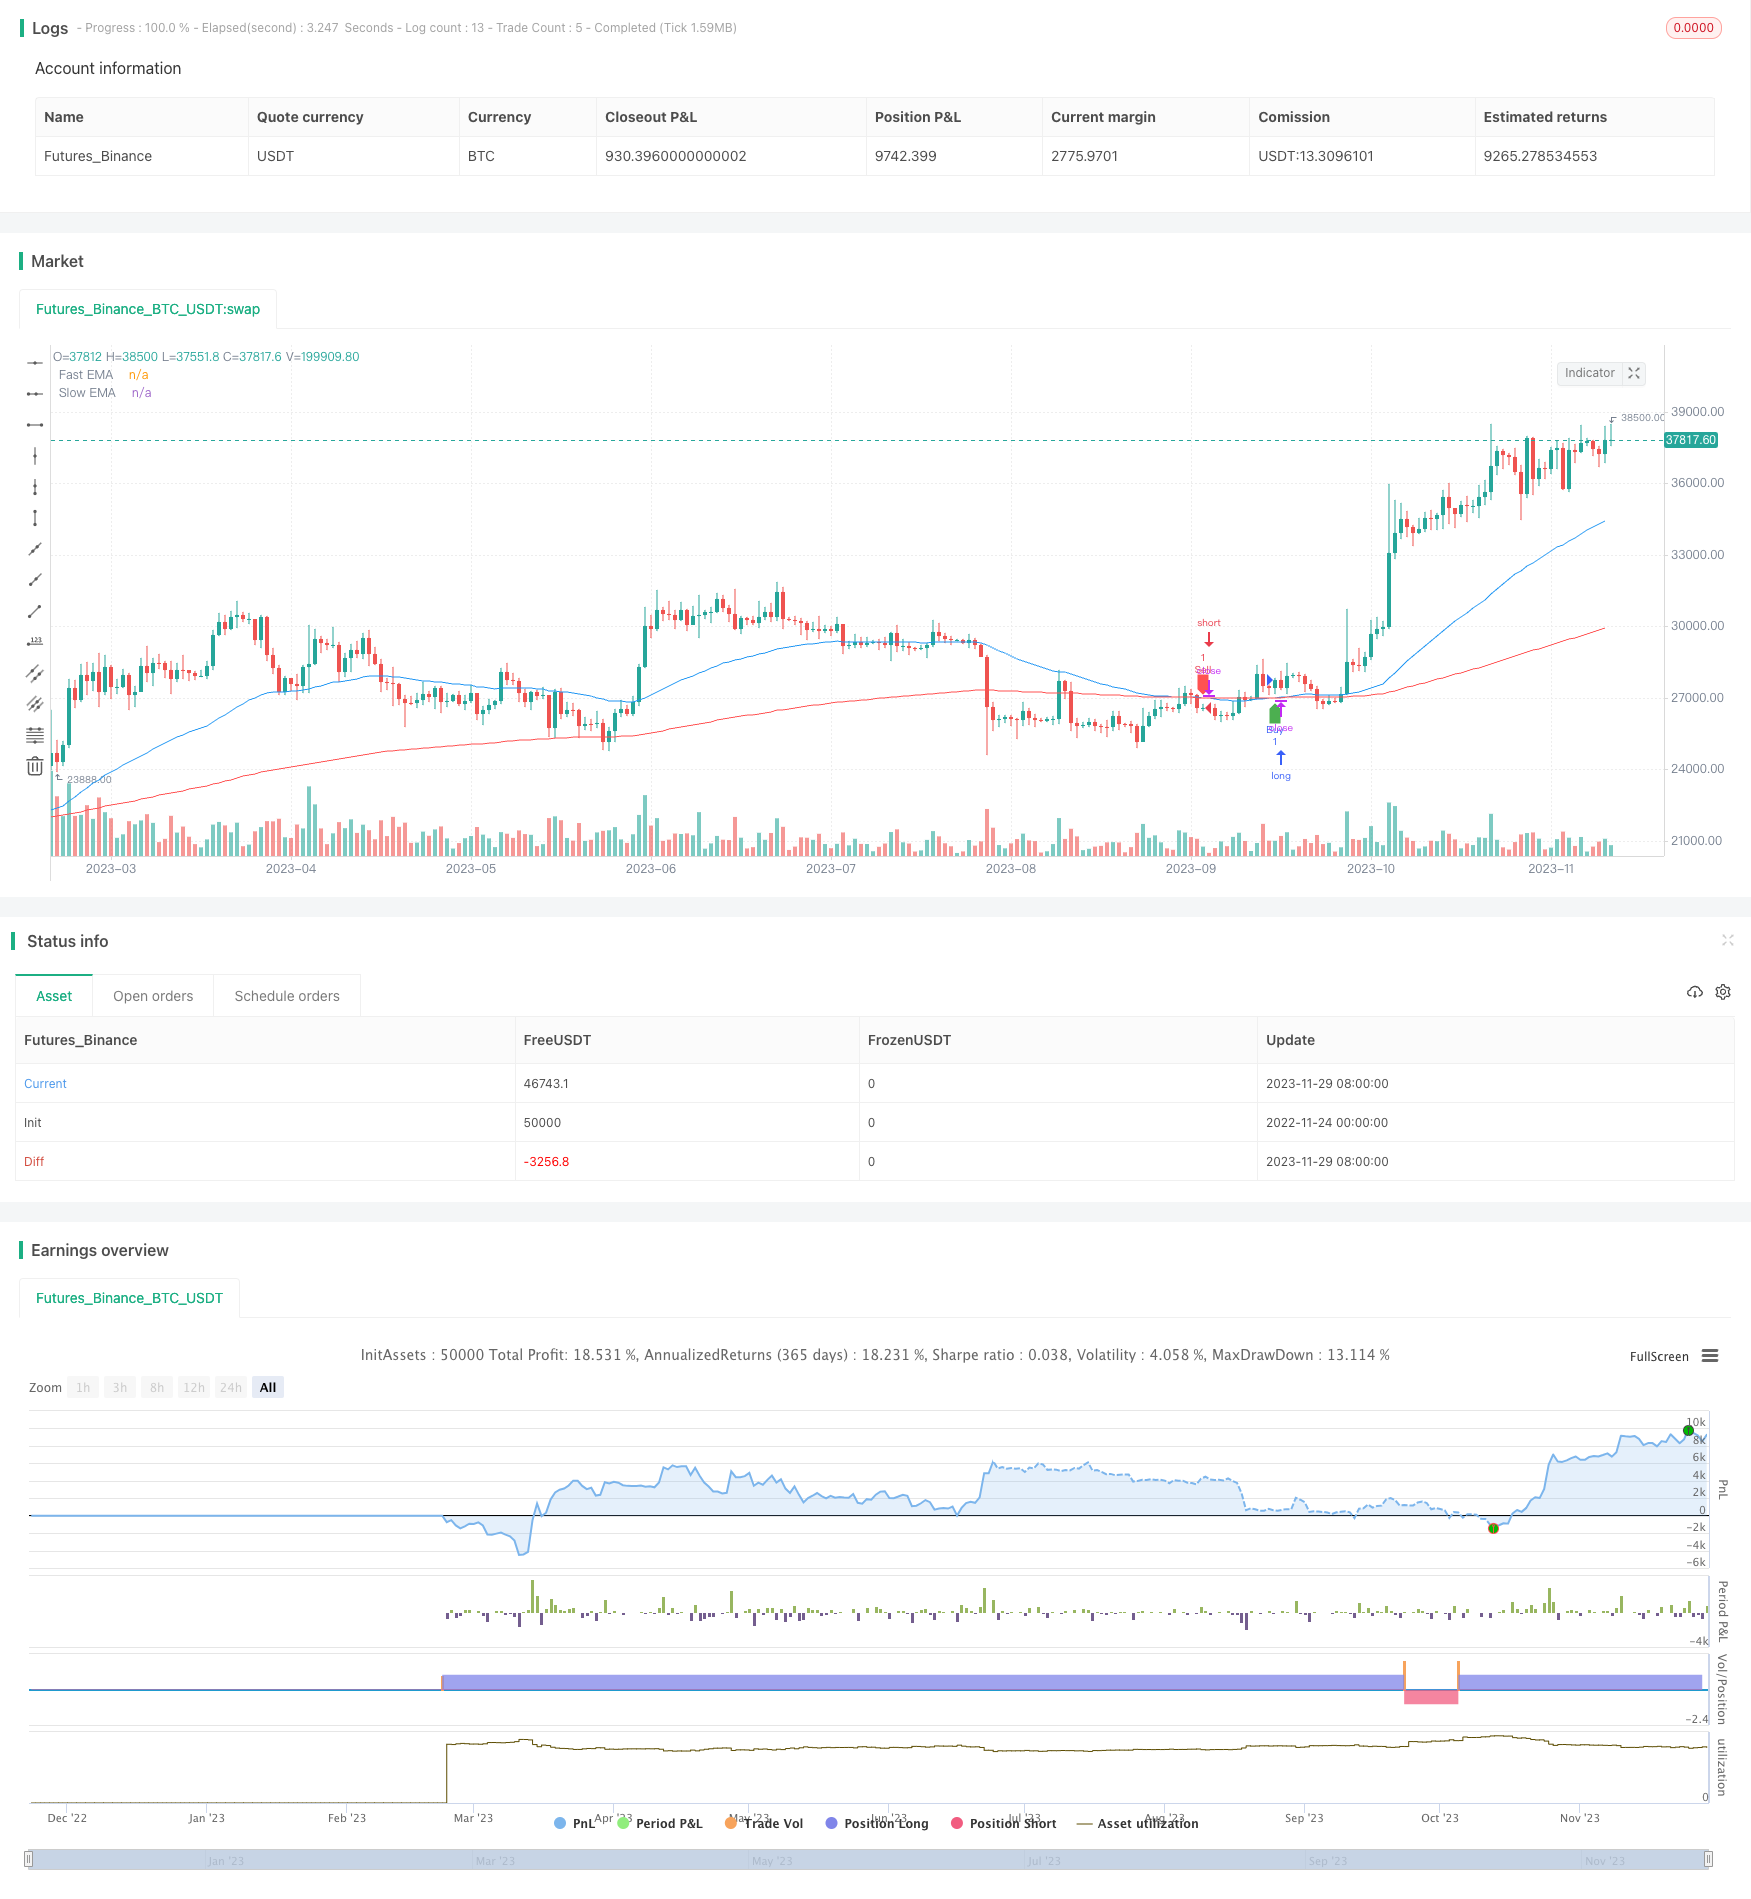
Overview
This strategy generates trading signals based on the crossover and crossunder between two Exponential Moving Averages (EMAs), specifically the 50-period EMA and 200-period EMA. It aims to capture changes in short-term and long-term price trends to form a momentum-based trading strategy.
Strategy Logic
Calculate two EMAs: 50-period EMA and 200-period EMA. EMAs give more weight to recent data and are more responsive to short-term price moves.
Determine trading signals:
- Buy signal: 50-period EMA crosses above 200-period EMA, indicating the short-term trend is turning upwards.
- Sell signal: 50-period EMA crosses below 200-period EMA, indicating the short-term trend is turning downwards.
Execute trades based on signals: Go long on buy signals, go short on sell signals.
Plot EMAs and trading signals on chart for intuitive visualization.
Advantages
The strategy has the following key advantages:
Captures major trend reversals, works well for trending and ranging markets.
Simple and clear decision rules, easy to implement and backtest.
EMAs smooth price data, help identify signals and filter out noise.
Customizable EMA periods suit different holding horizons.
Can combine other indicators to further filter signals and optimize.
Risks Analysis
There are also some risks to consider:
More false signals and excessive trades possible in choppy markets.
Relies solely on single indicator rules, robustness could improve.
No stop loss in place, risks uncontrolled losing trades.
EMA lag may miss best entry and exit points.
Requires backtesting to find optimal parameters, live results may differ.
Corresponding risk control and optimizations include using other indicators as filters, implementing stop losses, introducing machine learning models etc.
Optimization Opportunities
Some ways the strategy can be further optimized:
Add other indicators (e.g. MACD, RSI) for a multi-factor model. Improves robustness.
Incorporate stop losses. E.g. fixed percentage, trailing stop loss. Limits maximum loss per trade.
Utilize machine learning for optimal parameters and enhance signal generation rules.
Backtest to find best performing EMA combinations for market regime. Dynamically adjust periods.
Evaluate transaction costs. Add slippage, commission to fine tune position sizing.
Conclusion
This is an overall simple, classic breakout strategy based on EMA crossovers. Has merits but also some inherent flaws and room for improvement. Enhancing signal reliability, risk control, dynamic adjustment etc. will greatly improve its profitability in live trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 50 | Fast EMA Length |
| v_input_2 | 200 | Slow EMA Length |
Source Pine Script
/*backtest
start: 2022-11-24 00:00:00
end: 2023-11-30 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("EMA Golden Crossover Strategy", overlay=true)

// Input parameters
fastLength = input(50, title="Fast EMA Length")
slowLength = input(200, title="Slow EMA Length")

// Calculate EMAs using ta.ema
fastEMA = ta.ema(close, fastLength)
slowEMA = ta.ema(close, slowLength)

// Plot EMAs on the chart
plot(fastEMA, color=color.blue, title="Fast EMA")
plot(slowEMA, color=color.red, title="Slow EMA")

// Strategy logic
longCondition = ta.crossover(fastEMA, slowEMA)
shortCondition = ta.crossunder(fastEMA, slowEMA)

// Execute orders
if (longCondition)
    strategy.entry("Buy", strategy.long)

if (shortCondition)
    strategy.entry("Sell", strategy.short)

// Plot buy and sell signals on the chart
plotshape(series=longCondition, title="Buy Signal", color=color.green, style=shape.labelup, location=location.belowbar)
plotshape(series=shortCondition, title="Sell Signal", color=color.red, style=shape.labeldown, location=location.abovebar)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-01. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Exponential-Moving-Average-Crossover-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- MACD Momentum Indicator Backtest StrategyPine Script · Momentum · 1h
- MoonFlag MACD Momentum StochRSI Trading StrategyPine Script · Momentum · 1d
- Multi Indicator Comprehensive Momentum Trading StrategyPine Script · Momentum · 1d
- Multi Indicator Trend Momentum Trading Strategy with Dynamic Risk Management SystemPine Script · Momentum · 1h