Momentum Indicator Long Short Strategy
This strategy utilizes momentum indicators including Average Directional Index (ADX), Directional Movement Index (DMI) and Commodity Channel Index (CCI) to determine trend direction and follow trends. It enters…
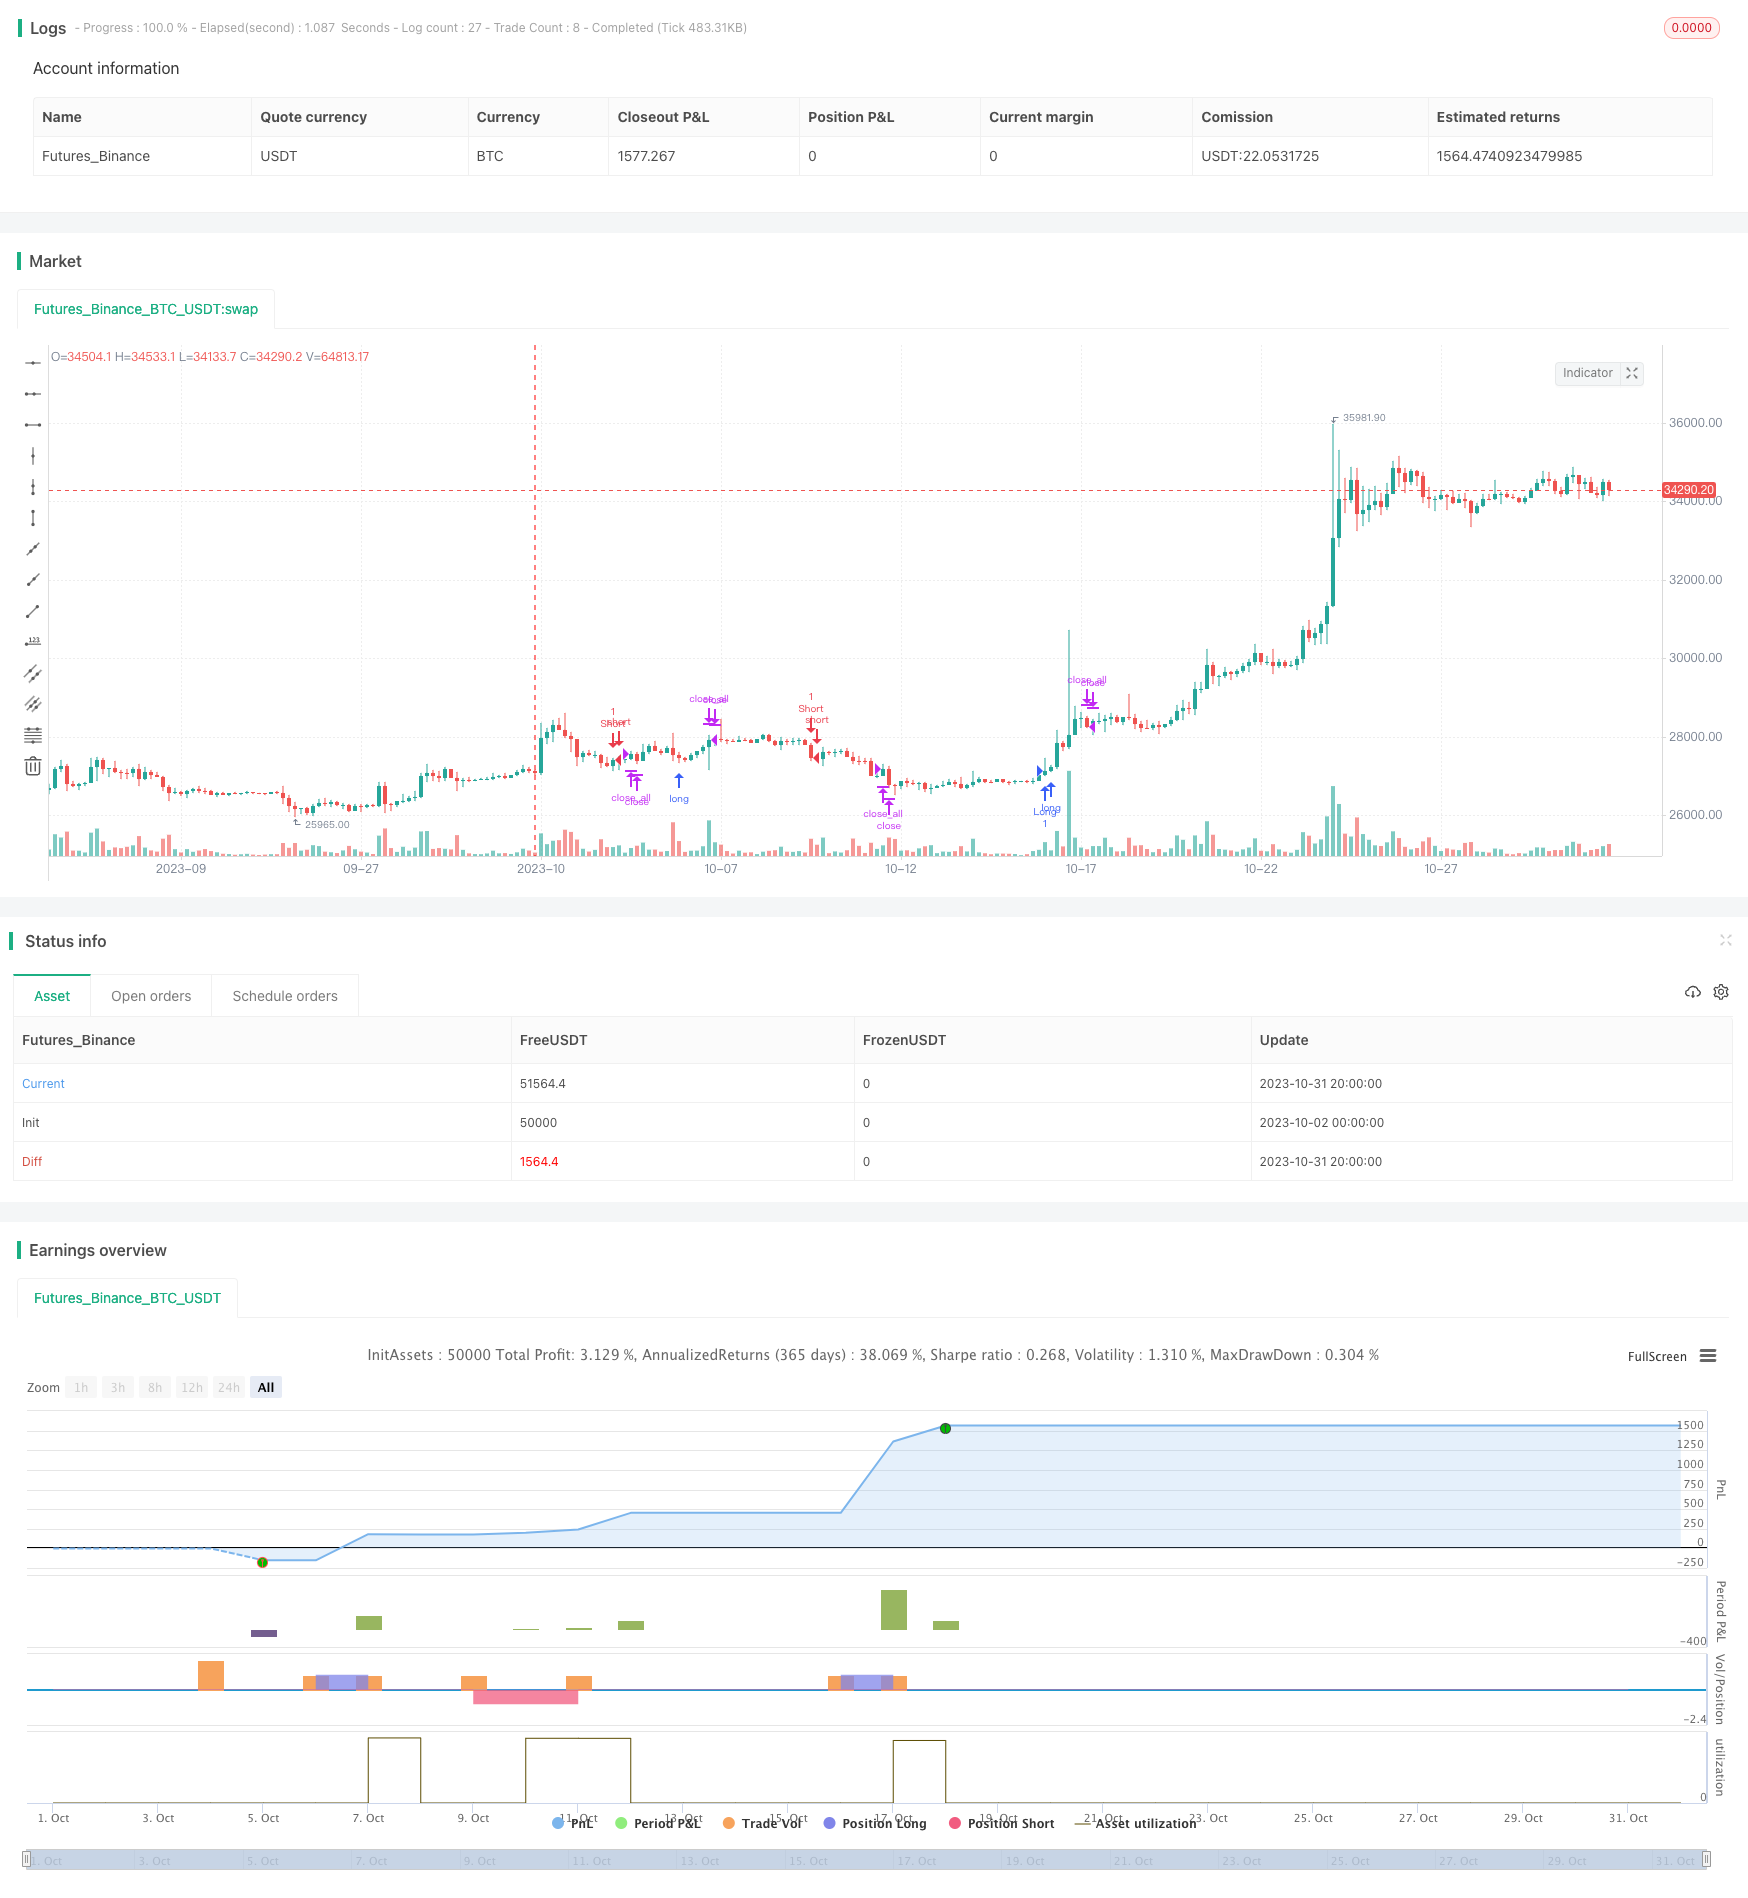
Overview
This strategy utilizes momentum indicators including Average Directional Index (ADX), Directional Movement Index (DMI) and Commodity Channel Index (CCI) to determine trend direction and follow trends. It enters positions when ADX and trend indicators confirm a trend, and CCI is overextended.
Strategy Logic
Calculate ADX, DMI and CCI indicators.
- ADX measures trend strength. A high ADX indicates a strong trend.
- DMI includes DI+ and DI-. DI+ shows uptrend strength while DI- shows downtrend strength. If DI+ is greater than DI-, it's an uptrend, and vice versa.
- CCI judges overbought/oversold levels. Below -100 is oversold while above 100 is overbought.
Determine trend direction.
- When DI+ crosses above DI-, an uptrend is identified.
- When DI- crosses below DI+, a downtrend is identified.
Enter positions.
- When uptrend forms, ADX is high, and CCI < -100, go long.
- When downtrend forms, ADX is high, and CCI > 100, go short.
Exit positions with stop loss.
- When long, exit when DI- crosses below DI+.
- When short, exit when DI+ crosses above DI-.
Advantage Analysis
ADX filters out trading during weak trends.
DMI reduces mistakes in trend identification.
Entering on CCI overextension improves timing and reduces risk.
Combining momentum indicators improves accuracy.
Stop loss limits loss per trade.
Risks and Hedging
Whipsaws when ADX drops. Raise ADX threshold to ensure strong enough trend.
DMI lags trend early stage. Add other analysis to identify opportunity.
High CCI trading frequency. Widen CCI range to filter noise.
Consider market neutral strategy when long and short, to hedge overall position risk.
Optimization Directions
Optimize ADX parameters to balance noise filtering and catching trend.
Optimize DMI parameters to balance lag and sensitivity.
Optimize CCI parameters to balance trading frequency and catching reversals.
Test adding or modifying indicators for better combos. E.g. MACD, KDJ.
Test on different products to find best fit.
Optimize position sizing to control risk while maintaining trend tracking.
Conclusion
The strategy logically uses ADX for trend, DMI for direction and CCI for reversals. But parameters need optimization and position sizing for risk control. Properly tuned and applied to trending products, it can deliver steady returns. Traders should dynamically adjust for changing markets.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 9 | ADX Smoothing |
| v_input_2 | 14 | DI Length |
| v_input_3 | 25 | ADX Entry |
| v_input_4 | 20 | CCI Length |
Source Pine Script
/*backtest
start: 2023-10-02 00:00:00
end: 2023-11-01 00:00:00
period: 4h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("ADX Strategy", currency = "USD", initial_capital = 1000, overlay=true)
adxlen = input(9, title="ADX Smoothing")
dilen = input(14, title="DI Length")
ADX_Entry = input(25, title="ADX Entry")
dirmov(len) =>
	up = change(high)
	down = -change(low)
	truerange = rma(tr, len)
	plus = fixnan(100 * rma(up > down and up > 0 ? up : 0, len) / truerange)
	minus = fixnan(100 * rma(down > up and down > 0 ? down : 0, len) / truerange)
	[plus, minus]

adx(dilen, adxlen) =>
	[plus, minus] = dirmov(dilen)
	sum = plus + minus
	adx = 100 * rma(abs(plus - minus) / (sum == 0 ? 1 : sum), adxlen)
	[adx, plus, minus]

[sig, up, down] = adx(dilen, adxlen)
cci_length = input(20, minval=1, title="CCI Length")
cci_ma = sma(close, cci_length)
cci = (close - cci_ma) / (0.015 * dev(close, cci_length))

stop_loss = syminfo.mintick * 100


open_longs = strategy.position_size > 0
open_shorts = strategy.position_size < 0

possible_bull = false
possible_bull := not open_longs ? (possible_bull[1] and not crossunder(up,down) ? true : false) : false
possible_bear = false
possible_bear := not open_shorts ? (possible_bear[1] and not crossunder(down,up) ? true : false) : false


bool bull_entry = crossover(up,down)

if(bull_entry and up < ADX_Entry and cci < 0)
	possible_bull := true
	bull_entry := false

if(possible_bull and up > ADX_Entry and cci > -100)
	bull_entry := true

bool bear_entry = crossover(down,up)

if(bear_entry and down < ADX_Entry and cci > 0)
	possible_bear := true
	bear_entry := false

if(possible_bear and down >= ADX_Entry and cci < 100)
	bear_entry := true

strategy.entry("Short", strategy.short, qty = 1,comment="Short", stop=high[1] - stop_loss, when = bear_entry)
strategy.entry("Long", strategy.long, qty = 1, comment="Long", stop=low[1] - stop_loss, when = bull_entry )

strategy.close_all(when = (open_shorts and (crossover(up,down) or crossover(sig,down))) or (open_longs and ( crossover(down,up) or crossover(sig, up))))
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Indicator-Long-Short-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Multi MA Trend Strength Capture with Momentum Profit Taking StrategyPine Script · Momentum · 2h
- Dynamic Momentum Weighted Moving Average Crossover StrategyPine Script · Momentum · 1h
- Momentum Indicator Oscillation Threshold Enhanced Trading StrategyPine Script · Momentum · 1d
- Multi Indicator Dynamic Stop Loss Momentum Trend Trading StrategyPine Script · Momentum · 1h
- Oscillator Candles Momentum Trading StrategyPine Script · Momentum · 1h