Momentum Indicator Oscillation Threshold Enhanced Trading Strategy
This strategy is a momentum trading system based on the Commodity Channel Index (CCI), designed to capture trading opportunities in oversold areas by monitoring price deviations from the mean. The strategy uses a…
Overview
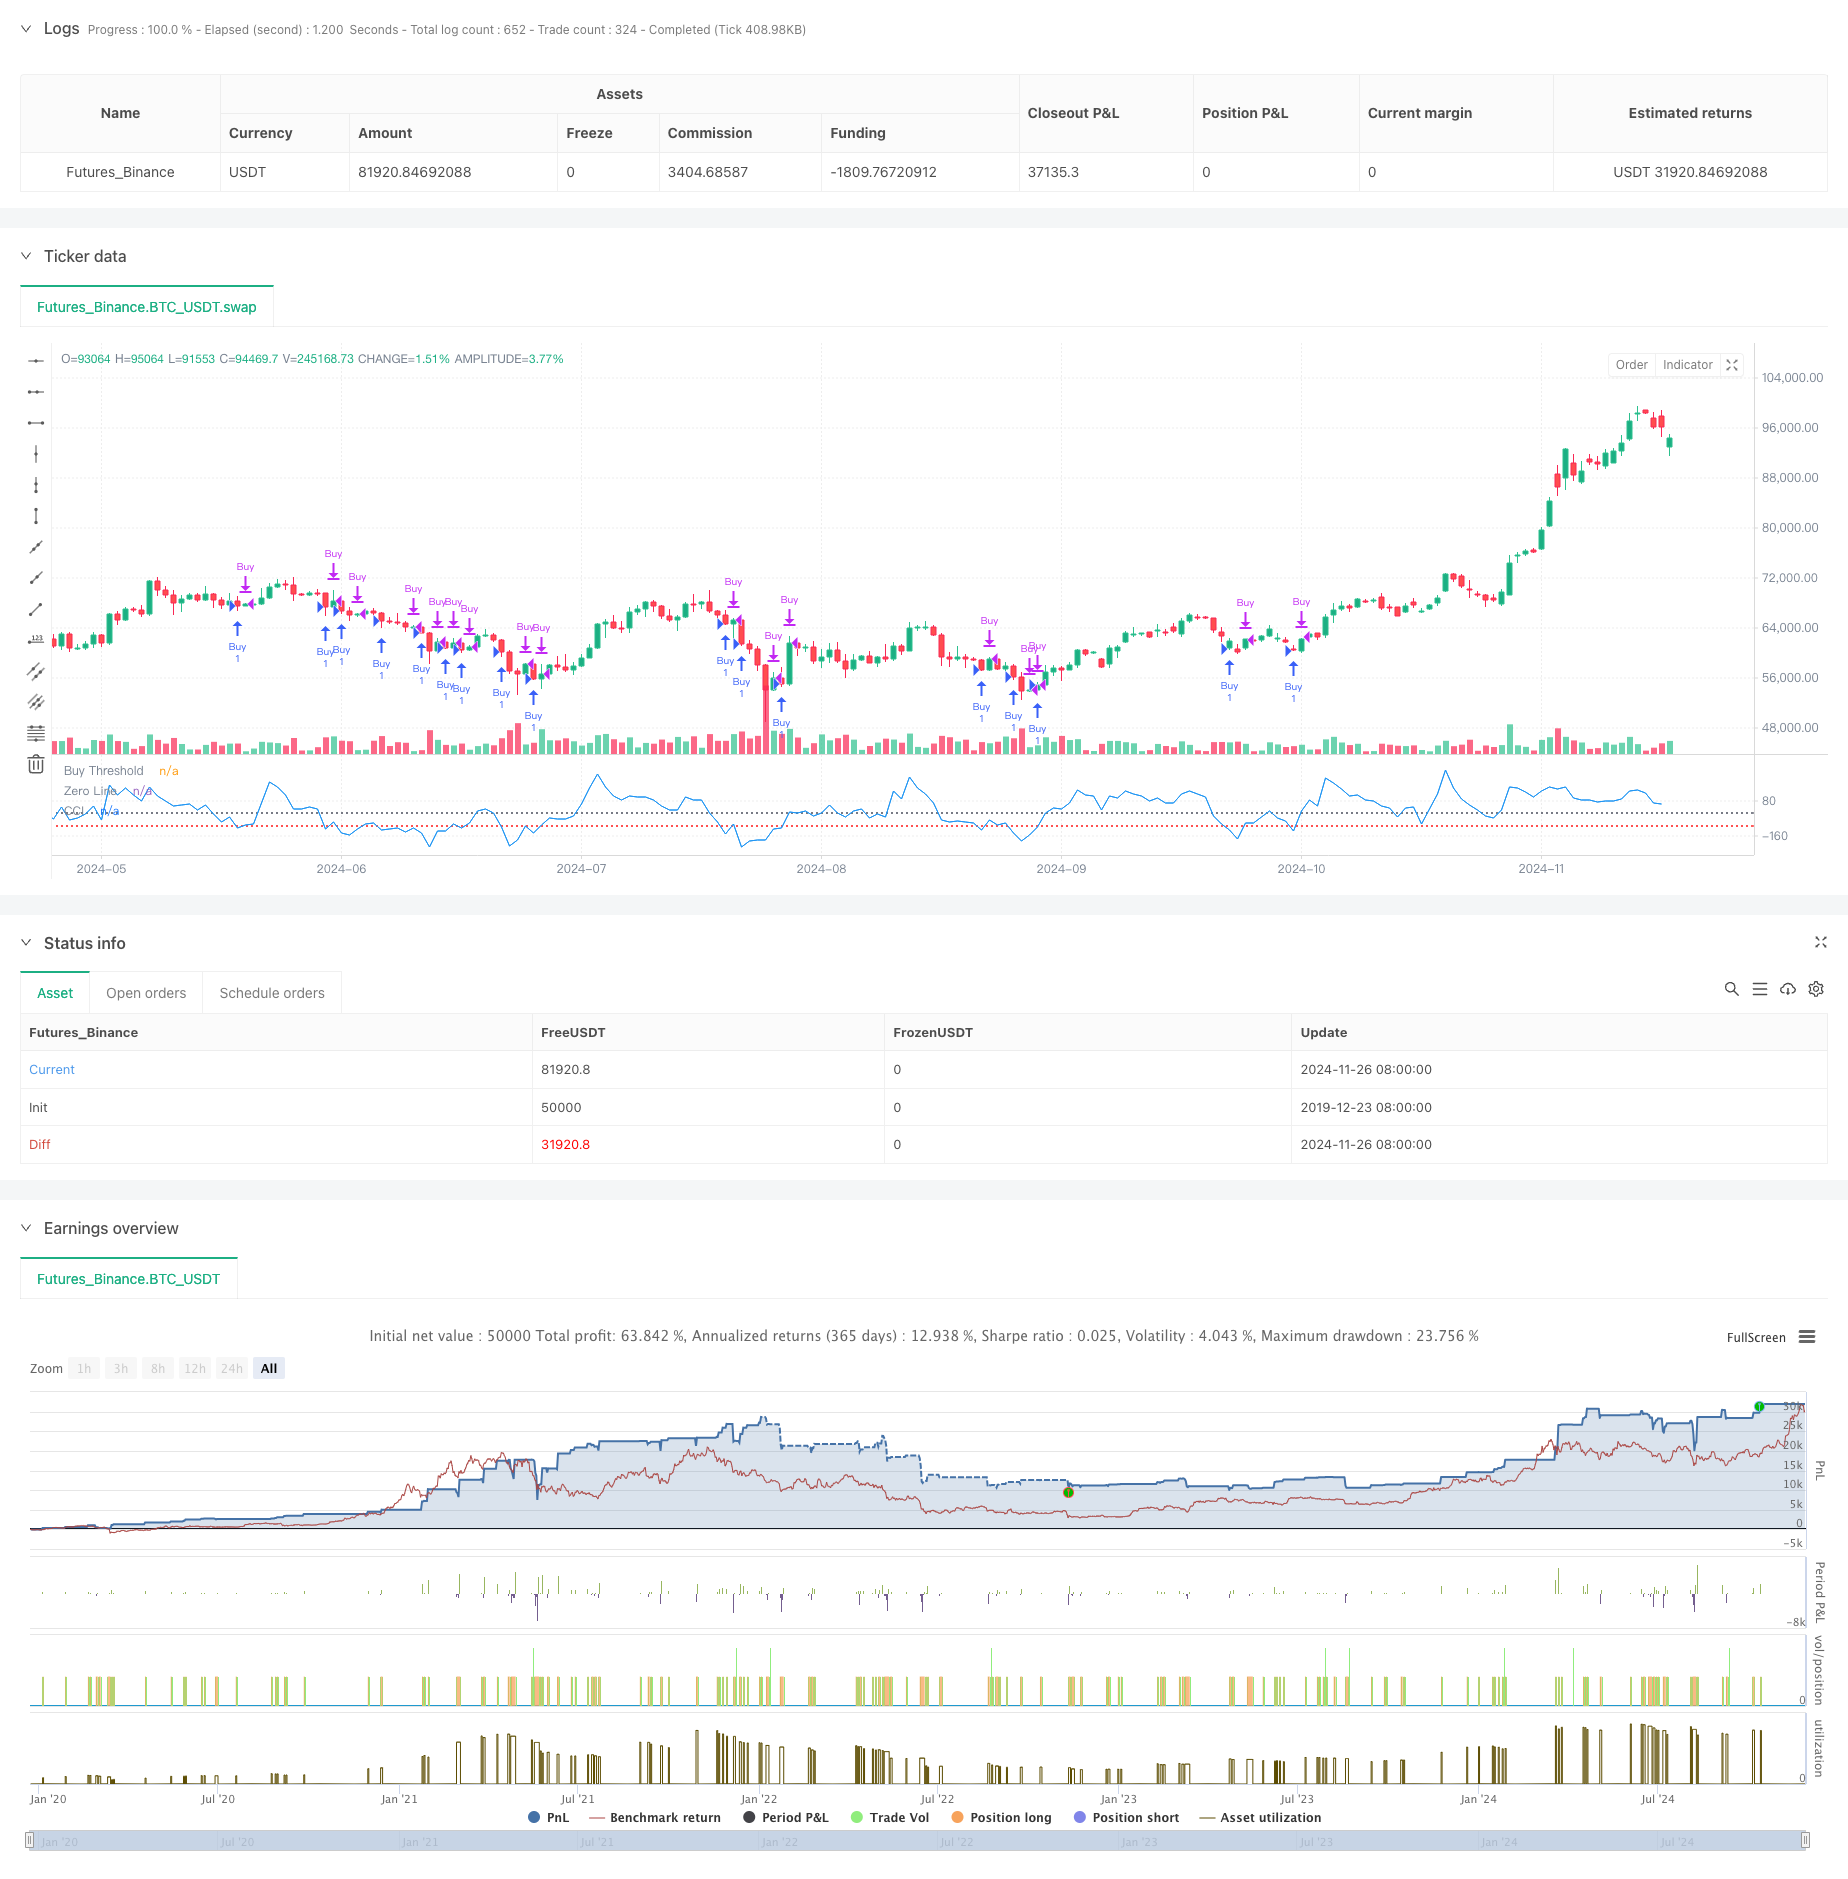
This strategy is a momentum trading system based on the Commodity Channel Index (CCI), designed to capture trading opportunities in oversold areas by monitoring price deviations from the mean. The strategy uses a 12-period lookback, enters long positions when CCI drops below -90 threshold, exits when closing price breaks above previous highs, and includes optional stop-loss and take-profit mechanisms.
Strategy Principles
The core principle utilizes CCI to measure price deviation from its mean. CCI calculation involves: first computing typical price (arithmetic mean of high, low and close prices), then calculating Simple Moving Average (SMA) of typical price, finally deriving CCI by subtracting SMA from typical price, dividing by mean deviation and multiplying by 0.015. Long positions are entered when CCI falls below -90, indicating possible oversold conditions; positions are closed when price breaks above previous highs, confirming upward trend. The strategy offers customizable stop-loss and take-profit parameters to accommodate different risk preferences.
Strategy Advantages
- Clear Signals: Uses fixed CCI thresholds for entry signals, avoiding indecision from subjective judgment
- Controlled Risk: Achieves precise risk control through optional stop-loss and take-profit mechanisms
- Flexible Parameters: Traders can adjust CCI lookback period and entry threshold for different market conditions
- Simple Execution: Clear strategy logic, easy to understand and implement, suitable for all trader types
- Cost Efficient: Event-driven trading approach reduces costs from overtrading
Strategy Risks
- False Breakout Risk: CCI crossing threshold may result in false breakouts leading to unnecessary trades
- Slippage Impact: May face significant slippage losses during high market volatility
- Trend Dependency: Strategy may generate frequent false signals in ranging markets
- Parameter Sensitivity: CCI period and threshold choices significantly impact strategy performance
- Delay Risk: As a lagging indicator, CCI may miss optimal entry points
Strategy Optimization Directions
- Signal Filtering: Additional technical indicators like RSI or MACD can be introduced to filter false signals
- Dynamic Thresholds: Replace fixed CCI thresholds with volatility-based dynamic thresholds
- Time-based Optimization: Adjust strategy parameters based on different time period characteristics
- Money Management: Add dynamic position sizing mechanisms to improve capital efficiency
- Multi-timeframe Analysis: Incorporate longer-term trend analysis to optimize entry timing
Conclusion
This strategy captures market oversold opportunities through CCI indicator, combined with stop-loss and take-profit mechanisms to create a complete trading system. The strategy features clear logic, easy execution, and good risk control capabilities. Through optimization measures like signal filtering and dynamic thresholds, the strategy's stability and profitability can be further improved. Traders are advised to conduct thorough backtesting and adjust parameters according to specific market characteristics before live implementation.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-27 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("CCI Threshold Strategy", overlay=false, initial_capital=50000, pyramiding=0, commission_type=strategy.commission.cash_per_contract, commission_value=0.05, slippage=1)

// --- Input Parameters ---
// Lookback period for CCI calculation
lookbackPeriod = input.int(12, minval=1, title="CCI Lookback Period")
// Buy threshold for CCI; typically represents an oversold condition
buyThreshold = input.int(-90, title="CCI Buy Threshold")
// Stop loss and take profit settings
stopLoss = input.float(100.0, minval=0.0, title="Stop Loss in Points")
takeProfit = input.float(150.0, minval=0.0, title="Take Profit in Points")
// Checkboxes to enable/disable SL and TP
useStopLoss = input.bool(false, title="Enable Stop Loss")
useTakeProfit = input.bool(false, title="Enable Take Profit")

// --- Calculate CCI ---
// CCI (Commodity Channel Index) is used as a momentum indicator to identify oversold and overbought conditions
cci = ta.cci(close, length=lookbackPeriod)

// --- Define Buy and Sell Conditions ---
// Buy condition: CCI drops below -90, indicating potential oversold levels
longCondition = cci < buyThreshold

// Sell condition: Close price crosses above the previous day's high, signaling potential exit
sellCondition = close > ta.highest(close[1], 1)

// --- Strategy Execution ---
// Buy entry based on the long condition
if (longCondition)
    strategy.entry("Buy", strategy.long)

// Close the long position based on the sell condition
if (sellCondition)
    strategy.close("Buy")

// Optional: Add stop loss and take profit for risk management
if (longCondition)
    strategy.exit("Sell", from_entry="Buy", loss=useStopLoss ? stopLoss : na, profit=useTakeProfit ? takeProfit : na)

// --- Plotting for Visualization ---
// Plot CCI with threshold levels for better visualization
plot(cci, title="CCI", color=color.blue)
hline(buyThreshold, "Buy Threshold", color=color.red, linestyle=hline.style_dotted)
hline(0, "Zero Line", color=color.gray, linestyle=hline.style_dotted)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Indicator-Oscillation-Threshold-Enhanced-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Oscillator Candles Momentum Trading StrategyPine Script · Momentum · 1h
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- MACD Momentum Indicator Backtest StrategyPine Script · Momentum · 1h
- MoonFlag MACD Momentum StochRSI Trading StrategyPine Script · Momentum · 1d
- Multi Indicator MACD Momentum Options Strategy with Risk Controlled Percentage Based ExitsPine Script · Momentum · 1h