Strategy vault / Mean reversion
Momentum Moving Average Reversal Strategy
The core idea of this strategy is to combine the RSI indicator and moving average to find opportunities for stock price reversals and achieve buying low and selling high. When the RSI indicator shows that the stock…
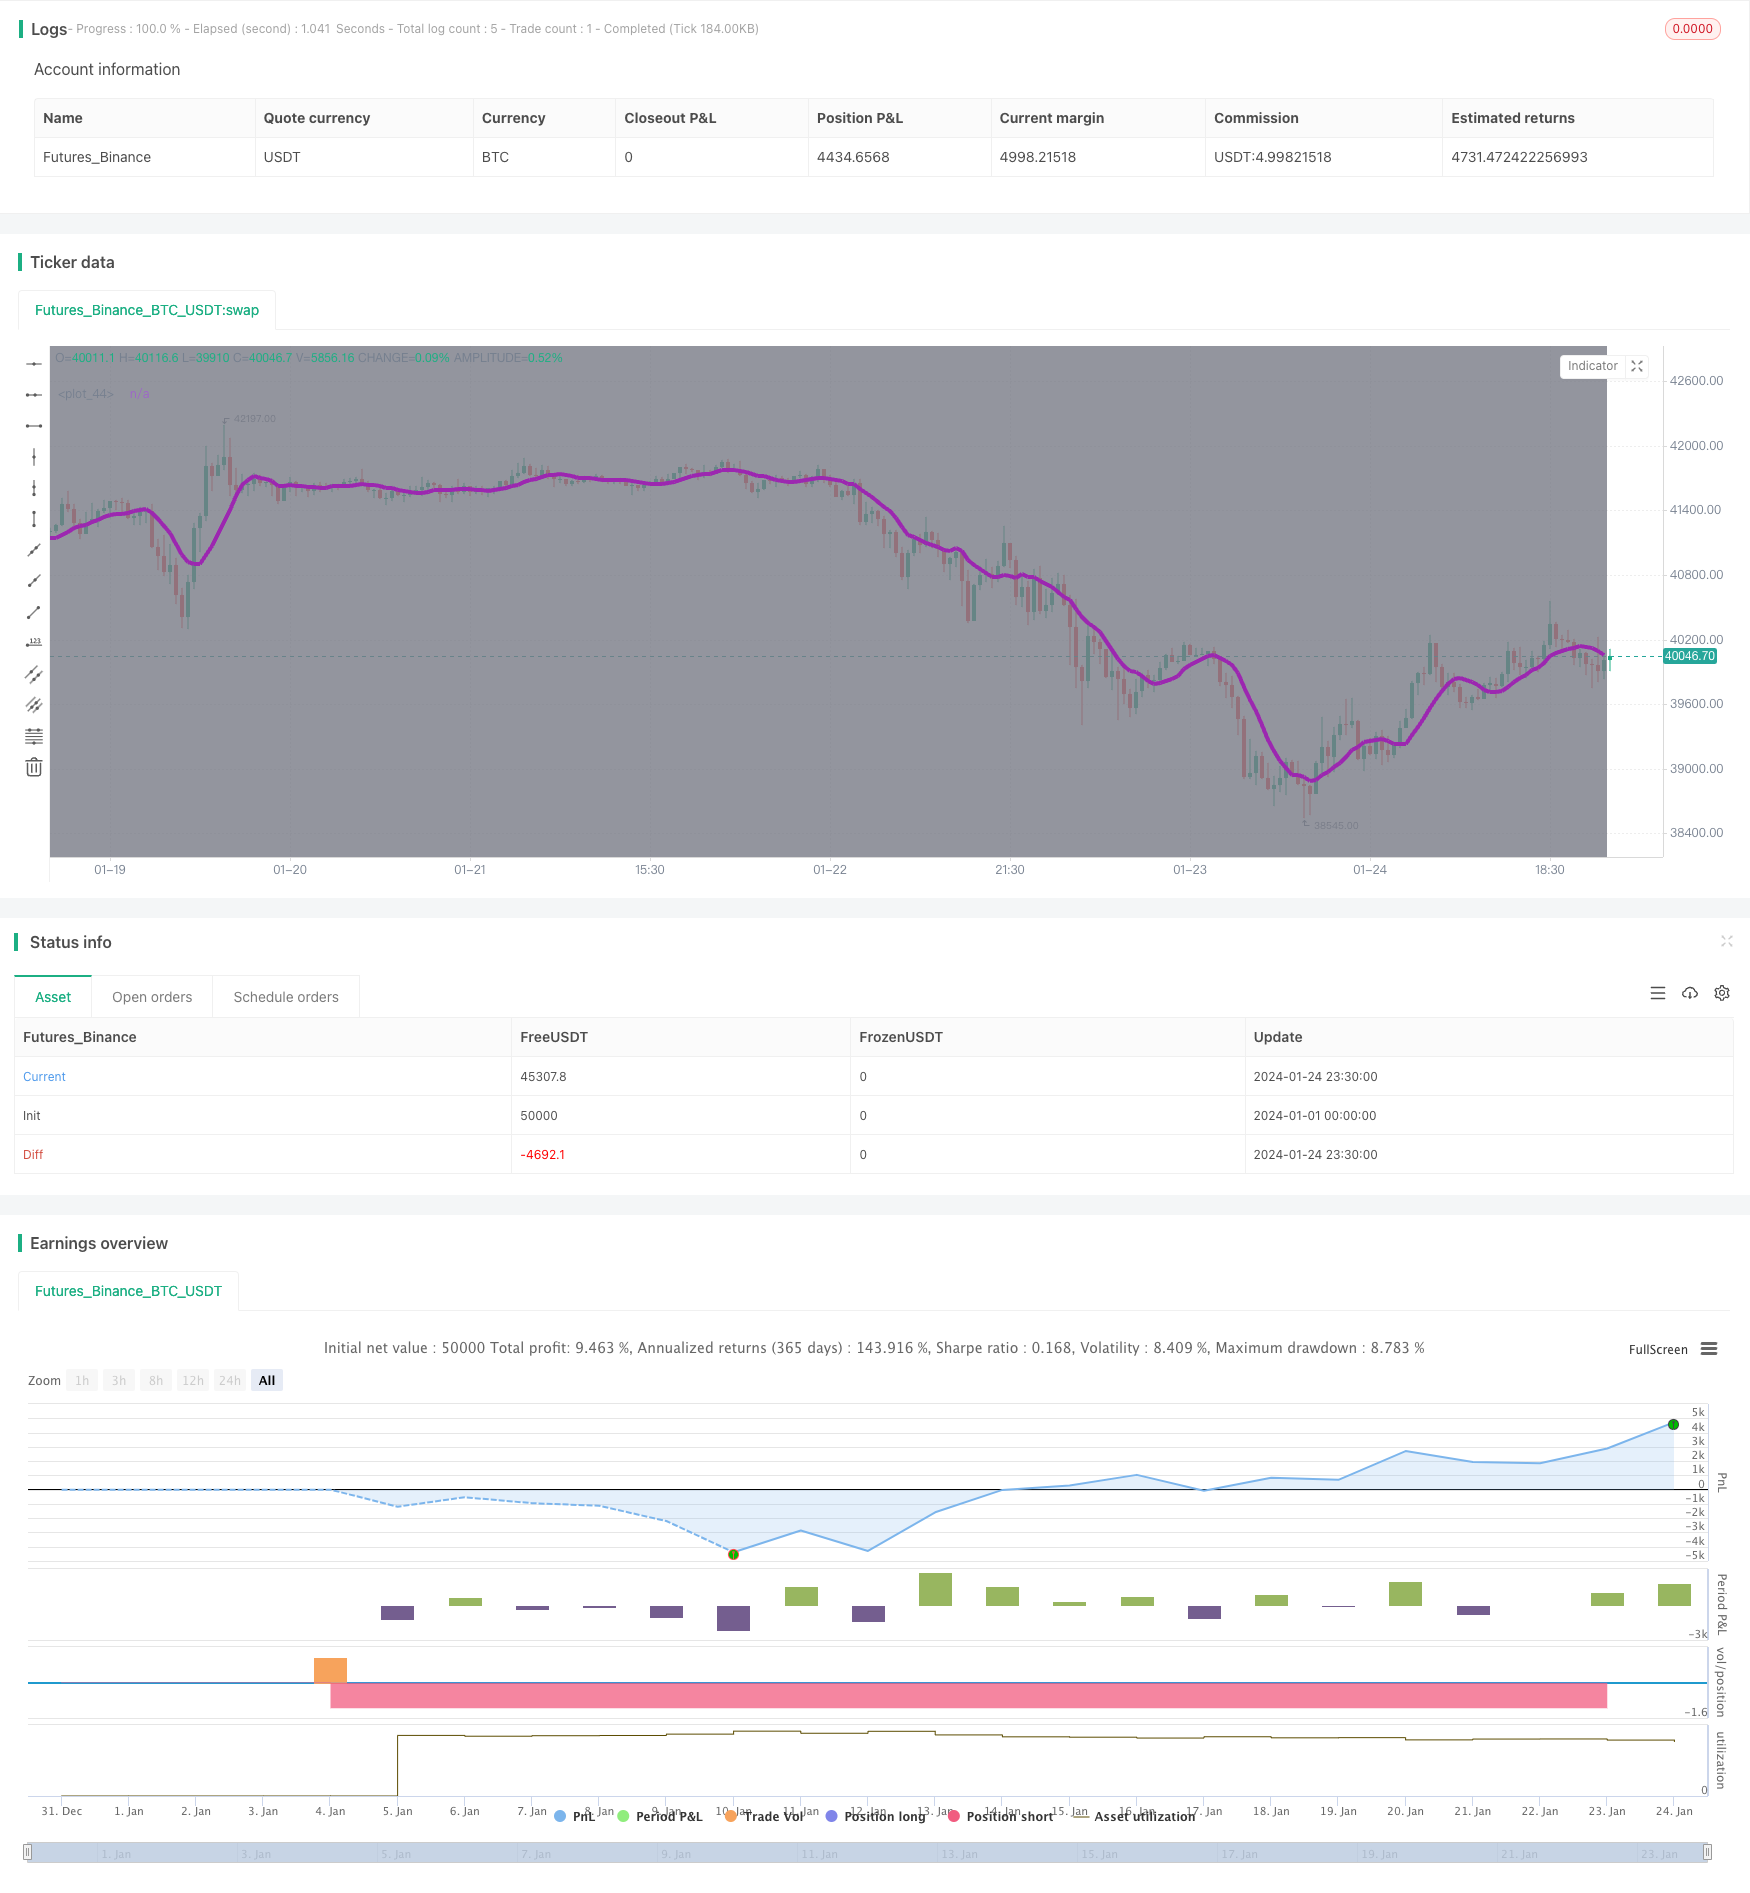
Overview
The core idea of this strategy is to combine the RSI indicator and moving average to find opportunities for stock price reversals and achieve buying low and selling high. When the RSI indicator shows that the stock is oversold and the short-term moving average crosses below the price, it serves as a buy signal. After setting the stop loss and take profit, wait for the price to reverse upward.
Strategy Principle
This strategy mainly uses the RSI indicator to judge oversold and overbought conditions, and the golden cross and dead cross of the moving average to determine price trends. Specifically, the RSI indicator can effectively judge whether a stock is oversold or overbought. When the RSI is below 30, it is in the oversold range. And when the short-term moving average (set to 9-day in this strategy) crosses below the price, it means the price is falling.
So when the RSI indicator is below 40, nearing the oversold state, and the 9-day moving average crosses below the price, it can be judged as a possible timing for the stock price to reverse, going long to buy. Then set the stop loss and take profit to exit, waiting for the stock price to reverse upward before selling to take profits.
Advantage Analysis
This strategy combines the RSI indicator and moving average, which can effectively determine the timing of buying. Compared with a single judgment of oversold, the added condition judgment of the moving average avoids fluctuation in the oversold area. The setting of stop loss and take profit is flexible and can vary from person to person.
Risk Analysis
This strategy relies on parameter settings such as RSI judgment threshold, moving average time window, etc. Different parameters may lead to different results. And under certain market conditions, stop loss is still possible.
In addition, transaction fees will also have a certain impact on profits. It is worth considering incorporating trading volume or fund management modules later for optimization.
Optimization Direction
Consider dynamically adjusting moving average parameters, selecting different parameters for different cycle; or introducing other indicators to judge, such as KDJ, MACD, etc., to form a comprehensive judgment based on multiple conditions.
It is also possible to establish a trading volume or capital management module to control the proportion of funds occupied by a single trade and reduce the impact of a single loss.
Summary
In general, this strategy uses RSI indicators and moving averages to determine buy timing and can effectively determine price reversals. Buying in oversold and locking in profits with stop loss and take profit can yield good results. For future optimizations, it is worth considering incorporating more Indicators or adding additional trading/fund management modules to make the strategy more robust.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | From Month |
| v_input_2 | true | From Day |
| v_input_3 | 2020 | From Year |
| v_input_4 | true | Thru Month |
| v_input_5 | true | Thru Day |
| v_input_6 | 2112 | Thru Year |
| v_input_7 | true | Show Date Range |
| v_input_8 | 9 | MA short period |
| v_input_9 | 14 | RSI period |
| v_input_10 | 1.5 | Long Stop Loss (%) |
| v_input_11 | 3 | Long Take Profit (%) |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-24 23:59:59
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Coinrule

//@version=4
strategy(shorttitle='MARSI',title='Moving Average', overlay=true, initial_capital=1000,  default_qty_type = strategy.percent_of_equity, default_qty_value = 100)

//Backtest dates
fromMonth = input(defval = 1,    title = "From Month",      type = input.integer, minval = 1, maxval = 12)
fromDay   = input(defval = 1,    title = "From Day",        type = input.integer, minval = 1, maxval = 31)
fromYear  = input(defval = 2020, title = "From Year",       type = input.integer, minval = 1970)
thruMonth = input(defval = 1,    title = "Thru Month",      type = input.integer, minval = 1, maxval = 12)
thruDay   = input(defval = 1,    title = "Thru Day",        type = input.integer, minval = 1, maxval = 31)
thruYear  = input(defval = 2112, title = "Thru Year",       type = input.integer, minval = 1970)

showDate  = input(defval = true, title = "Show Date Range", type = input.bool)

start     = timestamp(fromYear, fromMonth, fromDay, 00, 00)        // backtest start window
finish    = timestamp(thruYear, thruMonth, thruDay, 23, 59)        // backtest finish window
window()  => true

//MA inputs and calculations
inshort=input(9, title='MA short period')
MAshort= sma(close, inshort)

// RSI inputs and calculations
lengthRSI = input(14, title = 'RSI period', minval=1)
RSI = rsi(close, lengthRSI)

//Entry
strategy.entry(id="long", long = true, when = MAshort<close and RSI<40 and window())

//Exit
longLossPerc = input(title="Long Stop Loss (%)",
     type=input.float, minval=0.0, step=0.1, defval=1.5) * 0.01
longTakePerc = input(title="Long Take Profit (%)",
     type=input.float, minval=0.0, step=0.1, defval=3) * 0.01
longSL  = strategy.position_avg_price * (1 - longLossPerc)
longTP  = strategy.position_avg_price * (1 + longTakePerc)
if (strategy.position_size > 0 and window())
    strategy.exit(id="TP/SL", stop=longSL, limit=longTP)


bgcolor(color = showDate and window() ? color.gray : na, transp = 90)
plot(MAshort, color=color.purple, linewidth=4)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Moving-Average-Reversal-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- MACD Cross Period Trading StrategyPine Script · Mean reversion · 1d
- MACD Long Reversal StrategyPine Script · Mean reversion · 1d