Momentum Oscillation Crossing Bollinger Bands with Moving Average Strategy
This is a quantitative trading strategy based on Bollinger Bands and MACD indicators. It combines two mainstream technical indicators to identify trading opportunities, aiming to achieve higher win rate in trending…
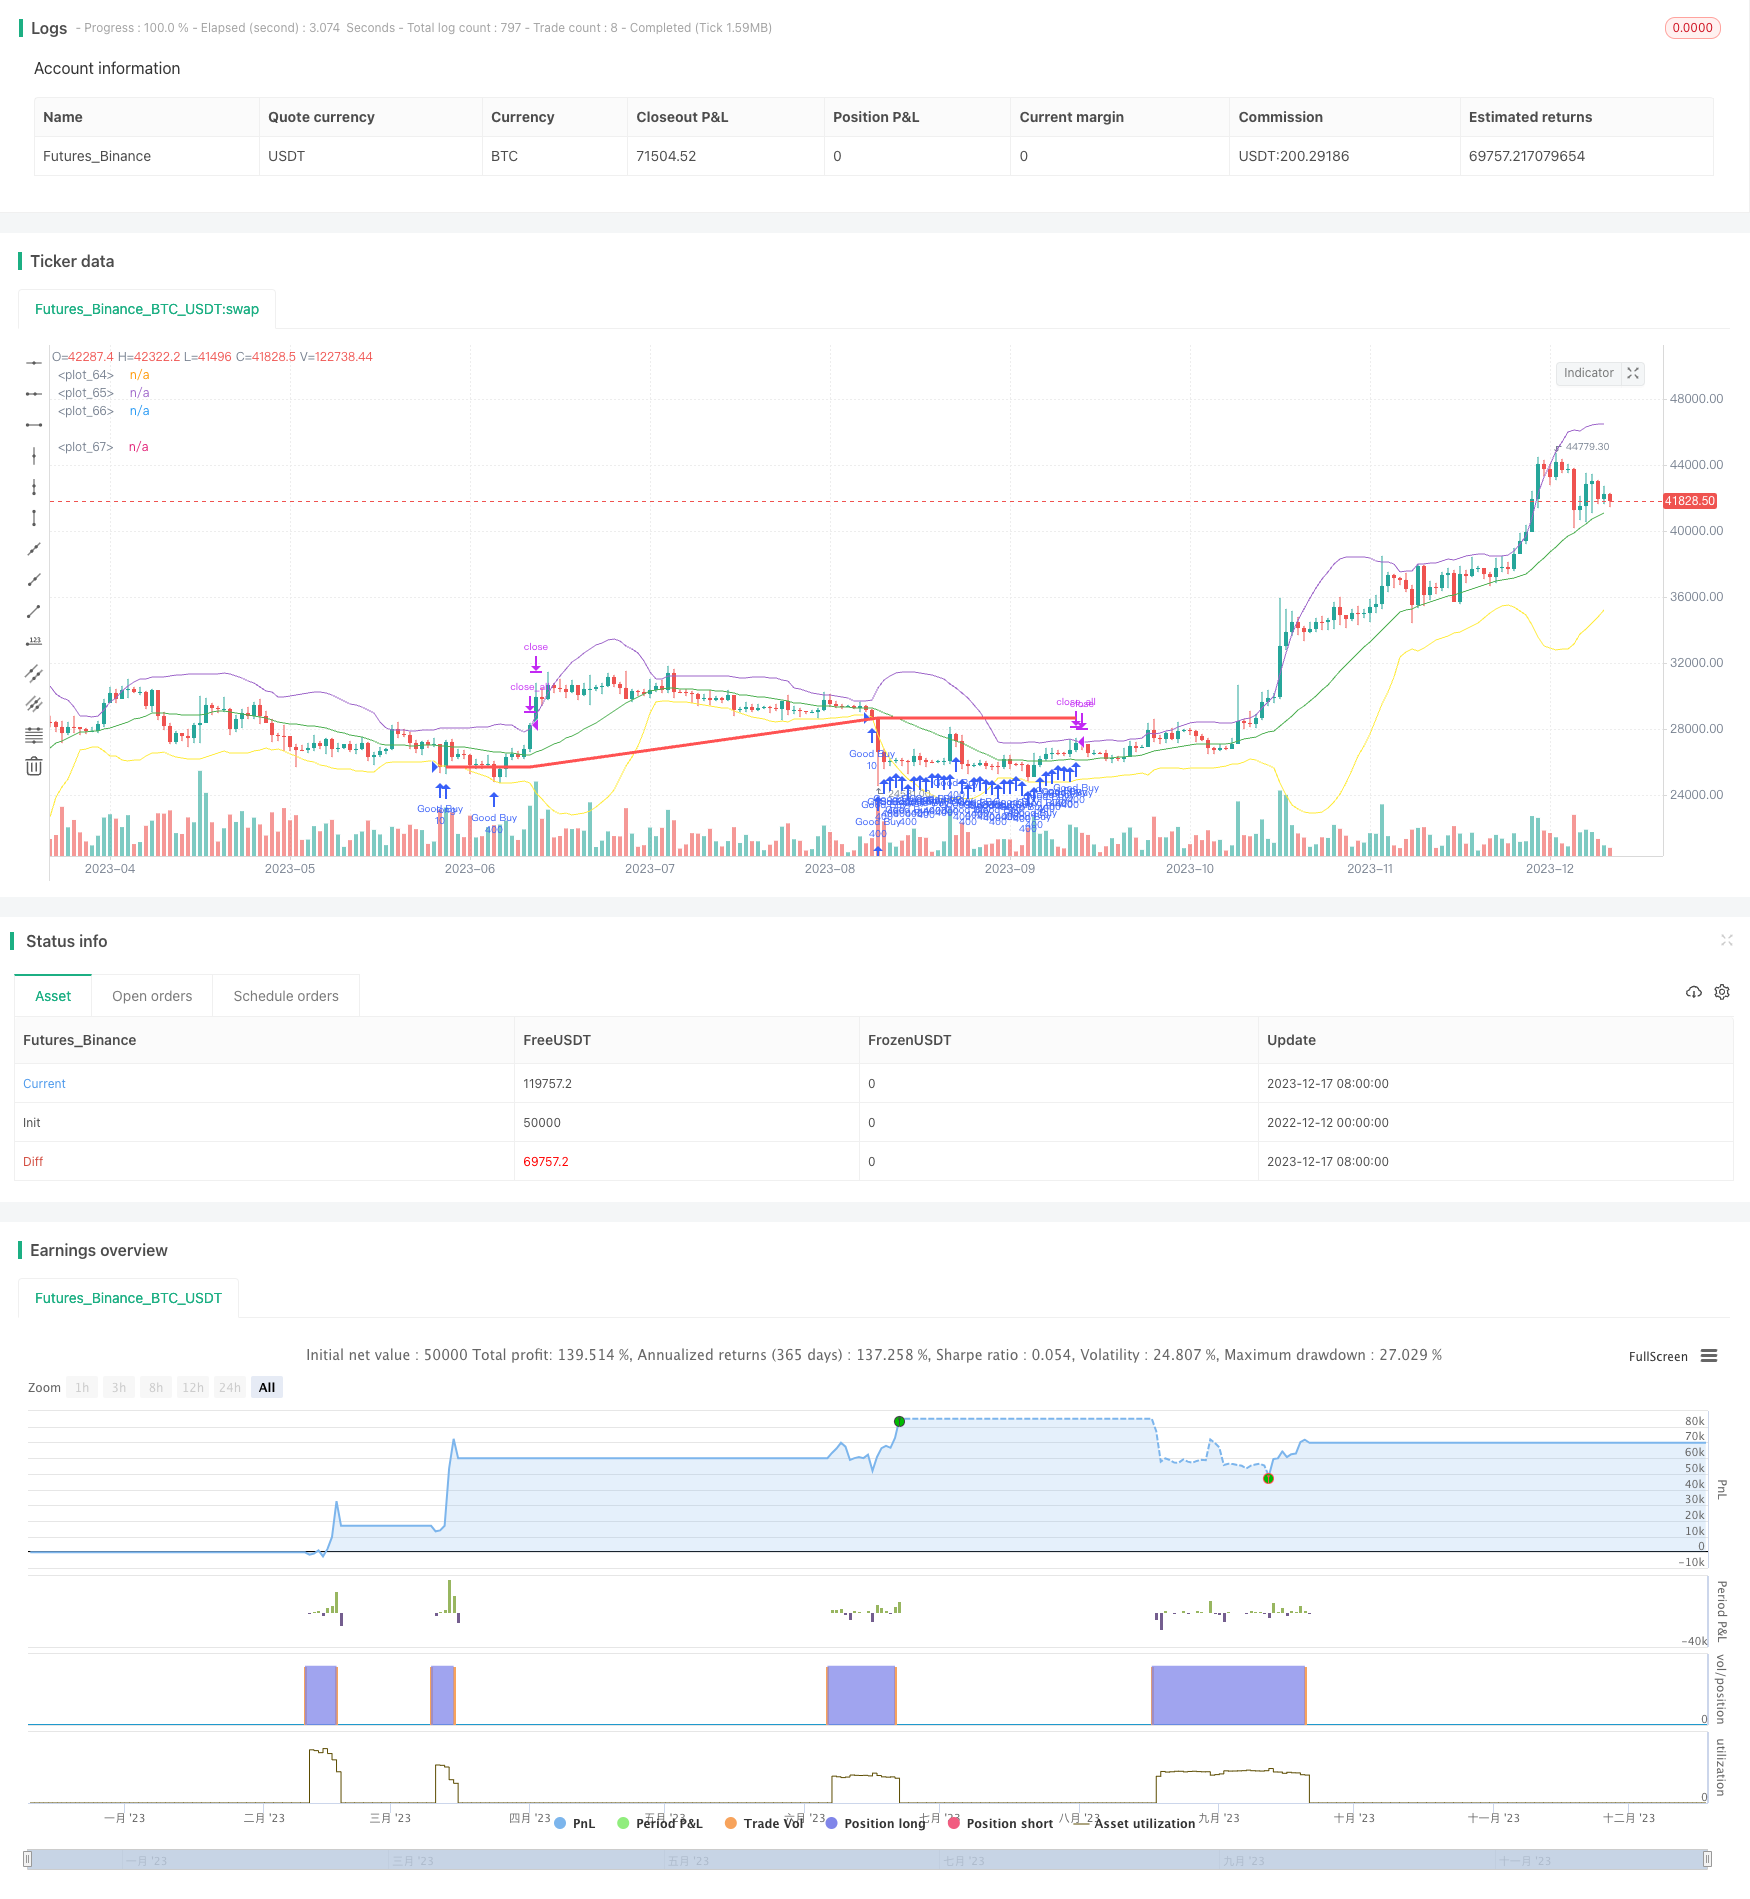
Overview
This is a quantitative trading strategy based on Bollinger Bands and MACD indicators. It combines two mainstream technical indicators to identify trading opportunities, aiming to achieve higher win rate in trending markets.
The strategy will establish long position when price breaks through the lower band of Bollinger Bands for trend following, and close position when price breaks through upper band. MACD indicator is used to filter false breakout by judging momentum direction. RSI indicator can be configured to assist in identifying overbought and oversold levels to further avoid losses.
Strategy Logic
The strategy consists mainly of Bollinger Bands and MACD indicators.
Bollinger Bands calculate upper and lower bands based on standard deviation of prices. Upward breakout of upper band signals overbought condition, while downward breakout of lower band signals oversold condition. This strategy goes long when price breaks down the lower band, and closes position when it breaks up the upper band.
MACD indicator judges momentum and direction of prices. Crossover of short term moving average above long term moving average is buy signal, while crossover below is sell signal. MACD helps filter false breakout of Bollinger Bands in this strategy.
Additionally, RSI indicator can assist in identifying overbought/oversold levels. Low RSI represents oversold and enhances buy signal, while high RSI represents overbought and enhances sell signal.
Advantages of the Strategy
The strategy combines Bollinger Bands, MACD and RSI indicators, which can effectively determine price trend and volatility. Its advantages include:
- Bollinger Bands capture trend following when price breaks out of bands
- MACD filters false signals from Bollinger Bands by judging momentum
- RSI avoids buying at peak by identifying overbought/oversold levels
- Higher win rate can be achieved through parameter optimization
Risks of the Strategy
There are also some risks to be aware of:
- High risk of stop loss when prices fluctuate violently
- Profitability decreases with improper parameter settings
- MACD may misjudge when trend reverses
Countermeasures:
- Stop loss percentage can be loosened appropriately
- Extensive backtesting required to find optimum parameters
- More indicators can be used to predict trend reversal
Directions for Optimization
Major directions to optimize the strategy include:
- Optimize parameters of Bollinger Bands for more market regimes
- Increase indicators to improve robustness
- Utilize machine learning to auto optimize parameters
- Test strategy performance on high frequency data
- Add risk management module to limit per trade loss
Conclusion
Overall this is a typical trend following strategy. By combining multiple technical indicators, it improves robustness and can achieve decent win rate when signals are accurate. However risks need to be monitored. Further improvements can be made through continuous optimization and tuning.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0 | Simple bot: simple | composite |
| v_input_2 | 3Commas Bot ID | |
| v_input_3 | Bot Email Token | |
| v_input_4 | 10 | Base order size |
| v_input_5 | 400 | Safety order size |
| v_input_6 | 1.83 | Safety Order Vol Scale (%) |
| v_input_7 | 1.55 | Safety Order Step Scale (%) |
| v_input_8 | 2 | Max Number of Safety Orders |
| v_input_9 | 1.54 | Initial SO Deviation (%) |
| v_input_10 | 15 | Long Stop Loss (%) |
| v_input_11 | 1.4 | Long Take Profit (%) |
| v_input_12 | 21 | Short MA Window |
| v_input_13 | 100 | Long MA Window |
| v_input_14 | 2.2 | Upper Band Offset |
| v_input_15 | 2.4 | Lower Band Offset |
| v_input_16 | 0 | Entrry at Cross Over/Under Lower: under | over |
| v_input_17 | true | Start Date |
| v_input_18 | true | Start Month |
| v_input_19 | 2016 | Start Year |
| v_input_20 | 31 | End Date |
| v_input_21 | 12 | End Month |
| v_input_22 | 2022 | End Year |
| v_input_47 | true | Use long? |
| v_input_48 | true | Use short? |
| v_input_23 | 23 | (?MACD)Fast Length |
| v_input_24 | 16 | Slow Length |
| v_input_25_open | 0 | Source: open | high | low | close | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_26 | 9 | Signal Smoothing |
| v_input_27 | 0 | Simple MA FAST (Oscillator): EMA | DHMA | THMA | FHMA | WMA | DWMA | TWMA | FWMA | SMA | DSMA | TSMA | FSMA | HMA | DEMA | TEMA | FEMA | RMA | DRMA | TRMA | FRMA |
| v_input_28 | 0 | Simple MA SLOW (Oscillator): EMA | DHMA | THMA | FHMA | WMA | DWMA | TWMA | FWMA | SMA | DSMA | TSMA | FSMA | HMA | DEMA | TEMA | FEMA | RMA | DRMA | TRMA | FRMA |
| v_input_29 | 0 | Simple MA(Signal Line): EMA | DHMA | THMA | FHMA | WMA | DWMA | TWMA | FWMA | SMA | DSMA | TSMA | FSMA | HMA | DEMA | TEMA | FEMA | RMA | DRMA | TRMA | FRMA |
| v_input_30 | true | (?Stress)Use stress on recent bars |
| v_input_31 | 0.41 | Stress on recent bars |
| v_input_32 | 6 | Level of stress |
| v_input_33 | true | (?Moving Average)Use moving average (MACD)? |
| v_input_34 | 36 | Length |
| v_input_35 | 0 | Type MA: THMA | DHMA | HMA | FHMA | WMA | DWMA | TWMA | FWMA | SMA | DSMA | TSMA | FSMA | EMA | DEMA | TEMA | FEMA | RMA | DRMA | TRMA | FRMA |
| v_input_36 | true | (?Linear Regression)Use linear regression (MACD)? |
| v_input_37 | 10 | Length |
| v_input_38 | true | Offset |
| v_input_39 | false | (?Condition entry/exit)Use cross macd and signal |
| v_input_40 | true | Use min/max macd |
| v_input_41 | false | (?RSI)Use RSI filter? |
| v_input_42 | true | Use RSI Take Profit? |
| v_input_43 | 22 | RSI period |
| v_input_44_close | 0 | RSI source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_45 | 90 | Overbought height |
| v_input_46 | 45 | Oversold height |
Source Pine Script
/*backtest
start: 2022-12-12 00:00:00
end: 2023-12-18 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © tedwardd

// This strategy is intended to help users of the 3commas.io platform backtest bot performance based on a Bollinger Strategy.
// It can also be used to signal a bot to open a deal by providing the Bot ID, email token and trading pair in the strategy settings screen.
// As currently written, this strategy uses a basic Bollinger Band strategy, recommening a deal start when the closing price crosses under the lower band.
// The thick red line plotted on the chart shows the average entry price of the current deal.

strategy("[v1.3laoowai]BNB_USDT_3m_3Commas_Bollinger_Strategy_by_tedwardd", overlay=true, default_qty_type=strategy.cash, default_qty_value=1000, initial_capital=900, currency="USD", commission_value=0.1)

// 3Commas Bot settinsg
bot_type                = input(title="Simple bot", defval="simple", options=["simple", "composite"])
bot_id                  = input(title="3Commas Bot ID", defval="")
email_token             = input(title="Bot Email Token", defval="")
base_order_size         = input(title="Base order size",minval=10, step=1, defval=10)
safety_order_size       = input(title="Safety order size", minval=15, step=1, defval=400)
volume_scale            = input(title="Safety Order Vol Scale (%)", minval=0.00, step=0.01, defval=1.83)
safety_step             = input(title="Safety Order Step Scale (%)", minval=0.00, step=0.1, defval=1.55)
safety_max              = input(title="Max Number of Safety Orders", minval=0, step=1, defval=2)
initial_deviation_input = input(title="Initial SO Deviation (%)", minval=0, step=0.01, defval=1.54) * 0.01
stoploss_input          = input(title="Long Stop Loss (%)", minval=0, step=1, defval=15) * 0.01
takeprofit_input        = input(title="Long Take Profit (%)", minval=0, step=1, defval=1.4) * 0.01

// USER INPUTS
sma_short_val           = input(title="Short MA Window", defval=21)
sma_long_val            = input(title="Long MA Window", defval=100)
ubOffset                = input(title="Upper Band Offset", defval=2.2, step=0.5)
lbOffset                = input(title="Lower Band Offset", defval=2.40, step=0.5)
cross                   = input(title="Entrry at Cross Over/Under Lower", defval="under", options=["over", "under"])

// Backtesting Date Ranges
startDate  = input(title="Start Date", defval=1, minval=1, maxval=31)
startMonth = input(title="Start Month", defval=1, minval=1, maxval=12)
startYear  = input(title="Start Year", defval=2016, minval=1800, maxval=2100)
endDate    = input(title="End Date", defval=31, minval=1, maxval=31)
endMonth   = input(title="End Month", defval=12, minval=1, maxval=12)
endYear    = input(title="End Year", defval=2022, minval=1800, maxval=2100)

// VARS
short_sma        = sma(close, sma_short_val)
long_sma         = sma(close, sma_long_val)
stdDev           = stdev(close, sma_short_val)
upperBand        = short_sma + (stdDev * ubOffset)
lowerBand        = short_sma - (stdDev * lbOffset)
stoploss_value   = strategy.position_avg_price * (1 - stoploss_input)
takeprofit_value = strategy.position_avg_price * (1 + takeprofit_input)
initial_dev_val  = strategy.position_avg_price * (1 - initial_deviation_input)
inDateRange      = true

initial_deviation = close < initial_dev_val

// Market Conditions
goodBuy    = cross=="over"?crossover(close, lowerBand):crossunder(close, lowerBand) // Buy when close crossing lower band
safety     = initial_deviation and (1-(close/strategy.position_avg_price))/.01 > strategy.opentrades-1 * safety_step and strategy.opentrades <= safety_max // SO when price deviates below SO threshold %
stoploss   = close <= stoploss_value // Stoploss condition - true if closing price for current bar drops below stoploss %
takeprofit = close >= takeprofit_value // Take profit condition - true if closing price for current bar is >= take profit percentage
goodSell = crossover(high, upperBand)

// goodSell is currently unused for any practical purpose. If you wish to try it, switch these two values.
// Doing so will make sell suggestions at high crossover upper bollinger but it does not trigger the bot to sell as written but may affect backtest results

// Plot some lines
plot(short_sma, color=color.green)
plot(upperBand)
plot(lowerBand, color=color.yellow)
plot(strategy.position_avg_price, color=color.red, linewidth=3)


// Webhook message. Defaults to string. To signal 3c bot, fill in bot_id and email_token in user settings
var enter_msg = "Enter Position"
var exit_msg  = "Exit Position"
var close_all = "Exit Position"
if bot_id != "" and email_token != ""
    if bot_type == "composite"
        enter_msg := '{"message_type": "bot", "bot_id": ' + bot_id + ', "email_token": "' + email_token + '", "delay_seconds": 0, "pair": "' + syminfo.currency + "_" + syminfo.basecurrency + '"}'
    else
        enter_msg := '{"message_type": "bot", "bot_id": ' + bot_id + ',  "email_token": "' + email_token + '", "delay_seconds": 0}'
    if bot_type == "composite"
        exit_msg := '{"message_type": "bot", "bot_id": ' + bot_id + ', "email_token": "' + email_token + '", "delay_seconds": 0, "pair": "' + syminfo.currency + "_" + syminfo.basecurrency + '", "action": "close_at_market_price"}'
    else
        exit_msg := '{"message_type": "bot", "bot_id": ' + bot_id + ', "email_token": "' + email_token + '", "delay_seconds": 0, "action": "close_at_market_price"}'
    close_all := '{"message_type": "bot", "bot_id": ' + bot_id + ', "email_token": "' + email_token + '", "delay_seconds": 0, "action": "close_at_market_price_all"}'

actual_safety_size = float(safety_order_size) // Set safety order size to starting safety
if strategy.opentrades > 1 // If we have more than two open trades we need to start scaling the safety size by the volume_scale
    actual_safety_size := (strategy.position_size - base_order_size) * volume_scale // Remove base order from total position size and scale it for next safety order

// Momentum Strategy (BTC/USDT; 1h) - MACD (with source code) by Drun30

//@version=4
// Getting inputs
fast_length = input(title="Fast Length", type=input.integer, defval=23,group="MACD")
slow_length = input(title="Slow Length", type=input.integer, defval=16,group="MACD")
src = input(title="Source", type=input.source, defval=open,group="MACD")

signal_length = input(title="Signal Smoothing", type=input.integer, minval = 1, maxval = 50, defval = 9,group="MACD")
sma_source1 = input(title="Simple MA FAST (Oscillator)", defval="EMA", options=["HMA","DHMA","THMA","FHMA","WMA","DWMA","TWMA","FWMA","SMA","DSMA","TSMA","FSMA","EMA","DEMA","TEMA","FEMA","RMA","DRMA","TRMA","FRMA"],group="MACD")
sma_source2 = input(title="Simple MA SLOW (Oscillator)", defval="EMA", options=["HMA","DHMA","THMA","FHMA","WMA","DWMA","TWMA","FWMA","SMA","DSMA","TSMA","FSMA","EMA","DEMA","TEMA","FEMA","RMA","DRMA","TRMA","FRMA"],group="MACD")

sma_signal = input(title="Simple MA(Signal Line)",defval="EMA", options=["HMA","DHMA","THMA","FHMA","WMA","DWMA","TWMA","FWMA","SMA","DSMA","TSMA","FSMA","EMA","DEMA","TEMA","FEMA","RMA","DRMA","TRMA","FRMA"],group="MACD")
// Calculating
ma(source,length,type)=>
    type=="FEMA"?4*ema(source,length)-ema(ema(ema(ema(source,length),length),length),length):type=="FSMA"?4*sma(source,length)-sma(sma(sma(sma(source,length),length),length),length):type=="FWMA"?4*wma(source,length)-wma(wma(wma(wma(source,length),length),length),length):type=="FRMA"?4*rma(source,length)-rma(rma(rma(rma(source,length),length),length),length):type=="TEMA"?3*ema(source,length)-ema(ema(ema(source,length),length),length):type=="TSMA"?3*sma(source,length)-sma(sma(sma(source,length),length),length):type=="TWMA"?3*wma(source,length)-wma(wma(wma(source,length),length),length):type=="TRMA"?3*rma(source,length)-rma(rma(rma(source,length),length),length):type=="EMA"?ema(source,length):type=="SMA"?sma(source,length):type=="WMA"?wma(source,length):type=="RMA"?rma(source,length):type=="DEMA"?2*ema(source,length)-ema(ema(source,length),length):type=="DSMA"?2*sma(source,length)-sma(sma(source,length),length):type=="DWMA"?2*wma(source,length)-wma(wma(source,length),length):type=="DRMA"?2*rma(source,length)-rma(rma(source,length),length):type=="HMA"?hma(source,length):type=="DHMA"?2*hma(source,length)-hma(hma(source,length),length):type=="THMA"?3*hma(source,length)-hma(hma(hma(source,length),length),length):type=="FHMA"?4*hma(source,length)-hma(hma(hma(hma(source,length),length),length),length):ema(source,length)
fast_ma = ma(src,fast_length,sma_source1)
slow_ma = ma(src,slow_length,sma_source2)
macd = fast_ma - slow_ma //Differenza tra la media mobile veloce e quella lenta
signal = ma(macd,signal_length,sma_signal) //usa o la SMA oppure la EMA sulla differenza tra la media mobile veloce e lenta
hist = macd - signal //Differenza tra la differenza precedente e la media mobile della differenza

use_stress=input(true,title="Use stress on recent bars",group="Stress")
recent_stress=input(0.41,title="Stress on recent bars",group="Stress",step=0.01,minval=0.01,maxval=0.99)
level=input(6,title="Level of stress",group="Stress")
if use_stress
    macd:=macd*(1/(1-recent_stress))
    if not na(macd[1])
        macd:=pow((macd*(recent_stress)),level)+(1-recent_stress*macd[1])

use_ma= input(true,title="Use moving average (MACD)?",group="Moving Average")
if use_ma
    macd:=ma(macd,input(36,title="Length",group="Moving Average"),input(title="Type MA",defval="THMA", options=["HMA","DHMA","THMA","FHMA","WMA","DWMA","TWMA","FWMA","SMA","DSMA","TSMA","FSMA","EMA","DEMA","TEMA","FEMA","RMA","DRMA","TRMA","FRMA"],group="Moving Average"))

use_linreg= input(true,title="Use linear regression (MACD)?",group="Linear Regression")
if use_linreg
    macd:=linreg(macd,input(10,title="Length",group="Linear Regression"),input(1,title="Offset",group="Linear Regression"))

//macd == linea blu (differenza tra media mobile veloce e media mobile lenta)
//signal == linea arancione (media mobile dell'macd)
//hist == istogramma (differenza tra macd e media mobile)

on_cross = input(false,title="Use cross macd and signal",group="Condition entry/exit")
on_minmax = input(true,title="Use min/max macd",group="Condition entry/exit")


aperturaLong = change(macd)>0//crossover(macd,signal)
aperturashort=not (change(macd)>0)//crossunder(macd,signal)

if on_cross
    on_minmax:=false
    aperturaLong := crossover(macd,signal)
    aperturashort := crossunder(macd,signal)
if on_minmax
    on_cross:=false
    aperturaLong := change(macd)>0//crossover(macd,signal)
    aperturashort:=change(macd)<0//crossunder(macd,signal)

rsiFilter = input(false,title="Use RSI filter?",group="RSI")
rsiTP = input(true,title="Use RSI Take Profit?",group="RSI")

len=input(22,title="RSI period",group="RSI")
srcr=input(close,title="RSI source",group="RSI")
rsi=rsi(srcr,len)
ovb=input(90,title="Overbought height",group="RSI")
ovs=input(45,title="Oversold height",group="RSI")
okLong=rsi<ovb and change(macd)>0 and change(macd)[1]<=0
okShort=rsi>ovs and change(macd)<0 and change(macd)[1]>=0
if not rsiFilter
    okLong:=true
    okShort:=true

usiLong=input(true,title="Use long?")
usiShort=input(true,title="Use short?")

chiusuraShort=rsi<ovs or (aperturaLong)
chiusuraLong=rsi>ovb or (aperturashort)
if rsiTP
    aperturaLong := change(macd)>0 and change(macd)[1]<=0 and rsi<ovb//crossover(macd,signal)
    aperturashort:=change(macd)<0 and change(macd)[1]>=0 and rsi>ovs//crossunder(macd,signal)

if not rsiTP
    chiusuraShort:=okLong and aperturaLong
    chiusuraLong:=okShort and aperturashort

//if chiusuraShort
//    strategy.close("SHORTISSIMO")
//if usiLong and strategy.position_size<=0 and okLong and aperturaLong
//    strategy.entry("LONGHISSIMO",true)
//if chiusuraLong
//    strategy.close("LONGHISSIMO")
//if usiShort and strategy.position_size>=0 and okShort and aperturashort
//    strategy.entry("SHORTISSIMO",false)

// Strategy Actions
//Buy
if inDateRange and goodBuy
    strategy.entry("Good Buy", strategy.long, base_order_size, when = strategy.opentrades <= 0, alert_message=enter_msg)
if inDateRange and safety
    strategy.order("Good Buy", strategy.long, actual_safety_size, when = strategy.opentrades > 0, comment = "safety order", alert_message=enter_msg)

// Sell
if inDateRange and goodSell
    strategy.close_all(comment="Good sell point", alert_message=exit_msg)
if inDateRange and stoploss
    strategy.close_all(comment="Stoploss", alert_message=exit_msg)
//if inDateRange and takeprofit
//    strategy.close_all(comment="TP Target", alert_message=exit_msg)
if usiShort and strategy.position_size>=0 and okShort and aperturashort
    strategy.close_all(comment="SHORTISSIMO", alert_message=exit_msg)
//if chiusuraShort
// strategy.close_all(comment="SHORTISSIMO1")Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Oscillation-Crossing-Bollinger-Bands-with-Moving-Average-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Momentum Indicator Aggregation Trading StrategyPine Script · Momentum · 1h
- Multi Indicator Trend Momentum Trading Strategy An Optimized Quantitative Trading System Based on Bollinger Bands Fibonacci and ATRPine Script · Momentum · 1h
- Multi Trend Momentum Crossover Strategy with Volatility Optimization SystemPine Script · Momentum · 1d
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Multi Indicator Dynamic Stop Loss Momentum Trend Trading StrategyPine Script · Momentum · 1h
- Multi factor Fusion Strategy Multi factor Fusion StrategyPine Script · Momentum · 3h