Strategy vault / Mean reversion
Momentum Reversal Moving Average Combination Strategy
This strategy identifies trends by combining multiple moving average indicators. Specifically, this strategy uses a fast moving average ribbon and a slow moving average ribbon at the same time. The fast moving…
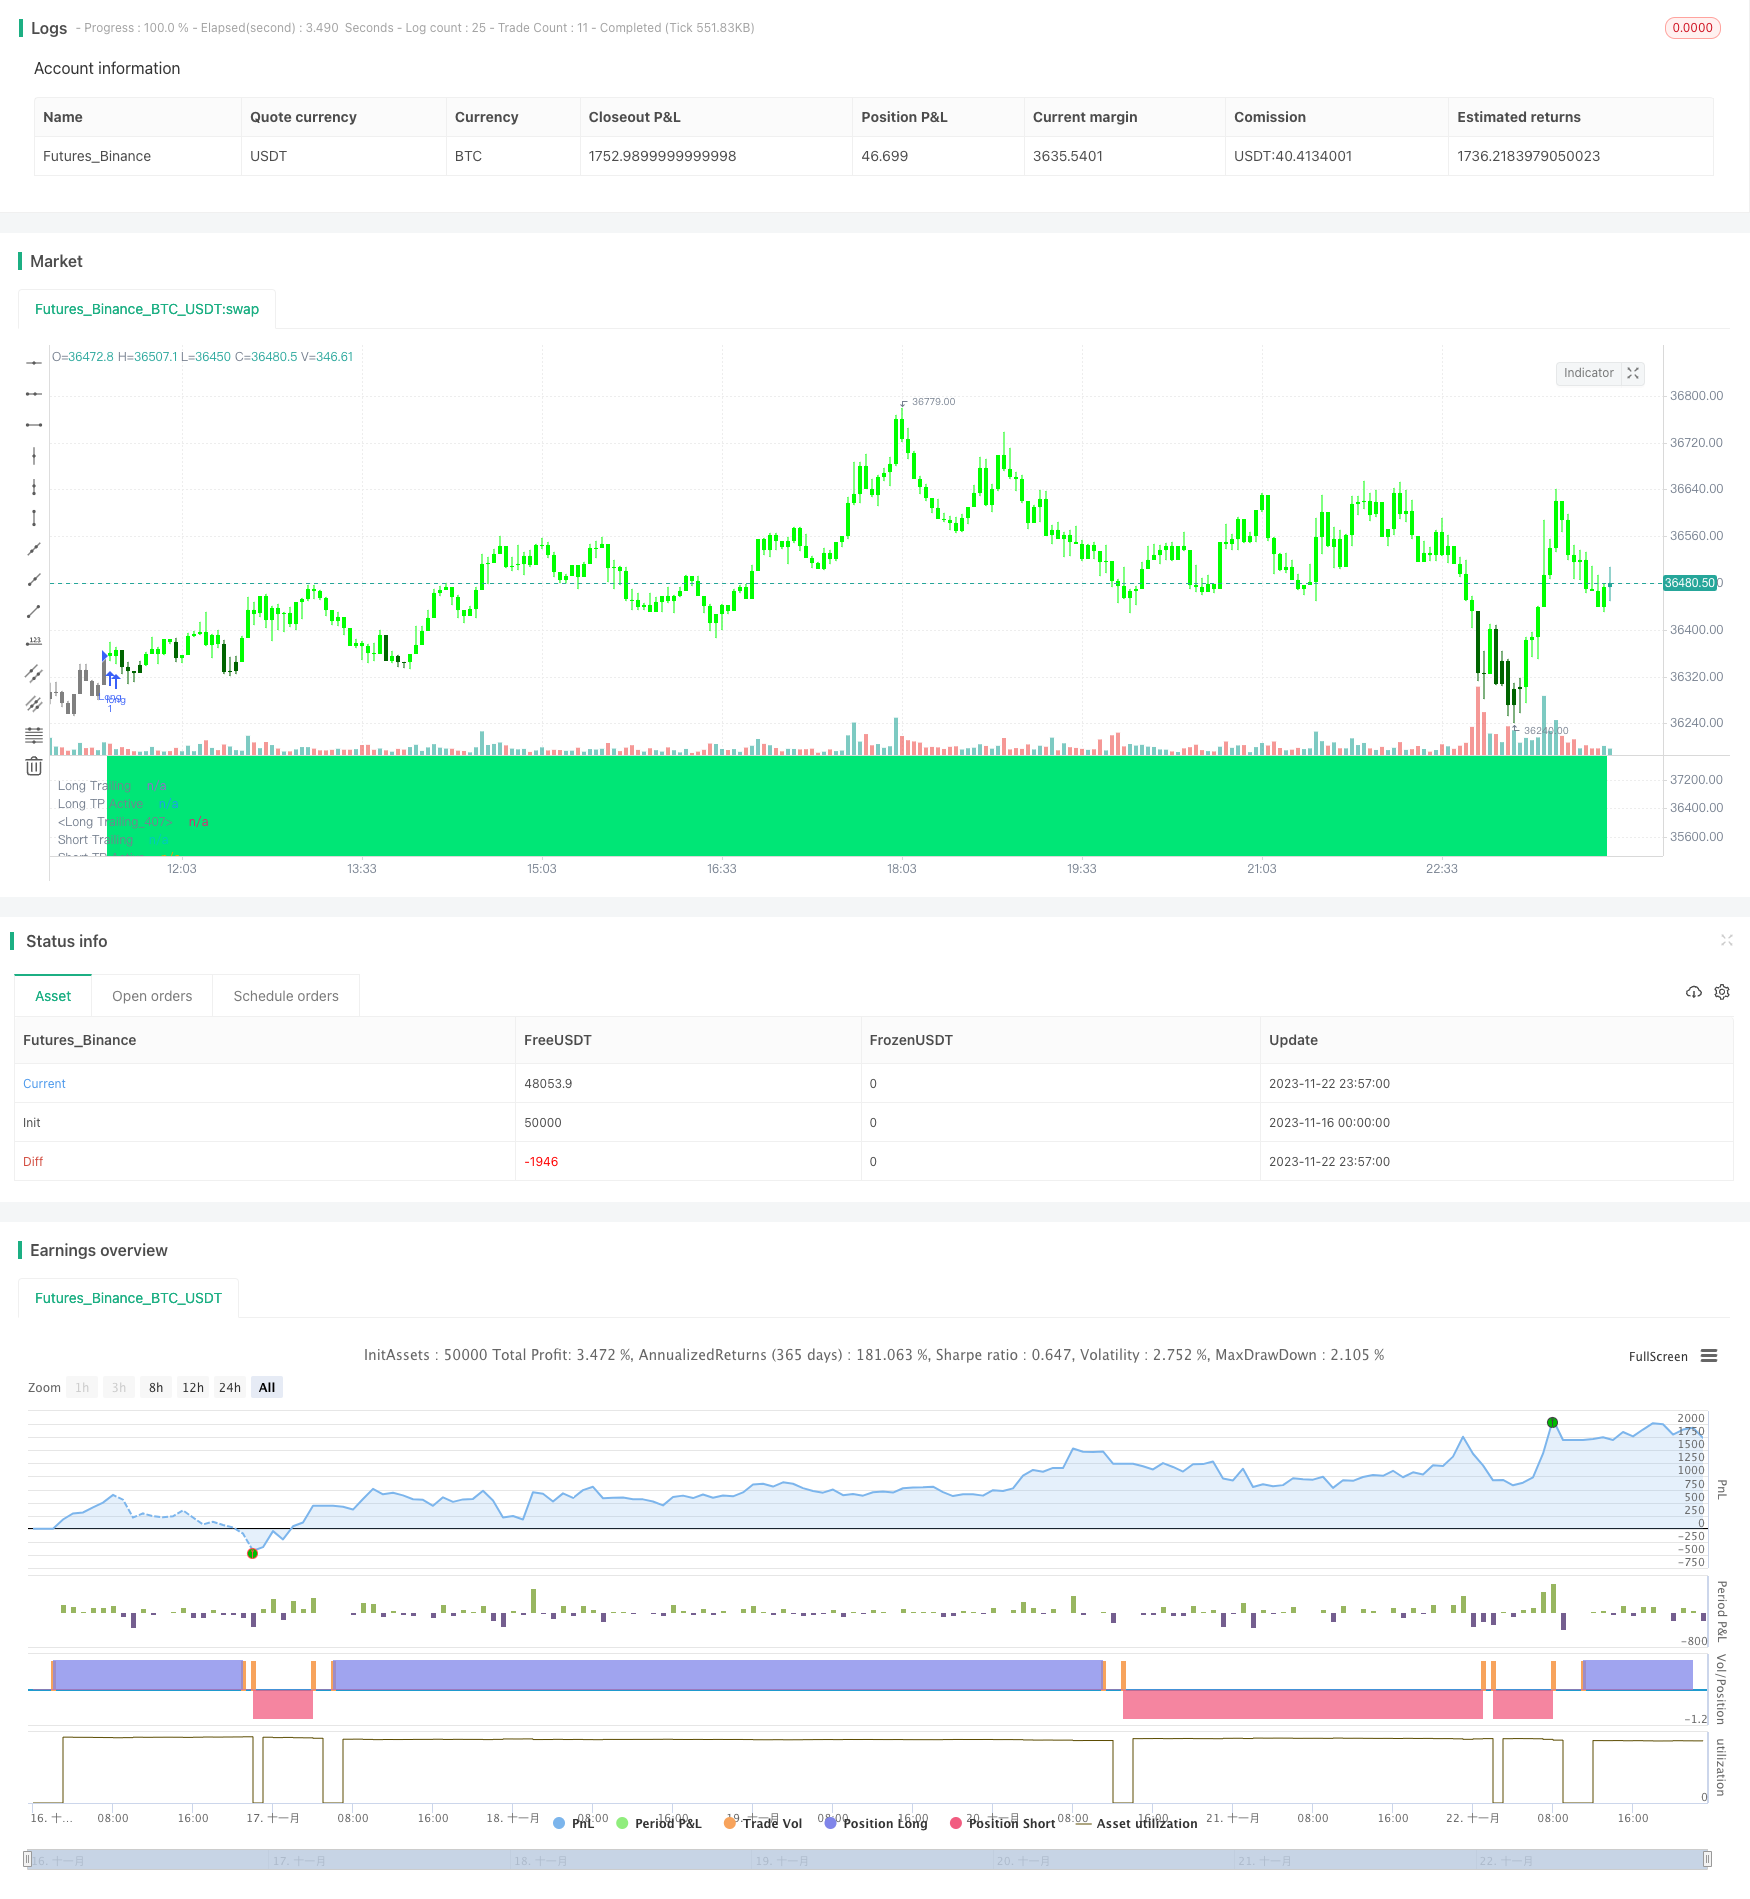
Overview
This strategy identifies trends by combining multiple moving average indicators. Specifically, this strategy uses a fast moving average ribbon and a slow moving average ribbon at the same time. The fast moving average ribbon consists of a 5-day EMA and a 25-day WMA, while the slow moving average ribbon consists of a 28-day EMA and a 72-day WMA. It generates a buy signal when the fast MA crosses above the slow MA, and a sell signal when the fast MA crosses below the slow MA. In addition, this strategy also uses the RSI indicator to assist in judging the timing.
Strategy Logic
- Use double moving averages to determine the trend direction
- Fast MA Ribbon: 5-day EMA, 25-day WMA
- Slow MA Ribbon: 28-day EMA, 72-day WMA
- When fast MA crosses above slow MA, generate a buy signal
- When fast MA crosses below slow MA, generate a sell signal
- Use RSI indicator to assist in determining the timing of buys and sells
- RSI Low to Buy: Generate a buy signal when RSI<35
- RSI High to Sell: Generate a sell signal when RSI>65
- Adopt trend tracking mechanisms including moving stop loss and moving take profit
- Moving stop loss: Track highest/lowest price to prevent excessive losses
- Moving take profit: Track highest/lowest price for timely profit taking
Advantage Analysis
- Using double MAs to determine trends, fast and slow MAs working together can effectively identify turning points
- RSI indicator's assistance helps avoid erroneous signals from MAs
- Moving stop loss mechanism effectively controls losses of individual losing trades
- Moving take profit mechanism locks in profits and prevents profit retracement
Risk Analysis
- Relatively high probability of failure in trend determination by double MAs, may generate false signals
- Improper RSI parameter settings may miss trading opportunities
- Excessively large stop loss magnitude may cause unnecessary losses
- Excessively small take profit magnitude may result in profit shrinkage
Optimization Directions
- Parameters of fast and slow MAs can be optimized to find optimal parameter combinations
- RSI parameters can also be optimized to find better overbought/oversold lines
- Test with different stop loss magnitudes to find balance between minimizing losses and avoiding false signals
- Try adaptive take profit strategies to allow take profit magnitude to adjust on its own based on market volatility
Conclusion
This strategy captures and tracks trends by determining trend direction with double MAs, judging timing assisted by RSI, and methods like moving take profit and stop loss. Further improvements can be achieved by optimizing parameters of MAs, RSI and profit/loss limits. The overall logic is clear and easy to understand and optimize. It is a practical and effective trend tracking strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | IS This a RENKO Chart |
| v_input_2 | false | Alternate TimeFrame Multiplier (0=none) |
| v_input_3 | false | Show Coloured MA Ribbons |
| v_input_4 | false | Show Ribbon Median MA Lines |
| v_input_5 | 0 | FAST MA Ribbon Type: : EMA | SMA | WMA | VWMA | SMMA | DEMA | TEMA | LAGMA | HullMA | ZEMA | TMA | SSMA |
| v_input_6 | 5 | FAST Ribbon Lower MA Length |
| v_input_7 | 25 | FAST Ribbon Upper Length |
| v_input_8 | 0 | SLOW MA Ribbon Type: : EMA | SMA | WMA | VWMA | SMMA | DEMA | TEMA | LAGMA | HullMA | ZEMA | TMA | SSMA |
| v_input_9 | 28 | SLOW Ribbon Lower MA Length |
| v_input_10 | 72 | SLOW Ribbon Upper Length |
| v_input_11 | 2018 | Backtest Start Year |
| v_input_12 | true | Backtest Start Month |
| v_input_13 | true | Backtest Start Day |
| v_input_14 | 0.02 | start |
| v_input_15 | 0.02 | increment |
| v_input_16 | 0.2 | maximum |
| v_input_17 | false | Use Opposite Trade as a Close Signal |
| v_input_18 | true | Colour Candles to Trade Order state |
| v_input_19 | 0 | What type of Orders: Longs+Shorts | LongsOnly | ShortsOnly | Flip |
| v_input_20 | true | Trailing Stop |
| v_input_21 | 3 | Trailing Stop (%) |
| v_input_22 | true | Take Profit |
| v_input_23 | 3 | Take Profit (%) |
| v_input_24 | true | Trailing Profit (%) |
| v_input_25 | false | Stop Loss |
| v_input_26 | 3 | Stop Loss (%) |
Source Pine Script
/*backtest
start: 2023-11-16 00:00:00
end: 2023-11-23 00:00:00
period: 3m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy(title="[WAI GUA]", shorttitle="[EOS] 1.0", overlay=false )

//study(title="[WAI GUA]", shorttitle="[EOS] 1.0", overlay=true)


//
// Use Alternate Anchor TF for MAs
uRenko    = input(true, title="IS This a RENKO Chart")
//
anchor     = input(0,minval=0,maxval=1440,title="Alternate TimeFrame Multiplier (0=none)")
//
src          = close //input(close, title="EMA Source")
showRibbons  = input(false,title="Show Coloured MA Ribbons")
showAvgs     = input(false,title="Show Ribbon Median MA Lines")

//
// Fast Ribbon MAs
// Lower MA - type, length
typeF1    = input(defval="EMA", title="FAST MA Ribbon Type: ", options=["SMA", "EMA", "WMA", "VWMA", "SMMA", "DEMA", "TEMA", "LAGMA", "HullMA", "ZEMA", "TMA", "SSMA"])
lenF1     = input(defval=5, title="FAST Ribbon Lower MA Length", minval=1)
gammaF1   = 0.33 //input(defval=0.33,title="Fast MA - Gamma for LAGMA")

// Upper MA - type, length
typeF11   = typeF1 //input(defval="WMA", title="FAST Ribbon Upper MA Type: ", options=["SMA", "EMA", "WMA", "VWMA", "SMMA", "DEMA", "TEMA", "LAGMA", "HullMA", "ZEMA", "TMA", "SSMA"])
lenF11    = input(defval=25, title="FAST Ribbon Upper Length", minval=2)
gammaF11  = 0.77 //input(defval=0.77,title="Slow MA - Gamma for LAGMA")

// Slow Ribbon MAs
// Lower MA - type, length
typeS1   = input(defval="EMA", title="SLOW MA Ribbon Type: ", options=["SMA", "EMA", "WMA", "VWMA", "SMMA", "DEMA", "TEMA", "LAGMA", "HullMA", "ZEMA", "TMA", "SSMA"])
lenS1    = input(defval=28, title="SLOW Ribbon Lower MA Length", minval=1)
gammaS1  = 0.33 //input(defval=0.33,title="Fast MA - Gamma for LAGMA")

// Upper MA - type, length
typeS16   = typeS1 //input(defval="WMA", title="SLOW Ribbon Upper MA Type: ", options=["SMA", "EMA", "WMA", "VWMA", "SMMA", "DEMA", "TEMA", "LAGMA", "HullMA", "ZEMA", "TMA", "SSMA"])
lenS16    = input(defval=72, title="SLOW Ribbon Upper Length", minval=2)
gammaS16  = 0.77 //input(defval=0.77,title="Slow MA - Gamma for LAGMA")

// - Constants
gold = #FFD700

// - FUNCTIONS
// - variant(type, src, len, gamma)
// ReturnMAEnter the selection variable, default isSMA,If Blank or Type.

// SuperSmoother filter
variant_supersmoother(src,len) =>
    a1 = exp(-1.414*3.14159 / len)
    b1 = 2*a1*cos(1.414*3.14159 / len)
    c2 = b1
    c3 = (-a1)*a1
    c1 = 1 - c2 - c3
    v9 = 0.0
    v9 := c1*(src + nz(src[1])) / 2 + c2*nz(v9[1]) + c3*nz(v9[2])
    v9

variant_smoothed(src,len) =>
    v5 = 0.0
    v5 := na(v5[1]) ? sma(src, len) : (v5[1] * (len - 1) + src) / len
    v5

variant_zerolagema(src,len) =>
    ema1 = ema(src, len)
    ema2 = ema(ema1, len)
    v10 = ema1+(ema1-ema2)
    v10

variant_doubleema(src,len) =>
    v2 = ema(src, len)
    v6 = 2 * v2 - ema(v2, len)
    v6

variant_tripleema(src,len) =>
    v2 = ema(src, len)
    v7 = 3 * (v2 - ema(v2, len)) + ema(ema(v2, len), len)               // Triple Exponential
    v7

//calc Laguerre
variant_lag(p,g) =>
    L0 = 0.0
    L1 = 0.0
    L2 = 0.0
    L3 = 0.0
    L0 := (1 - g)*p+g*nz(L0[1])
    L1 := -g*L0+nz(L0[1])+g*nz(L1[1])
    L2 := -g*L1+nz(L1[1])+g*nz(L2[1])
    L3 := -g*L2+nz(L2[1])+g*nz(L3[1])
    f = (L0 + 2*L1 + 2*L2 + L3)/6
    f

// return variant, defaults to SMA
variant(type, src, len, g) =>
    type=="EMA"     ? ema(src,len) :
      type=="WMA"   ? wma(src,len):
      type=="VWMA"  ? vwma(src,len) :
      type=="SMMA"  ? variant_smoothed(src,len) :
      type=="DEMA"  ? variant_doubleema(src,len):
      type=="TEMA"  ? variant_tripleema(src,len):
      type=="LAGMA" ? variant_lag(src,g) :
      type=="HullMA"? wma(2 * wma(src, len / 2) - wma(src, len), round(sqrt(len))) :
      type=="SSMA"  ? variant_supersmoother(src,len) :
      type=="ZEMA"  ? variant_zerolagema(src,len) :
      type=="TMA"   ? sma(sma(src,len),len) :
                      sma(src,len)

// - /variant

// If have anchor specified, calculate the base multiplier.
//mult  = isintraday ? anchor==0 or interval<=0 or interval>=anchor or anchor>1440? 1 : round(anchor/interval) : 1
//mult := isdwm?  1 : mult  // Only available Daily or less
mult = anchor>0 ? anchor : 1

//
high_  = uRenko? max(close,open) : high
low_   = uRenko? min(close,open) : low


//Adjust using anchor multiplierMALength

//Fast MA Ribbon
emaF1 = variant(typeF1, src, lenF1*mult, gammaF1)
emaF11 = variant(typeF11, src, lenF11*mult,gammaF11)
emafast = (emaF1+emaF11)/2 // Average of Upper and Lower MAs
//
//Slow MA Ribbon
emaS1 = variant(typeS1,src, lenS1*mult,gammaS1)
emaS16 = variant(typeS16, src, lenS16*mult, gammaS16)
emaslow = (emaS1+emaS16)/2 // Average of Upper and Lower MAs
//
// Count crossover candles
xup = 0
xdn = 0
fup = 0
fdn = 0
sup = 0
sdn = 0
//
xup := (emafast-emaslow)>0 and (emafast-emaslow)>(emafast[1]-emaslow[1]) ? nz(xup[1])+1 : 0
xdn := (emafast-emaslow)<0 and (emafast-emaslow)<(emafast[1]-emaslow[1]) ? nz(xdn[1])+1 : 0
fup := (emaF1-emaF11)>0 and (emaF1-emaF11)>(emaF1[1]-emaF11[1]) ? nz(fup[1])+1 : 0
fdn := (emaF1-emaF11)<0 and (emaF1-emaF11)<(emaF1[1]-emaF11[1]) ? nz(fdn[1])+1 : 0
sup := (emaS1-emaS16)>0 and (emaS1-emaS16)>(emaS1[1]-emaS16[1]) ? nz(sup[1])+1 : 0
sdn := (emaS1-emaS16)<0 and (emaS1-emaS16)<(emaS1[1]-emaS16[1]) ? nz(sdn[1])+1 : 0

//Fast EMA Final Color Rules
colFinal = fup>=2 ? aqua : fdn>=2 ? blue : gray
//Slow EMA Final Color Rules
colFinal2 = sup>=2 ? lime : sdn>=2 ? red : gray

//Fast EMA Plots
p1=plot(showRibbons?emaF1:na, title="Fast Ribbon Lower MA", style=line, linewidth=1, color=colFinal,transp=10)
p2=plot(showRibbons?emaF11:na, title="Fast Ribbon Upper MA", style=line, linewidth=1, color=colFinal,transp=10)
plot(showAvgs?emafast:na, title="Fast Ribbon Avg MA", style=circles,join=true, linewidth=1, color=gold,transp=10)

//
//fill(p1,p2,color=colFinal, transp=90)

//Slow EMA Plots
p3=plot(showRibbons?emaS1:na, title="Slow Ribbon Lower MA", style=line, linewidth=1, color=colFinal2,transp=10)
p4=plot(showRibbons?emaS16:na, title="Slow Ribbon Upper MA", style=line, linewidth=1, color=colFinal2,transp=10)
plot(showAvgs?emaslow:na, title="Slow Ribbon Avg MA", style=circles,join=true, linewidth=1, color=fuchsia,transp=10)
//
//fill(p3,p4, color=colFinal2, transp=90)

// Generate Buy Sell signals,
buy = 0
sell=0
//
buy  := xup>=2 and sup>=2 and fup>=2 ? nz(buy[1])>0?buy[1]+1  :1 : 0
sell := xdn>=2 and sdn>=2 and fdn>=2 ? nz(sell[1])>0?sell[1]+1 :1 : 0

////////////////////////
//* Backtest period selector *//
////////////////////////

testStartYear = input(2018, "Backtest Start Year",minval=1980)
testStartMonth = input(1, "Backtest Start Month",minval=1,maxval=12)
testStartDay = input(1, "Backtest Start Day",minval=1,maxval=31)
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)

testStopYear = 9999 //input(9999, "Backtest Stop Year",minval=1980)
testStopMonth = 12 // input(12, "Backtest Stop Month",minval=1,maxval=12)
testStopDay = 31 //input(31, "Backtest Stop Day",minval=1,maxval=31)
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)

testPeriod() => time >= testPeriodStart and time <= testPeriodStop ? true : false


///////////////
//* RSIStrategy *//
///////////////

//Indicator 1
lowerpc = lowest(low, 21)
upperpc = highest(high, 21)
midpc = avg(upperpc, lowerpc)

//Indicator 2
ma = sma(close, 50)
petd = ema(close,13)
rangema = ema(tr, 50)
upperkc = ma + rangema * 0.25
lowerkc = ma - rangema * 0.25

//Indicator 3
up = rma(max(change(close), 0), 5)
down = rma(-min(change(close), 0), 5)
rsi = down == 0 ? 100 : up == 0 ? 0 : 100 - (100 / (1 + up / down))

// PET-D
petdcolor = close > petd ? green : red
barcolor (petdcolor)


//Slope
SlopeL = midpc > midpc[5]
SlopeS = midpc < midpc[5]

//condition
CL = SlopeL == 1 and close > lowerkc and close < midpc and rsi < 35
CS = SlopeS == 1 and close < upperkc and close > midpc and rsi > 65

//Setup
RsiSL = CL == 1 and CL[1] != 1
RsiSS = CS == 1 and CS[1] != 1

/////////////////////
//* RSAParabolic indicator *//
/////////////////////
start = input(0.02)
increment = input(0.02)
maximum = input(0.2)

psar = sar(start, increment, maximum)

RSALE = false
RSASE = false
if (psar > high)
    RSALE = true
else
    RSALE = false

if (psar < low)
    RSASE = true
else
    RSASE = false


////////////////
//* Strategy component *//
////////////////

AQUA = #00FFFFFF
BLUE = #0000FFFF
RED  = #FF0000FF
LIME = #00FF00FF
GRAY = #808080FF
DARKRED   = #8B0000FF
DARKGREEN = #006400FF
//
fastExit  = input(false,title="Use Opposite Trade as a Close Signal")
clrBars   = input(true,title="Colour Candles to Trade Order state")
orderType = input("Longs+Shorts",title="What type of Orders", options=["Longs+Shorts","LongsOnly","ShortsOnly","Flip"])
//
isLong   = (orderType != "ShortsOnly")
isShort  = (orderType != "LongsOnly")

//////////////////////////
//* Trading status engine *//
//////////////////////////

// Track current trade status
longClose = false, longClose := nz(longClose[1],false)
shortClose = false, shortClose := nz(shortClose[1],false)
tradeState = 0, tradeState := nz(tradeState[1])
tradeState := tradeState==0 ?   buy==1 and (barstate.isconfirmed or barstate.ishistory) and isLong and not longClose and not shortClose? 1 :
                               sell==1  and (barstate.isconfirmed or barstate.ishistory) and isShort and not longClose and not shortClose? -1 :
                          tradeState : tradeState

////////////////////////////////////
//* Set the entry and special exit conditions here *//
////////////////////////////////////

//Enter state, when the state changes direction.
longCondition  = false
shortCondition = false
//longCondition  := longCondition != true ? change(tradeState) and tradeState==1 : true
//shortCondition := shortCondition != true ? change(tradeState) and tradeState==-1 : true
longCondition  := change(tradeState) and tradeState==1
shortCondition := change(tradeState) and tradeState==-1
if orderType=="Flip"
    temp = longCondition
    longCondition  := shortCondition
    shortCondition := temp
//end if

// Sell signal exit
longExitC  =  (emafast[1]<emaslow[1] and open<emaslow[1]) ? 1 : 0
shortExitC = (emafast[1]>emaslow[1] and open>emaslow[1]) ? 1 : 0

// changeExit conditions.
longExit = change(longExitC) and longExitC==1 and tradeState==1
shortExit = change(shortExitC) and shortExitC==1 and tradeState==-1

// -- debugs
//plotchar(tradeState,"tradeState at Event",location=location.bottom, color=#FF0000FF)
//plotchar(longCondition, title="longCondition",color=#FF0000FF)
//plotchar(shortCondition, title="shortCondition",color=#FF0000FF)
//plotchar(tradeState, title="tradeState",color=#006400FF)
// -- /debugs

////////////////////////////////
//======[ Trade entry price ]======//
////////////////////////////////

last_open_longCondition = na
last_open_shortCondition = na
last_open_longCondition := longCondition ? close : nz(last_open_longCondition[1])
last_open_shortCondition := shortCondition ? close : nz(last_open_shortCondition[1])

////////////////////////////
//======[ Location Status ]======//
////////////////////////////

in_longCondition  = tradeState == 1
in_shortCondition = tradeState == -1

////////////////////////
//======[ Tail stop ]======//
////////////////////////

isTS = input(true, "Trailing Stop")
ts = input(3.0, "Trailing Stop (%)", minval=0,step=0.1, type=float) /100

last_high = na
last_low = na
last_high_short = na
last_low_long = na
last_high := not in_longCondition ? na : in_longCondition and (na(last_high[1]) or high_ > nz(last_high[1])) ? high_ : nz(last_high[1])
last_high_short := not in_shortCondition ? na : in_shortCondition and (na(last_high[1]) or high_ > nz(last_high[1])) ? high_ : nz(last_high[1])
last_low := not in_shortCondition ? na : in_shortCondition and (na(last_low[1]) or low_ < nz(last_low[1])) ? low_ : nz(last_low[1])
last_low_long := not in_longCondition ? na : in_longCondition and (na(last_low[1]) or low_ < nz(last_low[1])) ? low_ : nz(last_low[1])

long_ts =  isTS and in_longCondition and not na(last_high) and (low_ <= last_high - last_high * ts) //and (last_high >= last_open_longCondition + last_open_longCondition * tsi)
short_ts = isTS and in_shortCondition and not na(last_low) and (high_ >= last_low + last_low * ts) //and (last_low <= last_open_shortCondition - last_open_shortCondition * tsi)


////////////////////////
//======[ Profit ]======//
////////////////////////

isTP = input(true, "Take Profit")
tp = input(3.0, "Take Profit (%)",minval=0,step=0.1,type=float) / 100
ttp = input(1.0, "Trailing Profit (%)",minval=0,step=0.1,type=float) / 100
ttp := ttp>tp ? tp : ttp

long_tp =  isTP and in_longCondition  and (last_high >= last_open_longCondition + last_open_longCondition * tp)   and (low_ <= last_high - last_high * ttp)
short_tp = isTP and in_shortCondition and (last_low <= last_open_shortCondition - last_open_shortCondition * tp) and (high_ >= last_low + last_low * ttp)

////////////////////////////
//======[ Stop loss ]======//
////////////////////////////

isSL = input(false, "Stop Loss")
sl = input(3.0, "Stop Loss (%)", minval=0,step=0.1, type=float) / 100
long_sl =  isSL and in_longCondition and (low_ <= last_open_longCondition - last_open_longCondition * sl)
short_sl = isSL and in_shortCondition and (high_ >= last_open_shortCondition + last_open_shortCondition * sl)

////////////////////////
//======[ Confrontation ]======//
////////////////////////

//Note: short exit signals are not forceful; no need to exert effort if the wedge continues.
long_sos = (fastExit or (not isTS and not isSL)) and longExit and in_longCondition
short_sos = (fastExit or (not isTS and not isSL)) and shortExit and in_shortCondition

////////////////////////////
//======[ Close signal ]======//
////////////////////////////

// Create a single shutdown for all different shutdown conditions, all conditions here are not repainted.
longClose :=  isLong and (long_tp or long_sl or long_ts or long_sos) and not longCondition
shortClose := isShort and (short_tp or short_sl or short_ts or short_sos) and not shortCondition
////////////////////////////
//======[ Plot color ]======//
////////////////////////////

longCloseCol = na
shortCloseCol = na
longCloseCol := long_tp ? green : long_sl ? maroon : long_ts ? purple : long_sos ? orange :longCloseCol[1]
shortCloseCol := short_tp ? green : short_sl ? maroon : short_ts ? purple : short_sos ? orange : shortCloseCol[1]
//
tpColor = isTP and in_longCondition ? lime : isTP and in_shortCondition ? lime : na
slColor = isSL and in_longCondition ? red : isSL and in_shortCondition ? red : na


//////////////////////////////////
//======[ Strategy chart ]======//
//////////////////////////////////

plot(isTS and in_longCondition?
     last_high - last_high * ts : na, "Long Trailing", fuchsia, style=2, linewidth=2,offset=1)
plot(isTP and in_longCondition and last_high < last_open_longCondition + last_open_longCondition * tp ?
     last_open_longCondition + last_open_longCondition * tp : na, "Long TP Active", tpColor, style=3,join=false, linewidth=2,offset=1)
plot(isTP and in_longCondition and last_high >= last_open_longCondition +  last_open_longCondition * tp ?
     last_high - last_high * ttp : na, "Long Trailing", black, style=2, linewidth=2,offset=1)
plot(isSL and in_longCondition and last_low_long > last_open_longCondition - last_open_longCondition * sl ?
     last_open_longCondition - last_open_longCondition * sl : na, "Long SL", slColor, style=3,join=false, linewidth=2,offset=1)

plot(isTS and in_shortCondition?
     last_low + last_low * ts : na, "Short Trailing", fuchsia, style=2, linewidth=2,offset=1)
plot(isTP and in_shortCondition and last_low > last_open_shortCondition - last_open_shortCondition * tp ?
     last_open_shortCondition - last_open_shortCondition * tp : na, "Short TP Active", tpColor, style=3,join=false, linewidth=2,offset=1)
plot(isTP and in_shortCondition and last_low <= last_open_shortCondition -  last_open_shortCondition * tp ?
     last_low + last_low * ttp : na, "Short Trailing", black, style=2, linewidth=2,offset=1)
plot(isSL and in_shortCondition and last_high_short < last_open_shortCondition + last_open_shortCondition * sl ?
     last_open_shortCondition + last_open_shortCondition * sl : na, "Short SL", slColor, style=3,join=false, linewidth=2,offset=1)

bclr = not clrBars ? na : tradeState==0 ? GRAY :
                          in_longCondition ? close<last_open_longCondition? DARKGREEN : LIME :
                          in_shortCondition ? close>last_open_shortCondition? DARKRED : RED : GRAY
barcolor(bclr,title="Trade State Bar Colouring")


//////////////////////////////////
//======[ Strategy Entry and Exit ]======//
//////////////////////////////////

if testPeriod() and isLong
    strategy.entry("Long", 1, when=longCondition)
    strategy.close("Long", when=longClose )

if testPeriod() and isShort
    strategy.entry("Short", 0,  when=shortCondition)
    strategy.close("Short", when=shortClose )

// --- Debugs
//plotchar(longExit,title="longExit",location=location.bottom,color=na)
//plotchar(longCondition,title="longCondition",location=location.bottom,color=na)
//plotchar(in_longCondition,title="in_longCondition",location=location.bottom,color=na)
//plotchar(longClose,title="longClose",location=location.bottom,color=na,color=na)
//plotchar(buy,title="buy",location=location.bottom,color=na)
// --- /Debugs
//Change Background When Opening Position
bgcolor( in_longCondition ? lime : na, transp=90)
bgcolor( in_shortCondition ? red : na, transp=90)

////////////////////////////
//======[ Reset variables ]======//
////////////////////////////


if longClose or not in_longCondition
    last_high := na
    last_high_short := na

if shortClose or not in_shortCondition
    last_low := na
    last_low_long := na

if longClose or shortClose
    tradeState := 0
    in_longCondition := false
    in_shortCondition := false


//plotchar(tradeState,"tradeState at EOF",location=location.bottom, color=na)
// EOFPublished by ChaoZhang on the FMZ strategy square · last modified 2023-11-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Reversal-Moving-Average-Combination-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- MACD RSI and EMA StrategyPine Script · Mean reversion · 1d
- RePaNoCHa Quantitative Trading StrategyPine Script · Mean reversion · 1d
- Johnys BOTPine Script · Mean reversion · 4h
- 15 MIN BTCUSDTPERP BOTPine Script · Mean reversion · 45m
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d