Strategy vault / Mean reversion
Momentum Reversal Strategy 437557
This strategy is a momentum reversal strategy based on moving averages and the relative strength index (RSI). It uses the crossover of fast and slow moving averages along with overbought and oversold signals to…
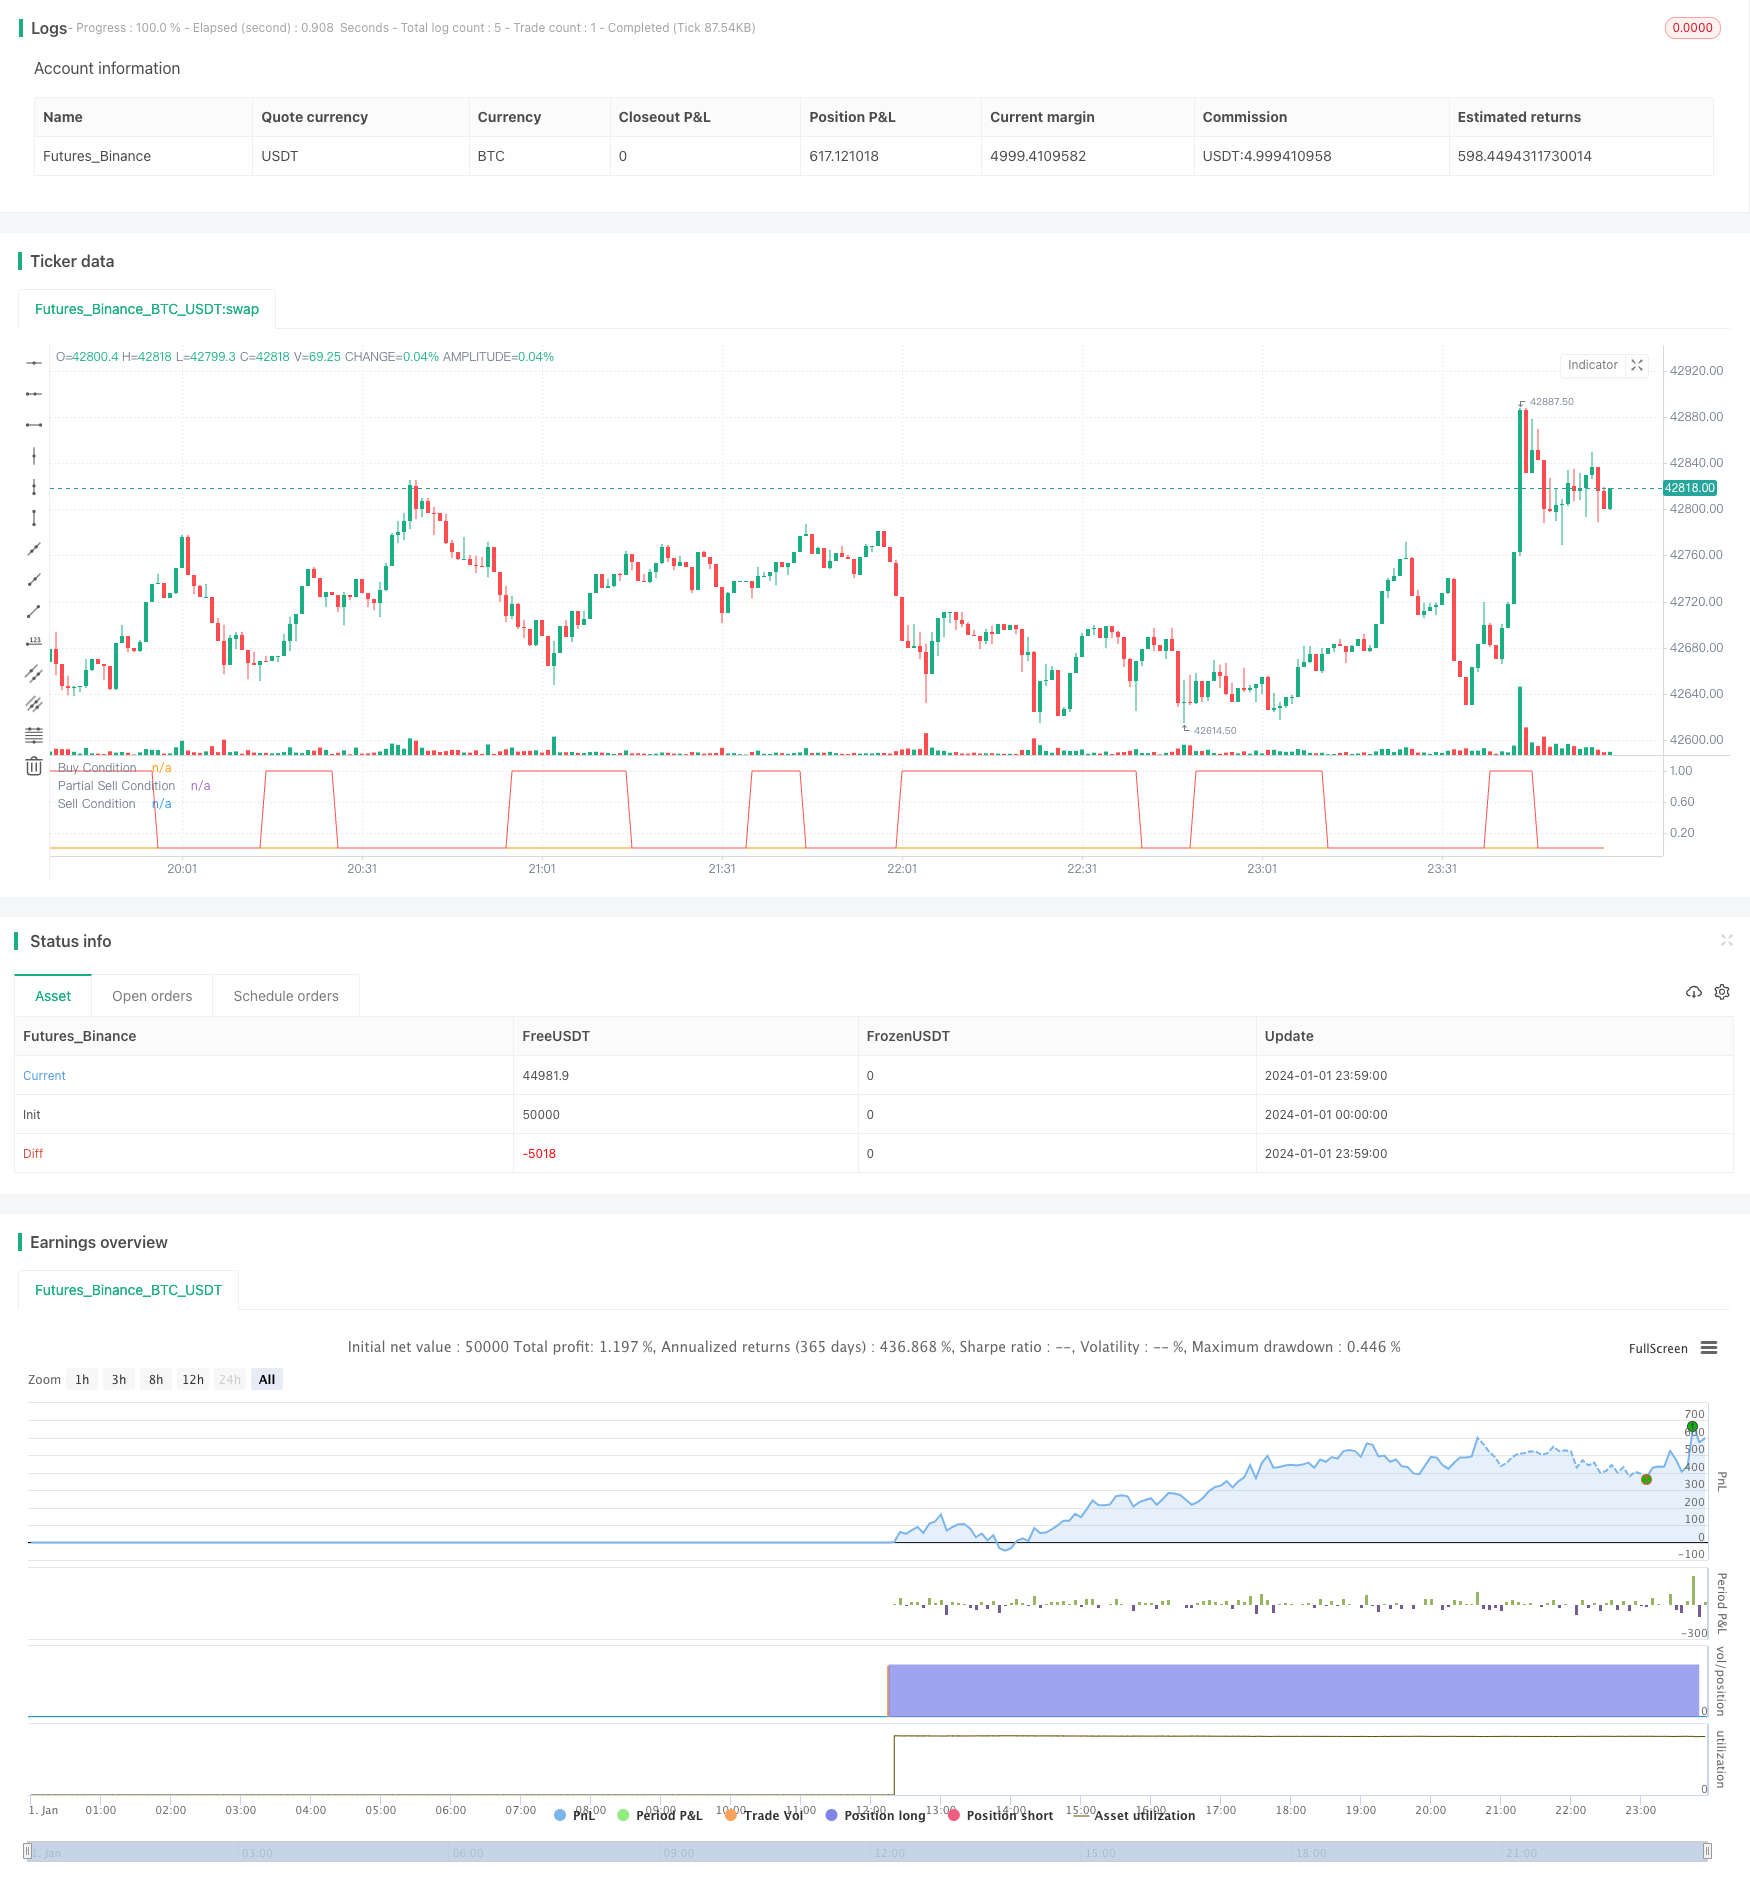
Overview
This strategy is a momentum reversal strategy based on moving averages and the relative strength index (RSI). It uses the crossover of fast and slow moving averages along with overbought and oversold signals to determine entries and exits.
Strategy Logic
The strategy uses a 14-day moving average as the fast signal line and a 28-day moving average as the slow line. It also incorporates the RSI indicator to gauge whether the market is overbought or oversold.
When the 14-day MA crosses above the 28-day MA and the RSI is below 30 or the RSI is below 13, it signals a reversal in the momentum to the upside, prompting a long entry. When the 14-day MA crosses back below the 28-day MA, it signals a failure of the momentum reversal which prompts a partial profit taking exit.
In addition, the strategy has a partial profit-taking mechanism. When the profit of the open position reaches the set take profit level (default 8%), it will partially take profit (default selling 50%).
Advantage Analysis
The strategy combines the advantages of moving averages while avoiding whipsaw losses.
Using fast and slow moving averages filters out some noise.
RSI gauges overbought and oversold levels, avoiding chasing new highs.
The partial profit-taking locks in some profits and reduces risk.
Risk Analysis
Dual moving average crossovers can produce whipsaws, leading to losses. This strategy uses the RSI to provide additional confirmation, filtering some whipsaw signals.
Partial profit-taking may result in missing larger moves. The take profit level can be adjusted to balance risk versus reward.
Optimization Directions
Test different parameter combinations of moving averages to find optimal settings.
Test different RSI threshold levels.
Adjust partial profit-taking take profit level and sell ratio to balance risk/reward.
Conclusion
Overall this is a typical mean reversion strategy. It uses fast/slow MA crosses to determine market turns supplemented by RSI to filter signals. It also implements partial profit taking to lock in some profits. The strategy is simple yet practical. Parameters can be adjusted to suit different market conditions.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | Length |
| v_input_2 | 8 | Take Profit |
| v_input_3 | 50 | Percent of Quantity to Sell |
| v_input_4 | true | Close Overbought and Take Profit |
| v_input_5 | 14 | SMA Signal Period |
| v_input_6 | 28 | SMA Longer Period |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-02 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy(title = "14/28 SMA and RSI", shorttitle = "14/28 SMA and RSI", overlay = false, pyramiding = 0, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, currency = currency.USD)
src = close, len = input(14, minval=1, title="Length")
take_Profit=input(8, title="Take Profit")
quantityPercentage=input(50, title="Percent of Quantity to Sell")
closeOverbought=input(true, title="Close Overbought and Take Profit")
up = rma(max(change(src), 0), len)
down = rma(-min(change(src), 0), len)
rsi = down == 0 ? 100 : up == 0 ? 0 : 100 - (100 / (1 + up / down))
longCondition = 0
sellCondition = 0
takeProfit = 0
quantityRemainder = 100
smaSignal = input(14, title="SMA Signal Period")
smaLong = input(28, title="SMA Longer Period")
if ((sma(close, smaSignal) >= sma(close, smaLong) and rsi<= 30) or (rsi<=13)) and strategy.position_size==0
    longCondition:=1

if longCondition==1
    strategy.entry("Buy", strategy.long)

profit = ((close-strategy.position_avg_price)/strategy.position_avg_price) * 100

if sma(close, smaSignal) <= sma(close, smaLong) and strategy.position_size>1
    sellCondition := 1

if strategy.position_size>=1
    if closeOverbought == true
        if profit>=take_Profit and takeProfit == 0
            strategy.exit("Take Profit", profit=take_Profit, qty_percent=quantityPercentage)
            takeProfit:=1
            quantityRemainder:=100-quantityPercentage
    if sellCondition == 1 and quantityRemainder<100
        strategy.close("Buy")

    if closeOverbought == false and rsi>70
        strategy.close("Take Profit")

plot(longCondition, "Buy Condition", green)
plot(takeProfit, "Partial Sell Condition", orange)
plot(sellCondition, "Sell Condition", red)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-03. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Reversal-Strategy-437557.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- Advanced Strategy with Volume and Price Pullback Multiple Take ProfitPine Script · Mean reversion · 1h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d