Momentum Tracking CCI Strategy
This strategy is based on the Commodity Channel Index (CCI) indicator, aiming to go long in oversold conditions and go short in overbought conditions. It also optionally uses an Exponential Moving Average (EMA)…
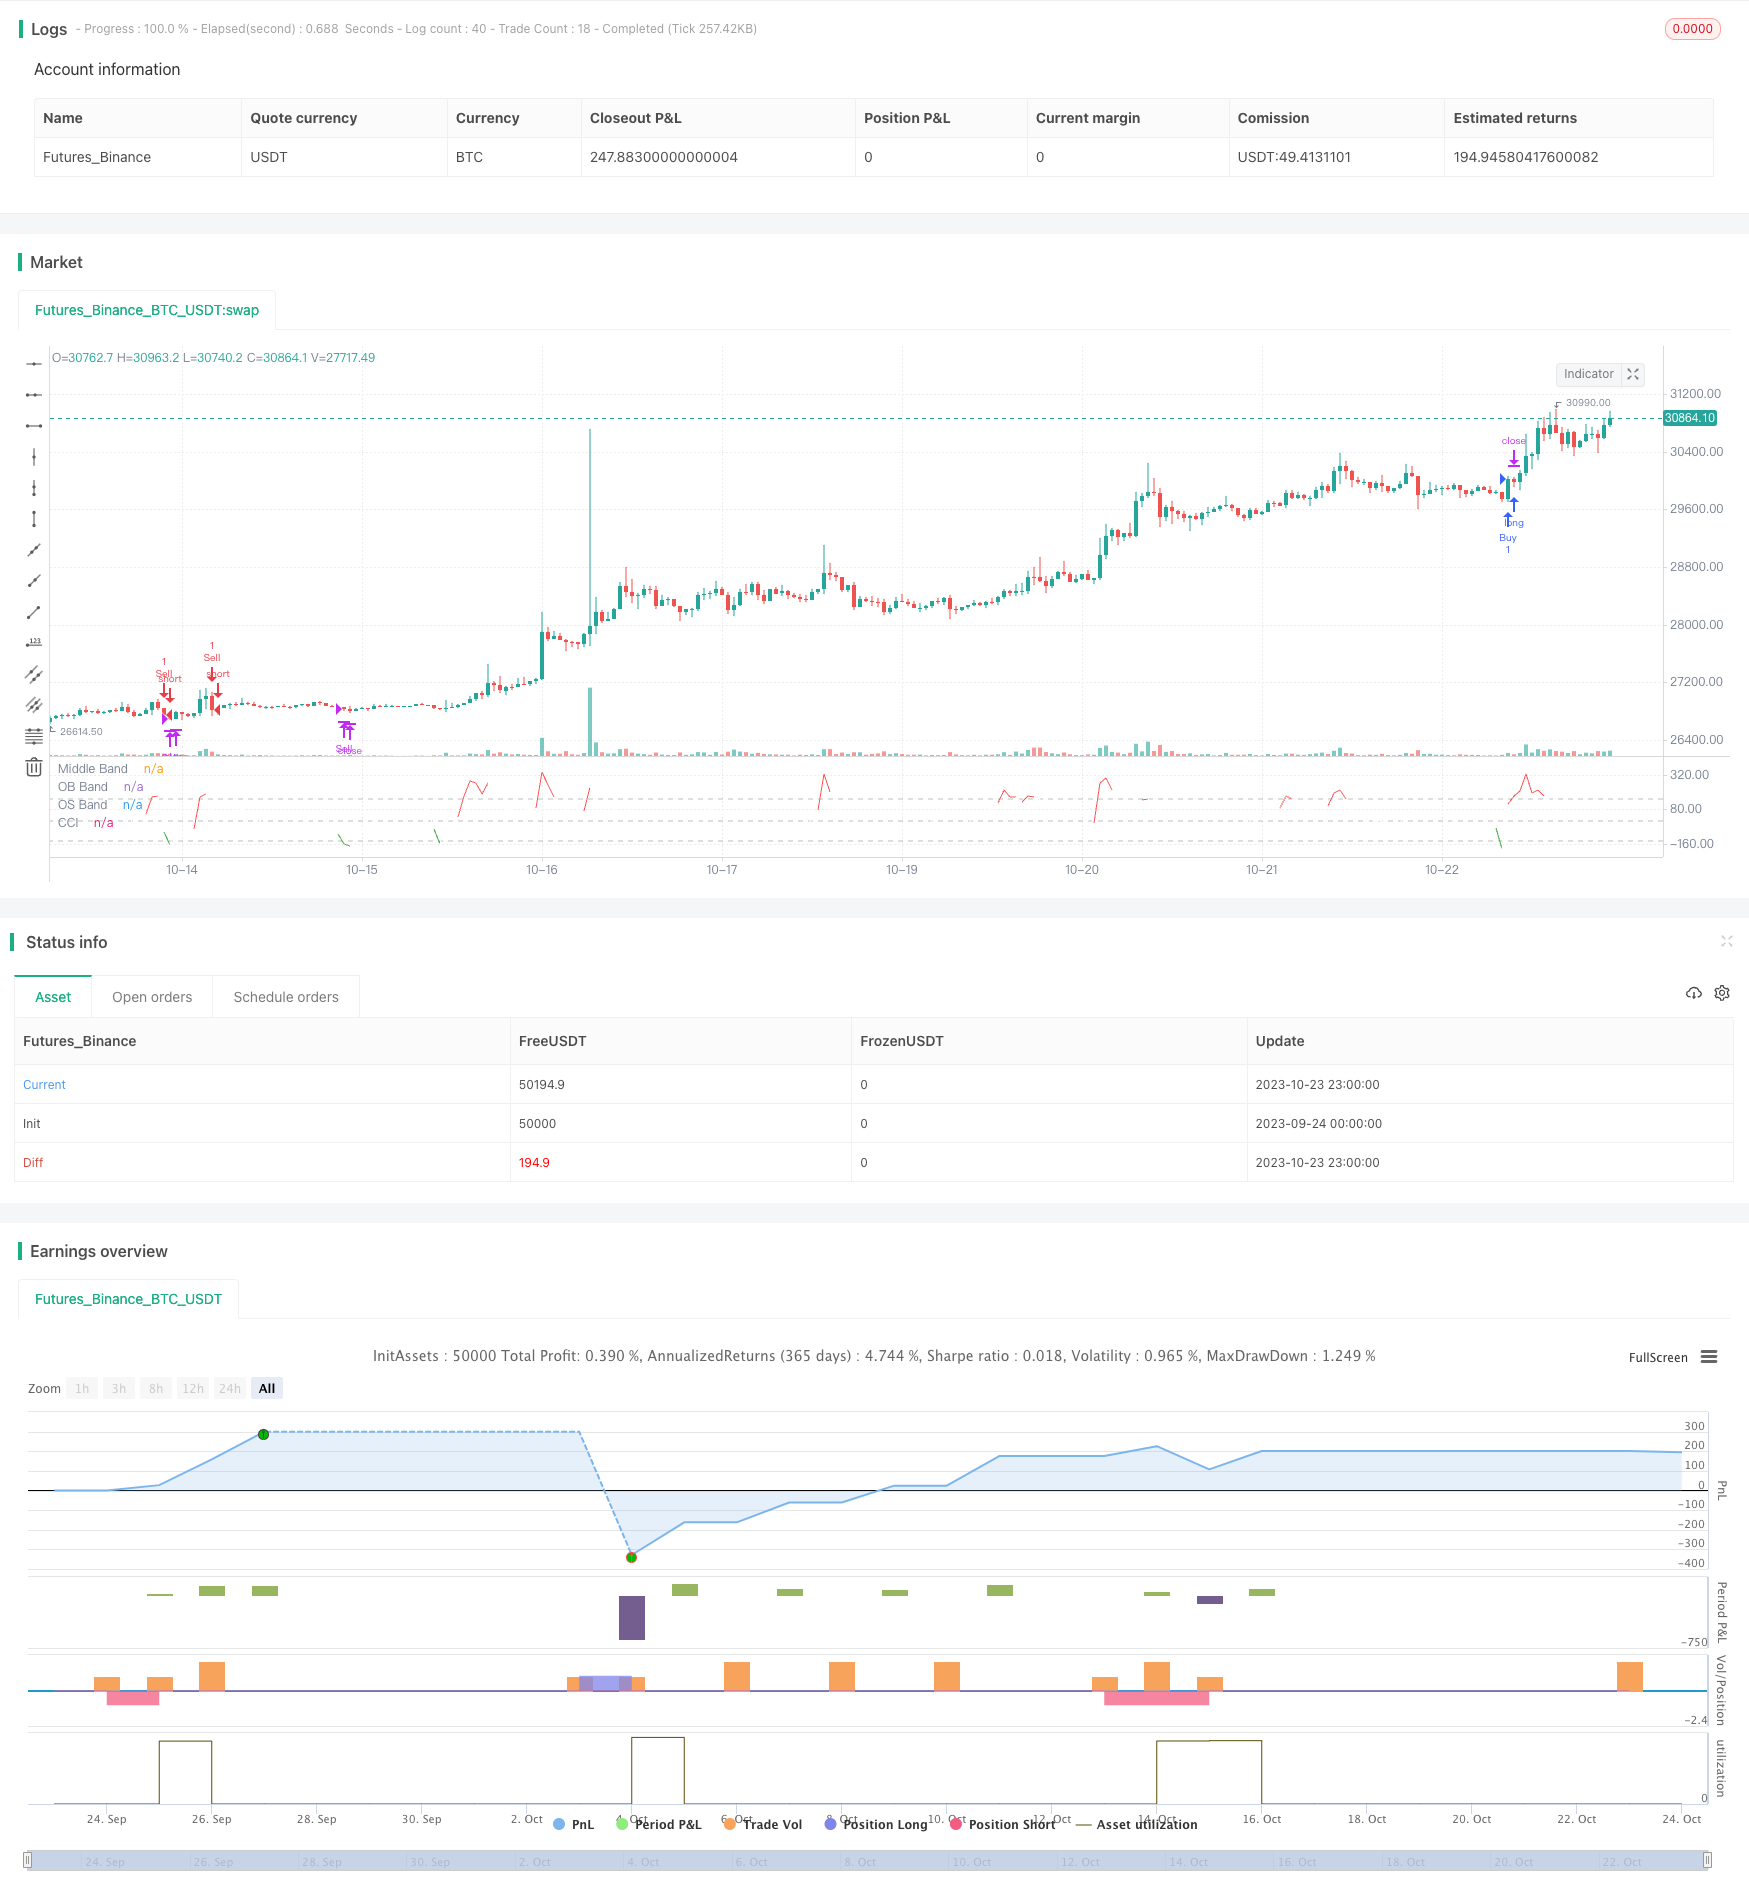
Overview
This strategy is based on the Commodity Channel Index (CCI) indicator, aiming to go long in oversold conditions and go short in overbought conditions. It also optionally uses an Exponential Moving Average (EMA) filter to only trade in the direction of the trend. The strategy also provides fixed percentage or Average True Range (ATR) based stop loss and take profit.
Strategy Logic
Use CCI indicator to determine market trend
CCI measures momentum by comparing current price to the average price over a period
CCI above 150 is overbought, below -100 is oversold
Optionally use EMA filter
Only go long when price is above EMA, and short when below EMA
Use EMA to determine trend direction, avoid counter-trend trading
Provide two types of stop loss and take profit
Fixed percentage based stop loss and take profit: Use fixed percentage of entry price
ATR based stop loss and take profit: Use ATR multiplier for stop loss, calculate take profit based on risk reward ratio
Entry conditions
Go long when CCI crosses above -100
Go short when CCI crosses below 150
If EMA enabled, only enter when price is on right side of EMA
Exit conditions
Close position when stop loss or take profit is hit
Close position when CCI re-enters overbought/oversold region
Plotting
- Plot CCI indicator, color code regions
Advantage Analysis
Use CCI overbought/oversold for entry, a classic usage of CCI
Optional EMA ensures trading with the trend, avoid reversals
Provide two types of stop loss/take profit for flexibility
Close on CCI signal again locks in reversal profit
Plotting highlights CCI signals clearly
Simple and clear logic, easy to understand and optimize
Risk Analysis
CCI has lagging effect, may miss reversals or give false signals
Wrong EMA parameters may miss trends or render strategy ineffective
Fixed percentage stop loss/take profit less adaptive to market changes
ATR stop loss/take profit sensitive to ATR period, should optimize
Larger drawdown risk, position sizing should be adjusted
Performance varies across market conditions, re-evaluate parameters
Optimization Directions
Evaluate CCI periods to find optimal parameter combinations
Test different EMA periods for best trend estimation
Adjust stop loss/take profit for optimal risk reward ratio
Add other filters like volume to further avoid false signals
Combine with trendlines/chart patterns for pattern confirmation
Add position sizing rules like fixed size to control drawdown
Backtest across different market conditions, dynamically adjust
Summary
The strategy utilizes the classic CCI overbought/oversold principles for entry. The EMA filter controls trend trading. Two types of stop loss/take profit provided for flexibility. Plotting highlights signals clearly. Simple and clear logic, easy to understand and optimize. Further improvements can be made via parameter tuning, adding filters, risk control etc.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | CCI Length |
| v_input_int_1 | 150 | Overbought |
| v_input_int_2 | -140 | Oversold |
| v_input_2 | true | Use EMA |
| v_input_3 | 55 | EMA Length |
| v_input_4 | true | (?TP/SL Method)Percentage TP/SL |
| v_input_5 | false | ATR TP/SL |
| v_input_float_1 | 10 | Take Profit (%) |
| v_input_float_2 | 10 | Stop Loss (%) |
| v_input_6 | 20 | ATR Length |
| v_input_7 | 4 | ATR SL Multiplier |
| v_input_8 | 2 | Risk Reward Ratio |
Source Pine Script
/*backtest
start: 2023-09-24 00:00:00
end: 2023-10-24 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © alifer123

//@version=5
// strategy("CCI+EMA Strategy with Percentage or ATR TP/SL [Alifer]", shorttitle = "CCI_EMA_%/ATR_TP/SL", overlay=false,
//      initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=10, commission_type=strategy.commission.percent, commission_value=0.045)

length = input(14, "CCI Length")
overbought = input.int(150, step = 10, title = "Overbought")
oversold = input.int(-140, step = 10, title = "Oversold")
src = hlc3
ma = ta.sma(src, length)
cci = (src - ma) / (0.015 * ta.dev(src, length))

// EMA
useEMA = input(true, "Use EMA", tooltip = "Only enters long when price is above the EMA, only enters short when price is below the EMA")
emaLength = input(55, "EMA Length")
var float ema = na
if useEMA
    ema := ta.ema(src, emaLength)

// Take Profit and Stop Loss Method
tpSlMethod_percentage = input(true, "Percentage TP/SL", group="TP/SL Method")
tpSlMethod_atr = input(false, "ATR TP/SL", group="TP/SL Method")

// Percentage-based Take Profit and Stop Loss
tp_percentage = input.float(10.0, title="Take Profit (%)", step=0.1, group="TP/SL Method")
sl_percentage = input.float(10.0, title="Stop Loss (%)", step=0.1, group="TP/SL Method")

// ATR-based Take Profit and Stop Loss
atrLength = input(20, title="ATR Length", group="TP/SL Method")
atrMultiplier = input(4, title="ATR SL Multiplier", group="TP/SL Method")
riskRewardRatio = input(2, title="Risk Reward Ratio", group="TP/SL Method")

// Calculate TP/SL levels based on the selected method, or leave them undefined if neither method is selected
longTP = tpSlMethod_percentage ? strategy.position_avg_price * (1 + tp_percentage / 100) : na
longSL = tpSlMethod_percentage ? strategy.position_avg_price * (1 - sl_percentage / 100) : na
shortTP = tpSlMethod_percentage ? strategy.position_avg_price * (1 - tp_percentage / 100) : na
shortSL = tpSlMethod_percentage ? strategy.position_avg_price * (1 + sl_percentage / 100) : na

if tpSlMethod_atr
    longSL := strategy.position_avg_price - ta.atr(atrLength) * atrMultiplier
    longTP := ((strategy.position_avg_price - longSL) * riskRewardRatio) + strategy.position_avg_price
    shortSL := strategy.position_avg_price + ta.atr(atrLength) * atrMultiplier
    shortTP := ((strategy.position_avg_price - shortSL) * riskRewardRatio) - strategy.position_avg_price

// Enter long position when CCI crosses below oversold level and price is above EMA
longCondition = ta.crossover(cci, oversold) and (not useEMA or close > ema)
if longCondition
    strategy.entry("Buy", strategy.long)

// Enter short position when CCI crosses above overbought level and price is below EMA
shortCondition = ta.crossunder(cci, overbought) and (not useEMA or close < ema)
if shortCondition
    strategy.entry("Sell", strategy.short)

// Close long positions with Take Profit or Stop Loss
if strategy.position_size > 0
    strategy.exit("Long Exit", "Buy", limit=longTP, stop=longSL)

// Close short positions with Take Profit or Stop Loss
if strategy.position_size < 0
    strategy.exit("Short Exit", "Sell", limit=shortTP, stop=shortSL)

// Close positions when CCI crosses back above oversold level in long positions or below overbought level in short positions
if ta.crossover(cci, overbought)
    strategy.close("Buy")
if ta.crossunder(cci, oversold)
    strategy.close("Sell")

// Plotting
color_c = cci > overbought ? color.red : (cci < oversold ? color.green : color.white)
plot(cci, "CCI", color=color_c)
hline(0, "Middle Band", color=color.new(#787B86, 50))
obband = hline(overbought, "OB Band", color=color.new(#78867a, 50))
osband = hline(oversold, "OS Band", color=color.new(#867878, 50))
fill(obband, osband, color=color.new(#787B86, 90))
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Tracking-CCI-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Oscillator Candles Momentum Trading StrategyPine Script · Momentum · 1h
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- Momentum Strategy Based on DEMA and EMA Crossover with ATR Volatility FilterPine Script · Momentum · 1h
- Momentum Trend Optimization Combination StrategyPine Script · Momentum · 1h
- Moving Average Candle Regression StrategyPine Script · Momentum · 15m