Momentum Trend Tracker Strategy
The "Momentum Trend Tracker" strategy is a meticulously crafted tool designed for traders who seek to leverage the confluence of volatility, trend, and momentum indicators for informed decision-making. The uniqueness…
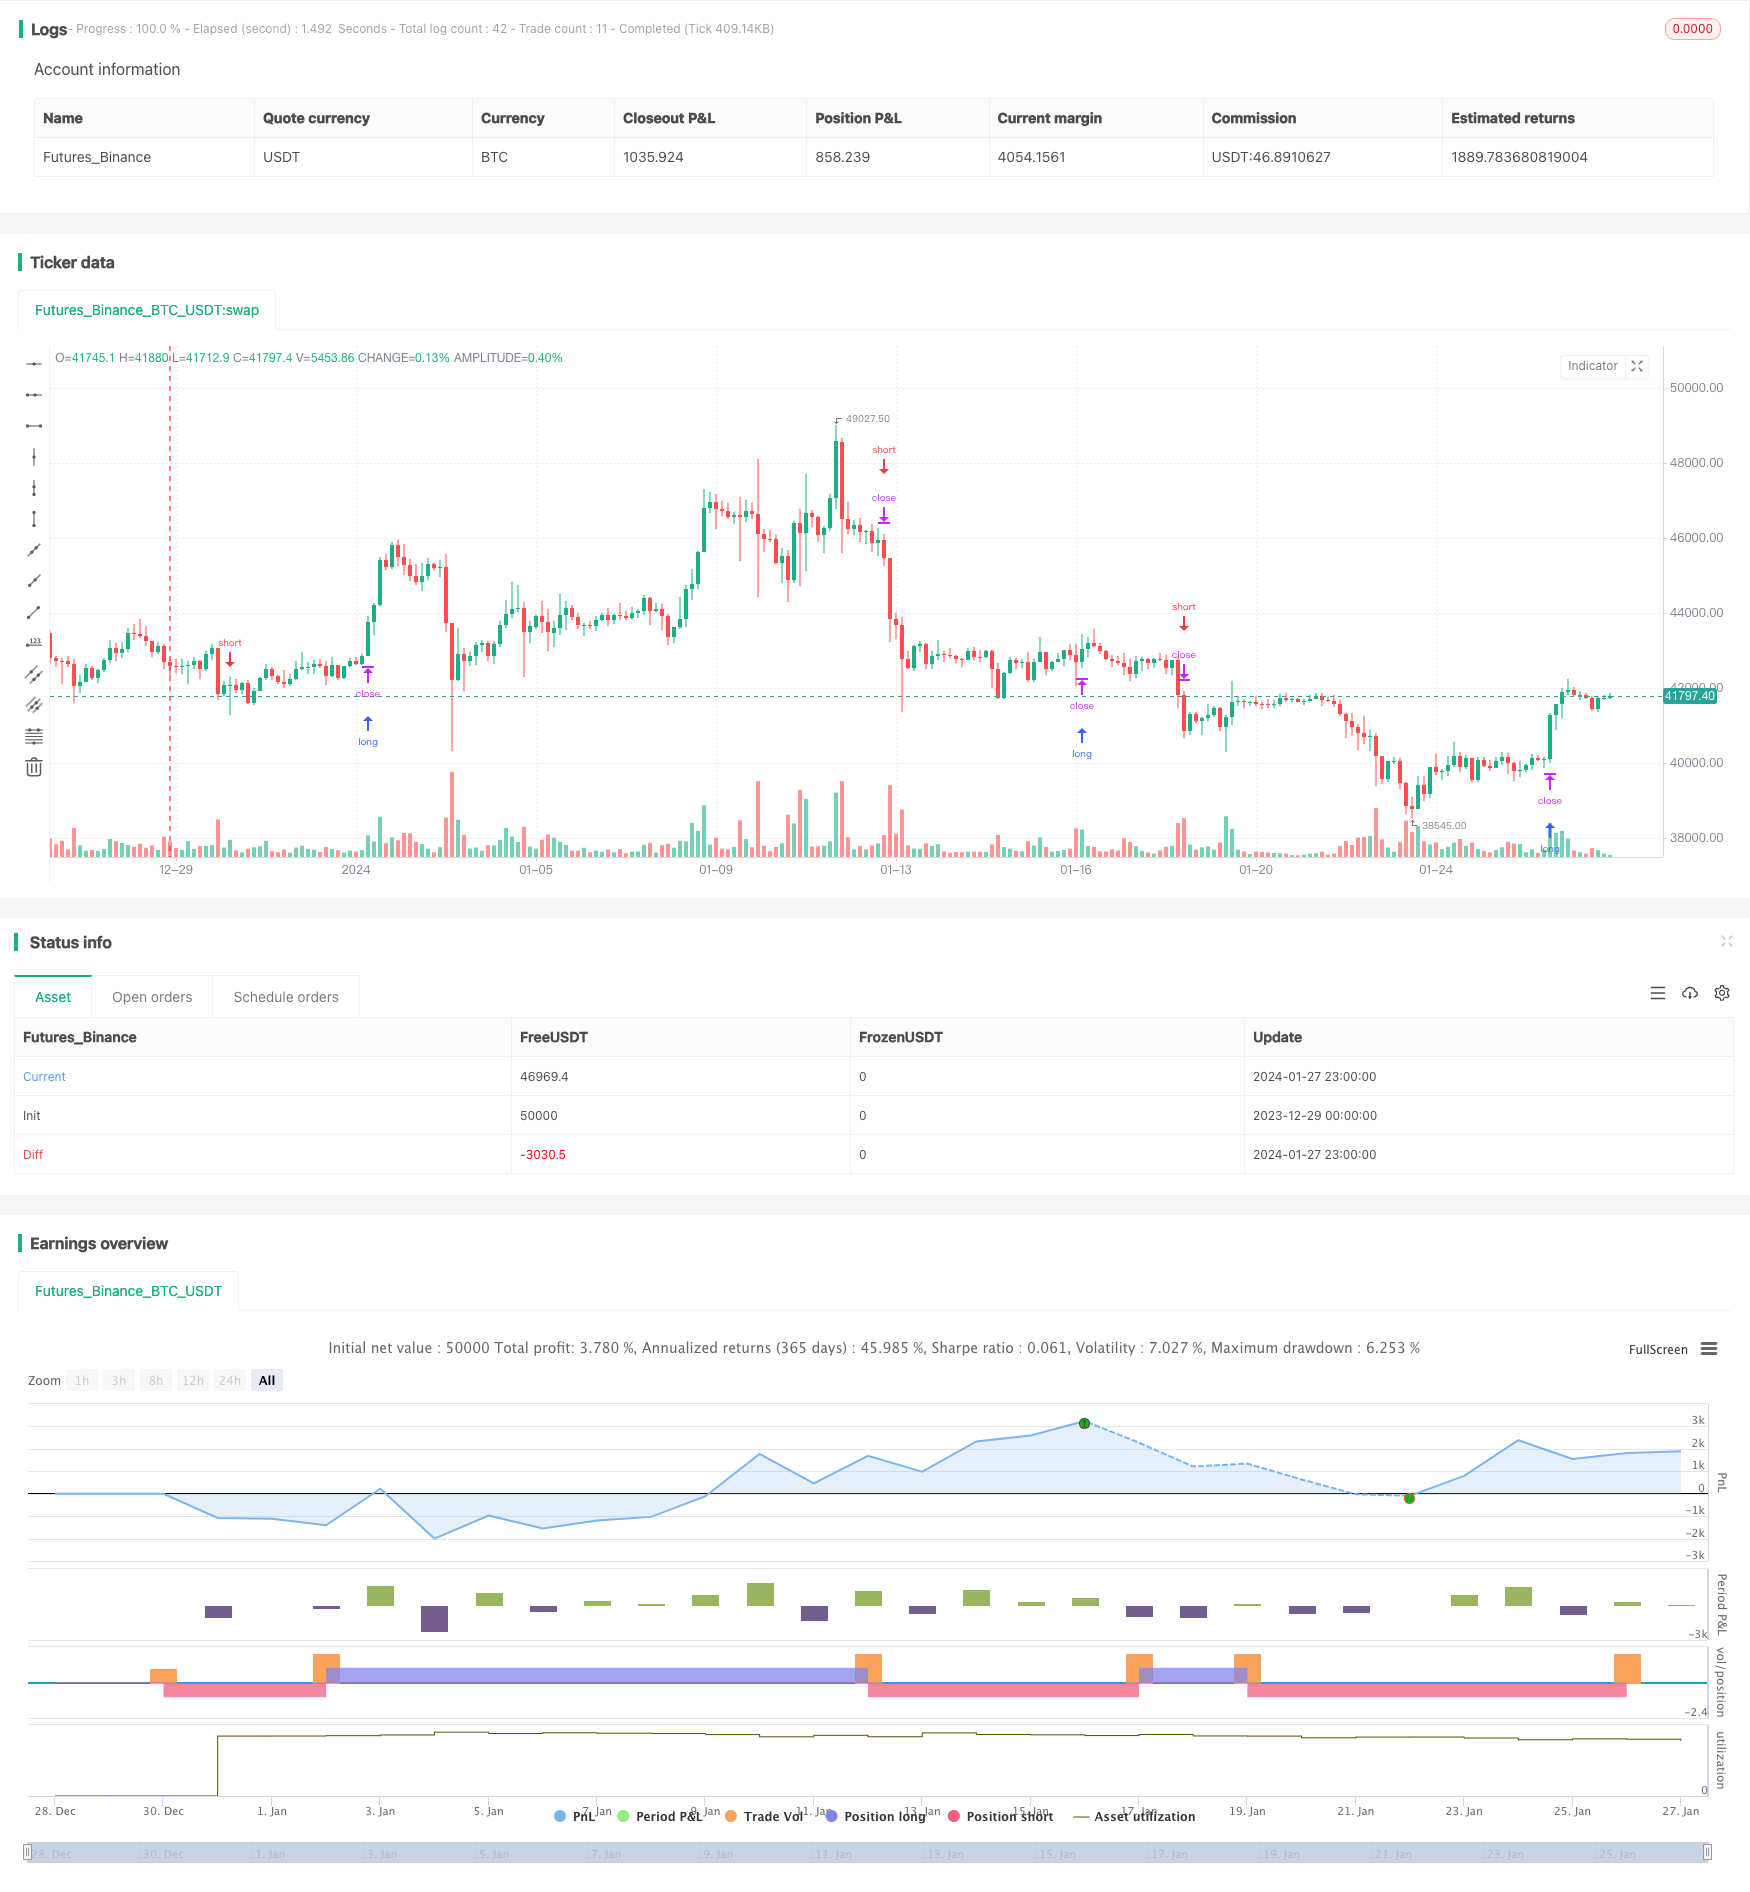
Overview
The "Momentum Trend Tracker" strategy is a meticulously crafted tool designed for traders who seek to leverage the confluence of volatility, trend, and momentum indicators for informed decision-making. The uniqueness of this strategy lies in its integration of Average True Range (ATR) for dynamic stop loss positioning, Simple Moving Average (SMA) for trend filtering, and Moving Average Convergence Divergence (MACD) for entry confirmation.
Strategy Logic
Volatility Assessment
The strategy employs ATR to dynamically adjust stop levels catering to changing market volatility. This approach ensures stop levels respond more sensitively to current market conditions, potentially reducing the risk of premature stop-outs.
Trend Filtering
By using an SMA, the strategy filters entries ensuring alignment with the overall market trend. This filter is crucial to avoid trades against the prevailing market direction, thus increasing the likelihood of successful trades.
Momentum Confirmation
The MACD indicator serves as a momentum filter, confirming trade entries by ensuring they coincide with the prevailing momentum. This additional layer of confirmation helps in filtering out false signals and enhances the strategy's reliability.
Advantage Analysis
The integration of ATR, SMA, and MACD in the strategy is not merely a mashup of indicators. Instead, each component plays a critical role in the trade decision process from entry to exit. This holistic approach provides traders with a comprehensive strategy leveraging multiple market dimensions, offering a unique and valuable tool for trend-following and momentum-based trading.
Risk Analysis
The strategy relies heavily on indicator configurations, improper parameter tuning may lead to incorrect signals. Additionally, low SNR signals near trend inflection points may cause whipsaws. To mitigate these risks, parameter optimization is recommended along with incorporating other confirming indicators to improve robustness.
Optimization Directions
The strategy can be dynamically optimized by introducing machine learning algorithms to tune parameters according to current market conditions. Additionally, incorporating more data sources like news events, social media data, etc. may aid in judging market turning points and reduce late entries. Moreover, the strategy can be expanded across multiple timeframes or instruments to capture more trading opportunities.
Conclusion
The "Momentum Trend Tracker" strategy fully utilizes the strengths of multiple indicators to provide a valuable tool for trade decision-making. Excellent parameter tuning and market understanding are key to unlocking its value. Despite room for improvements, it offers experienced traders a unique perspective worth dedicating time and effort to test and optimize.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 20 | ATR Length |
| v_input_2 | 0.75 | ATR Multiplier |
| v_input_3 | 32 | SMA Period |
| v_input_4 | 12 | MACD Short Term |
| v_input_5 | 26 | MACD Long Term |
| v_input_6 | 9 | MACD Signal Smoothing |
Source Pine Script
/*backtest
start: 2023-12-29 00:00:00
end: 2024-01-28 00:00:00
period: 3h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("trend_hunter", overlay=true)

length = input(20, title="ATR Length")
numATRs = input(0.75, title="ATR Multiplier")
atrs = ta.sma(ta.tr, length) * numATRs

// Trend Filter
smaPeriod = input(32, title="SMA Period")
sma = ta.sma(close, smaPeriod)

// MACD Filter
macdShortTerm = input(12, title="MACD Short Term")
macdLongTerm = input(26, title="MACD Long Term")
macdSignalSmoothing = input(9, title="MACD Signal Smoothing")

[macdLine, signalLine, _] = ta.macd(close, macdShortTerm, macdLongTerm, macdSignalSmoothing)

// Long Entry with Trend and MACD Filter
longCondition = close > sma and close[1] <= sma[1] and macdLine > signalLine
strategy.entry("Long", strategy.long, stop=close + atrs, when=longCondition, comment="Long")

// Short Entry with Trend and MACD Filter
shortCondition = close < sma and close[1] >= sma[1] and macdLine < signalLine
strategy.entry("Short", strategy.short, stop=close - atrs, when=shortCondition, comment="Short")

//plot(strategy.equity, title="equity", color=color.red, linewidth=2, style=plot.style_area)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Trend-Tracker-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- Multi Indicator Trend Momentum Trading Strategy with Dynamic Risk Management SystemPine Script · Momentum · 1h
- Multi Indicator Trend Momentum Trading Strategy An Optimized Quantitative Trading System Based on Bollinger Bands Fibonacci and ATRPine Script · Momentum · 1h
- Multi MA Trend Strength Capture with Momentum Profit Taking StrategyPine Script · Momentum · 2h
- Multi Trend Momentum Crossover Strategy with Volatility Optimization SystemPine Script · Momentum · 1d
- AVMQTS Adaptive Volatility and Momentum Quantitative Trading System AVMQTSPine Script · Momentum · 1d