Strategy vault / Trend following
Moving Average Crossover Trend Following Strategy 441080
The Moving Average Crossover Trend Following strategy is a quantitative trading strategy that tracks market trends. The strategy generates trading signals by calculating fast and slow moving averages and catching…
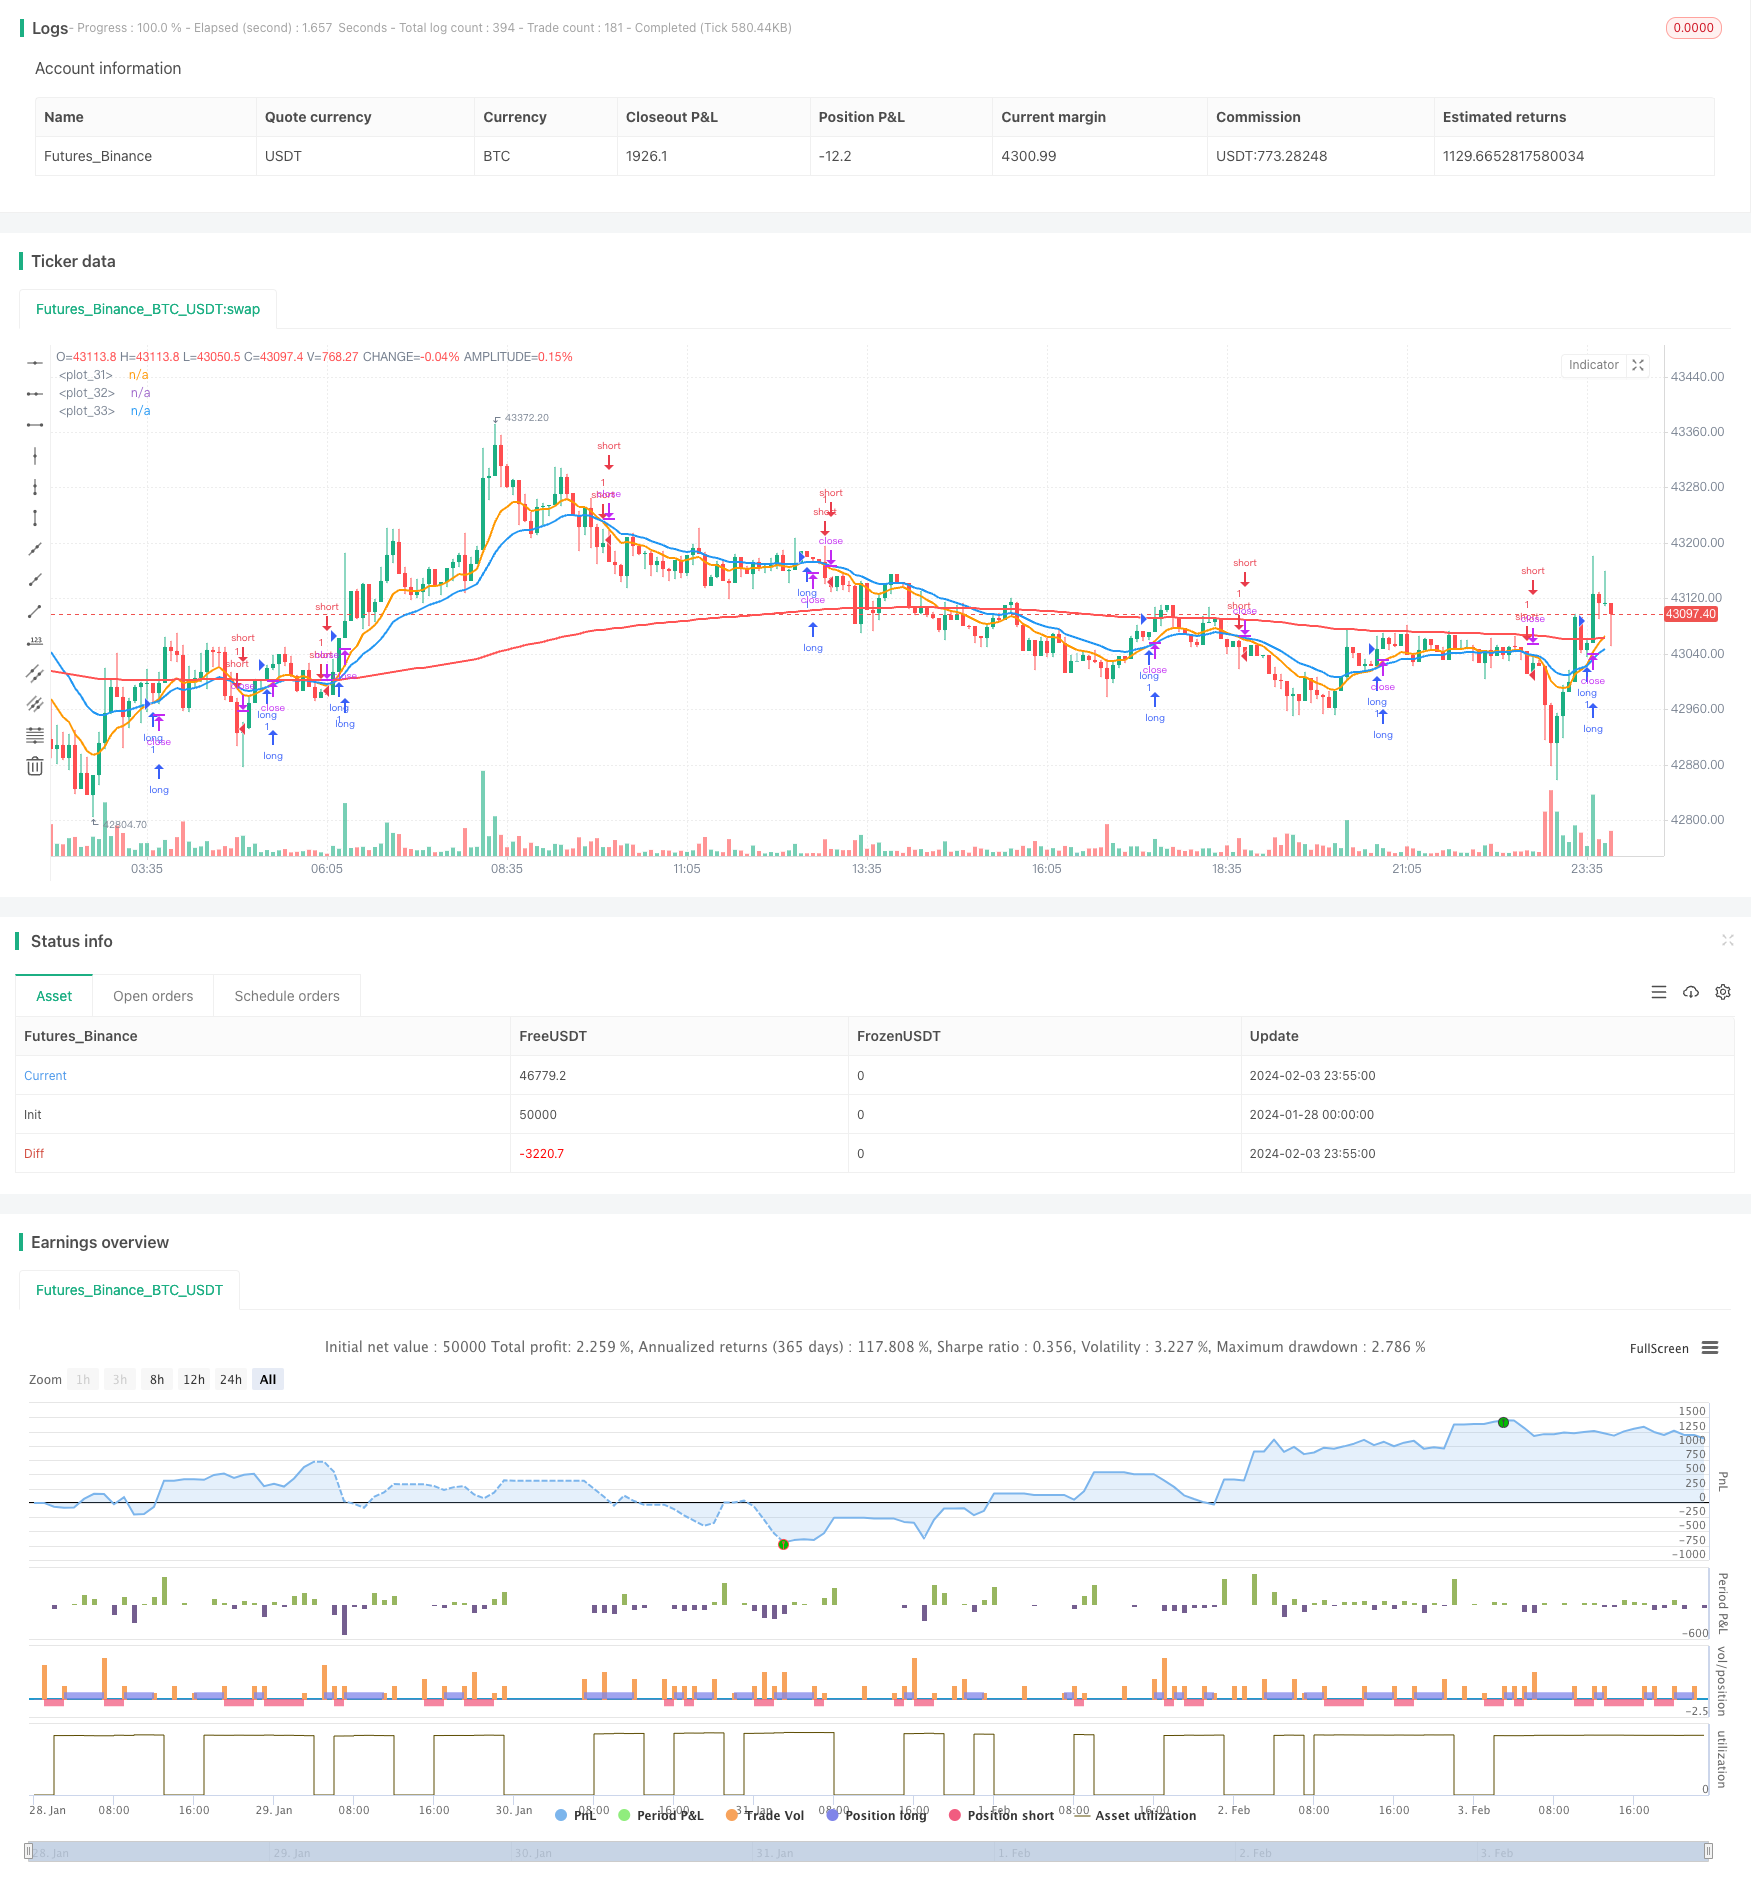
Overview
The Moving Average Crossover Trend Following strategy is a quantitative trading strategy that tracks market trends. The strategy generates trading signals by calculating fast and slow moving averages and catching turning points in market trends when crossovers occur.
Strategy Logic
The core principle of this strategy is to judge market trends using exponential moving averages (EMAs) with different parameters. The strategy defines a fast EMA and a slow EMA. When the fast EMA crosses above the slow EMA, it indicates a bullish trend reversal in the market. When the fast EMA crosses below the slow EMA, it indicates a bearish trend reversal.
On upward crosses, the strategy will open long positions. On downward crosses, the strategy will open short positions. The strategy will hold its position until take profit or stop loss is triggered, or a crossover in the opposite direction occurs again.
Advantage Analysis
The strategy has the following advantages:
- The strategy logic is simple and clear, easy to understand and implement, suitable for beginners;
- Using EMAs to smooth prices can effectively filter out market noise and identify trends;
- Parameters can be flexibly adjusted to adapt to markets with different cycles;
- The strategy can be extended to multi-timeframe versions to improve stability.
Risk Analysis
The strategy also has some risks:
- In ranging markets, multiple stop losses may occur, impacting profitability;
- It cannot effectively identify trend types (bullish or bearish), which may lead to severe losses;
- Improper EMA parameter settings may lead to over-trading or detection delays.
To mitigate risks, consider combining other indicators to determine trend types, or set wider stop loss ratios.
Optimization Directions
The strategy can also be optimized in the following aspects:
- Increase judgment of trend types to avoid opening positions against the trend;
- Add multi-timeframe judgments to improve signal quality;
- Dynamically adjust stop loss and take profit ratios to optimize exit points;
- Combine other indicators to filter out erroneous trades.
Conclusion
In summary, the Moving Average Crossover Trend Following Strategy is a simple and practical trend trading strategy. The core ideas of the strategy are clear and easy to implement, and there is also room for optimization. By adjusting parameters, adding multi-timeframe analysis, dynamic stops etc, the stability and profitability of the strategy can be continuously improved.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 10 | Fast EMA |
| v_input_int_2 | 20 | Slow EMA |
| v_input_string_1 | 0 | Trade Direction: Both | Short | Long |
| v_input_1 | timestamp(01 Jan 2023 00:00) | Start Date |
| v_input_2 | timestamp(31 Dec 2030 23:59) | End Date |
| v_input_3 | true | Take Profit Percent |
| v_input_4 | true | Stop Loss Percent |
Source Pine Script
/*backtest
start: 2024-01-28 00:00:00
end: 2024-02-04 00:00:00
period: 5m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy('Zhukov trade', overlay=true, calc_on_every_tick=true, currency=currency.USD)

// INPUT:

// Options to enter fast and slow Exponential Moving Average (EMA) values
emaFast = input.int(title='Fast EMA', defval=10, minval=1, maxval=9999)
emaSlow = input.int(title='Slow EMA', defval=20, minval=1, maxval=9999)

// Option to select trade directions
tradeDirection = input.string(title='Trade Direction', options=['Long', 'Short', 'Both'], defval='Both')

// Options that configure the backtest date range
startDate = input(title='Start Date', defval=timestamp('01 Jan 2023 00:00'))
endDate = input(title='End Date', defval=timestamp('31 Dec 2030 23:59'))

// Set take profit and stop loss percentages
take_profit_percent = input(1.0, title ="Take Profit Percent") / 100.0
stop_loss_percent = input(1.0, title ="Stop Loss Percent") / 100.0

// CALCULATIONS:

// Use the built-in function to calculate two EMA lines
fastEMA = ta.ema(close, emaFast)
slowEMA = ta.ema(close, emaSlow)
emapos = ta.ema(close, 200)

// PLOT:

// Draw the EMA lines on the chart
plot(series=fastEMA, color=color.new(color.orange, 0), linewidth=2)
plot(series=slowEMA, color=color.new(color.blue, 0), linewidth=2)
plot(series=emapos, color=color.new(color.red, 0), linewidth=2)

// CONDITIONS:

// Check if the close time of the current bar falls inside the date range
inDateRange = true

// Translate input into trading conditions
longOK = tradeDirection == 'Long' or tradeDirection == 'Both'
shortOK = tradeDirection == 'Short' or tradeDirection == 'Both'

// Decide if we should go long or short using the built-in functions
longCondition = ta.crossover(fastEMA, slowEMA) and inDateRange
shortCondition = ta.crossunder(fastEMA, slowEMA) and inDateRange

// ORDERS:

// Submit entry (or reverse) orders
if longCondition and longOK
    strategy.entry(id='long', direction=strategy.long)

if shortCondition and shortOK
    strategy.entry(id='short', direction=strategy.short)

// Exit orders
if strategy.position_size > 0 and longOK
    strategy.exit(id='exit long', from_entry='long', limit=strategy.position_avg_price * (1 + take_profit_percent), stop=strategy.position_avg_price * (1 - stop_loss_percent))

if strategy.position_size < 0 and shortOK
    strategy.exit(id='exit short', from_entry='short', limit=strategy.position_avg_price * (1 - take_profit_percent), stop=strategy.position_avg_price * (1 + stop_loss_percent))
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Moving-Average-Crossover-Trend-Following-Strategy-441080.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- ATR and T3 Moving Average StrategyPine Script · Trend following · 5m