Strategy vault / Machine learning
Moving Average Displaced Envelope Strategy
This strategy generates trading signals based on the Moving Average Displaced Envelope indicator. The envelope bands are calculated by percentage factors of the moving average. If the previous high breaks above the…
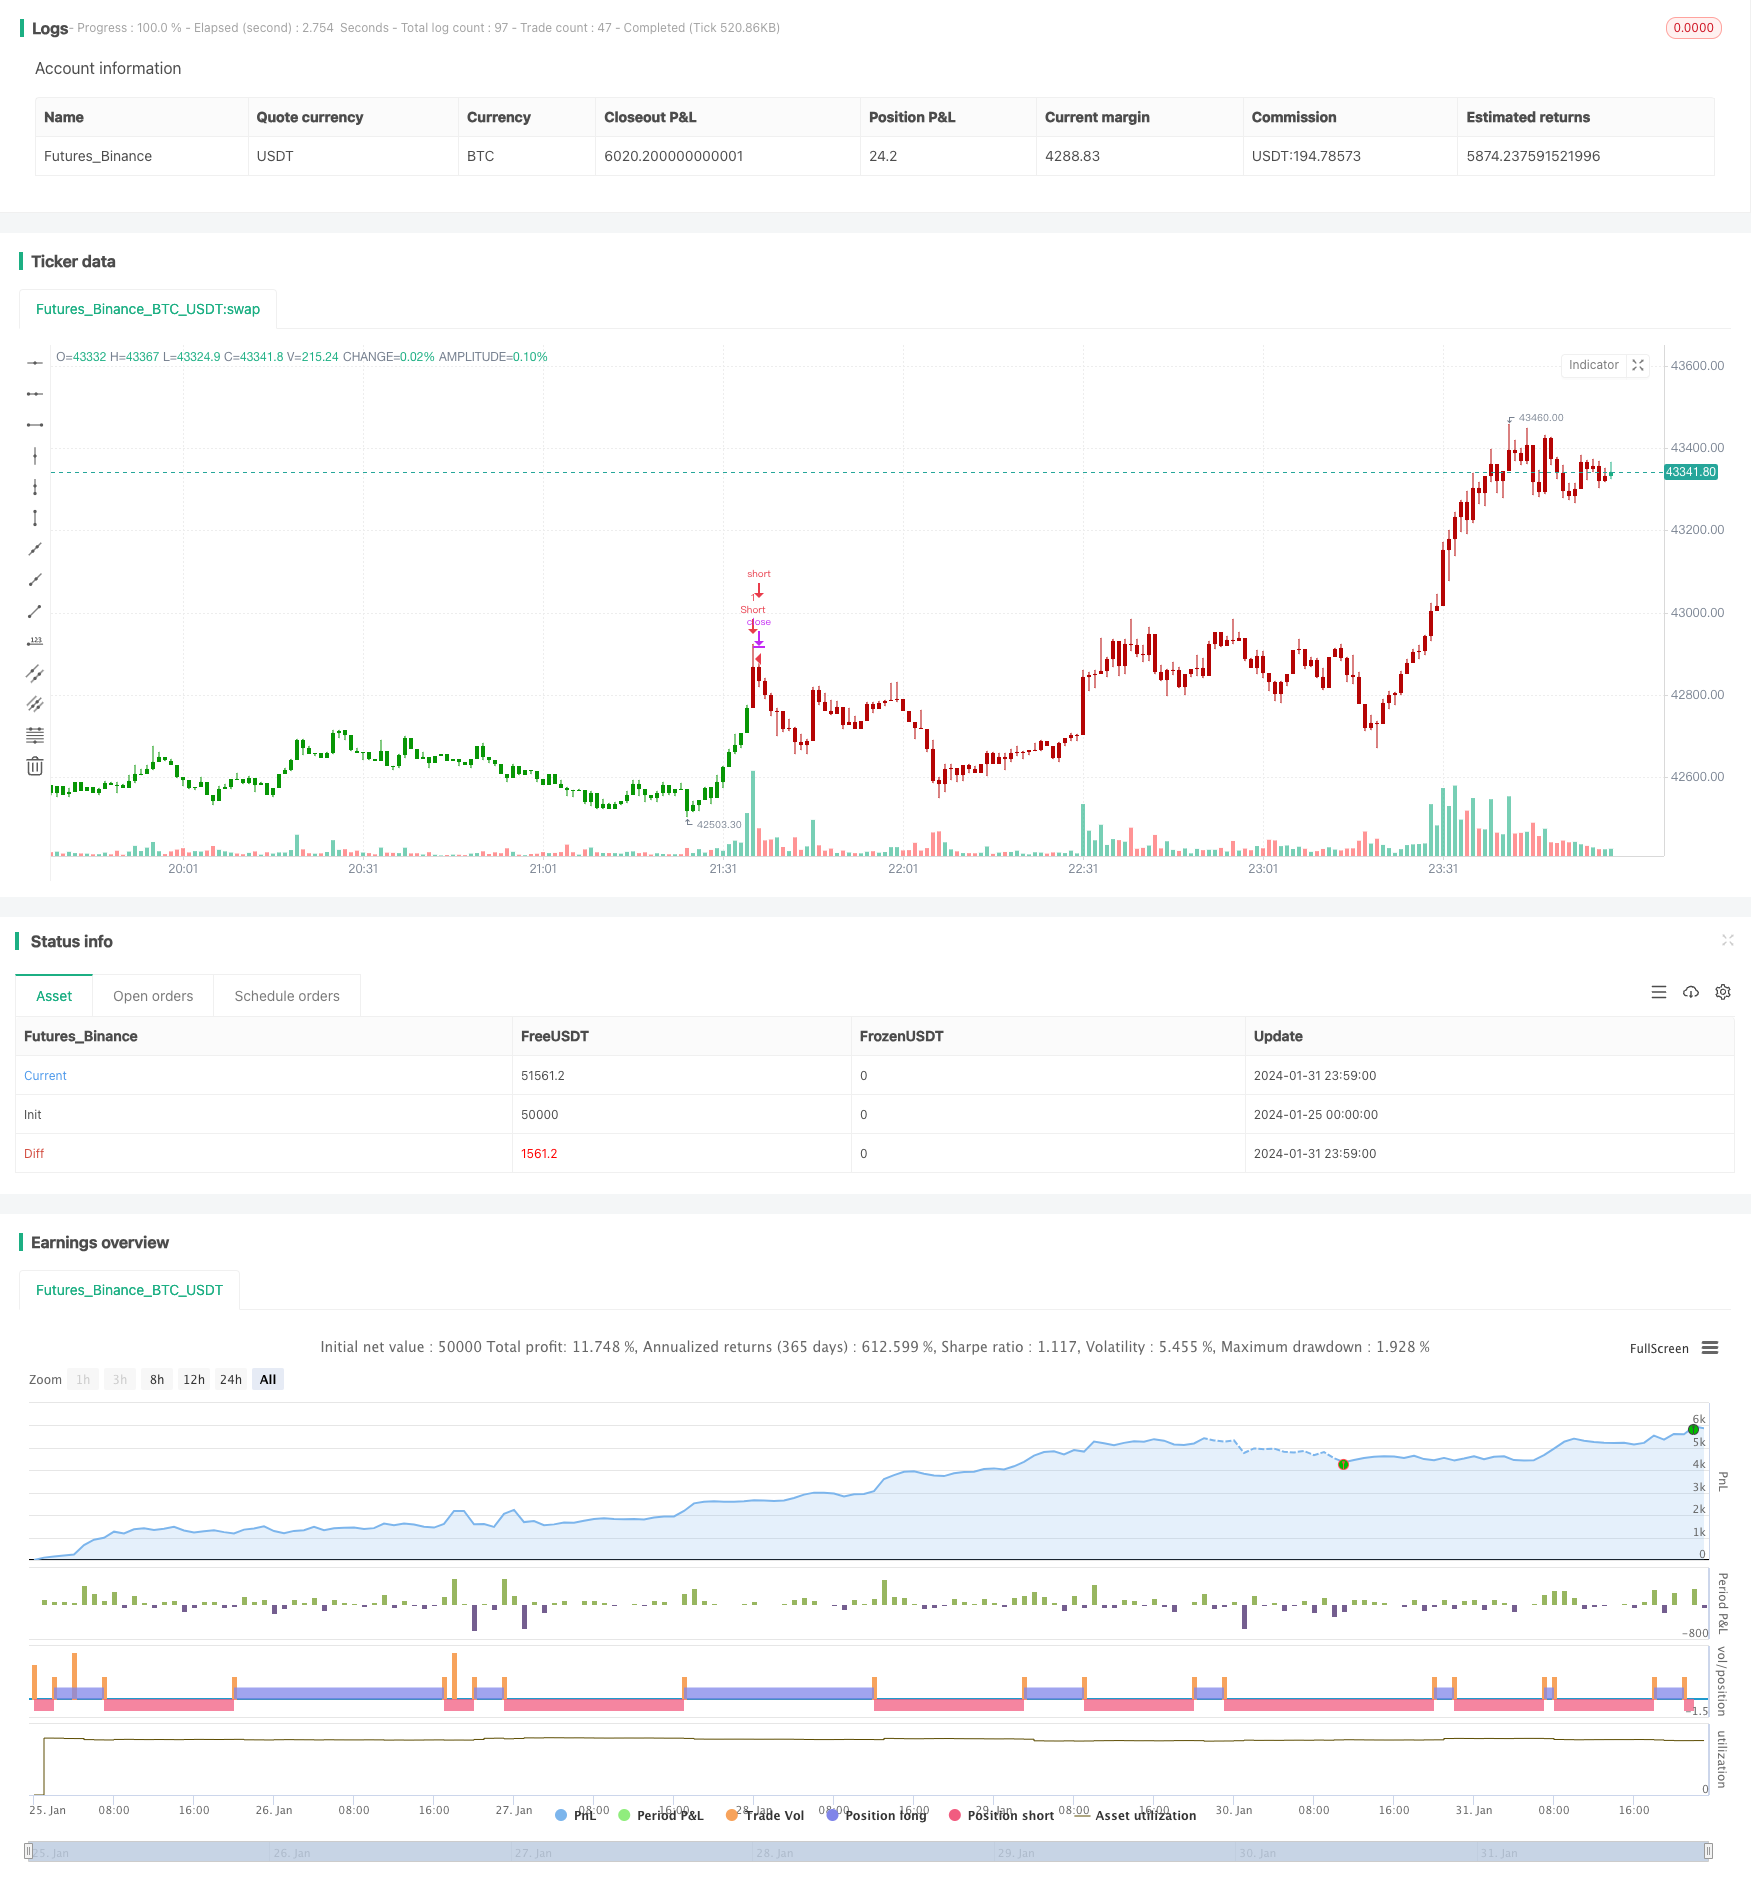
This strategy generates trading signals based on the Moving Average Displaced Envelope indicator. The envelope bands are calculated by percentage factors of the moving average. If the previous high breaks above the upper band, a sell signal is generated. If the previous low breaks below the lower band, a buy signal is generated.
Strategy Logic
This strategy uses the displaced exponential moving average (EMA) as the core indicator, and forms the upper and lower bands after a certain period by percentage factors. This constructs the complete moving average displaced envelope system. Specifically, the envelope system consists of:
- EMA(Price, Period) - The core moving average line
- top = sEMA[disp] * ((100 + perAb)/100) - Upper band
- bott = sEMA[disp] * ((100 - perBl)/100) - Lower band
Here Percent above and Percent below control the percentage range of the bands relative to the core moving average line. The Displacement parameter controls the period displacement between the bands and the core moving average line.
In this way, we can form appropriate trading ranges by adjusting the above parameters. Trading signals are generated when prices break through the bands. Specifically:
- If close is lower than the lower band bott, a buy signal is generated
- If close is higher than the upper band top, a sell signal is generated
Note that this strategy also provides a reverse parameter. If set to true, the signal direction is opposite to the above.
Advantage Analysis
The main advantages of this strategy are:
- Using exponential moving average as the base indicator can reduce curve lagging and improve sensitivity to price changes
- More adjustable parameters allow better optimization of trading performance through parameter tuning
- The reverse mode adapts to different market types
- Simple and clear rules, easy to understand and implement
Risks and Precautions
There are also some risks with this strategy:
- False signals can occur frequently in range-bound markets
- Improper parameter settings may cause over-trading or signal missing
- Market noise cannot be filtered effectively, generating some worthless signals
To prevent these risks, some optimizations can be made:
- Filter signals with other indicators like volume, volatility etc.
- Add parameter optimization process to find optimum parameter sets
- Adjust stop loss properly to limit losses
Optimization Directions
There is still large room for optimizing this strategy:
- Add machine learning models to realize automatic parameter optimization and adjustment
- Incorporate features like stop loss, trailing stop to control risks
- Filter signals with sentiment indicators to improve quality
- Increase model combinations with other technical indicators to identify trends and improve overall accuracy
- Inherit this strategy template to develop other types of moving average systems and expand applicability
With these optimizations, the stability, adaptability and performance of the strategy can be further improved.
Summary
The moving average displaced envelope strategy utilizes simple exponential moving average systems and parameterized bands to form clear trading rules that are easy to interpret and implement. It is a typical trend following system. Through parameter tuning and optimizations, good results can be achieved. But the impacts of market environments should also be fully considered and potential risks should be prevented. This strategy serves as a basic template and has much room for expansions and optimizations.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 9 | Period |
| v_input_3 | 0.5 | Percent above |
| v_input_4 | 0.5 | Percent below |
| v_input_5 | 13 | Displacement |
| v_input_6 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2024-01-25 00:00:00
end: 2024-02-01 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 14/08/2020
// Moving Average Displaced Envelope. These envelopes are calculated
// by multiplying percentage factors with their displaced expotential
// moving average (EMA) core.
// How To Trade Using:
// Adjust the envelopes percentage factors to control the quantity and
// quality of the signals. If a previous high goes above the envelope
// a sell signal is generated. Conversely, if the previous low goes below
// the envelope a buy signal is given.
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
strategy(title="Moving Average Displaced Envelope Backtest", shorttitle="MA DE", overlay = true)
Price = input(title="Source", type=input.source, defval=close)
Period =input(defval=9, minval=1)
perAb = input(title = "Percent above", defval=.5, minval=0.01, step = 0.1)
perBl = input(title = "Percent below", defval=.5, minval=0.01, step = 0.1)
disp = input(title = "Displacement", defval=13, minval=1)
reverse = input(false, title="Trade reverse")
pos = 0
sEMA = ema(Price, Period)
top = sEMA[disp] * ((100 + perAb)/100)
bott = sEMA[disp]* ((100 - perBl)/100)
pos := iff(close < bott , 1,
	     iff(close > top, -1, pos[1]))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1 , 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? #b50404: possig == 1 ? #079605 : #0536b3 )
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Moving-Average-Displaced-Envelope-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- Dual Moving Average Matching Strategy Based on Bollinger BandsPine Script · Machine learning · 1h
- Dynamic Weighted Moving Average Trading StrategyPine Script · Machine learning · 1d
- EMA and RSI Quantitative Trading StrategyPine Script · Machine learning · 1h
- Fibonacci Retracement Dynamic Stop Loss StrategyPine Script · Machine learning · 1h
- MACD Robot Trading StrategyPine Script · Machine learning · 1d