Strategy vault / Mean reversion
Moving Average Indicator Strategy
The Moving Average Indicator strategy is a quantitative trading strategy that judges market trends based on moving averages and conducts long or short position operations. By calculating the average closing price…
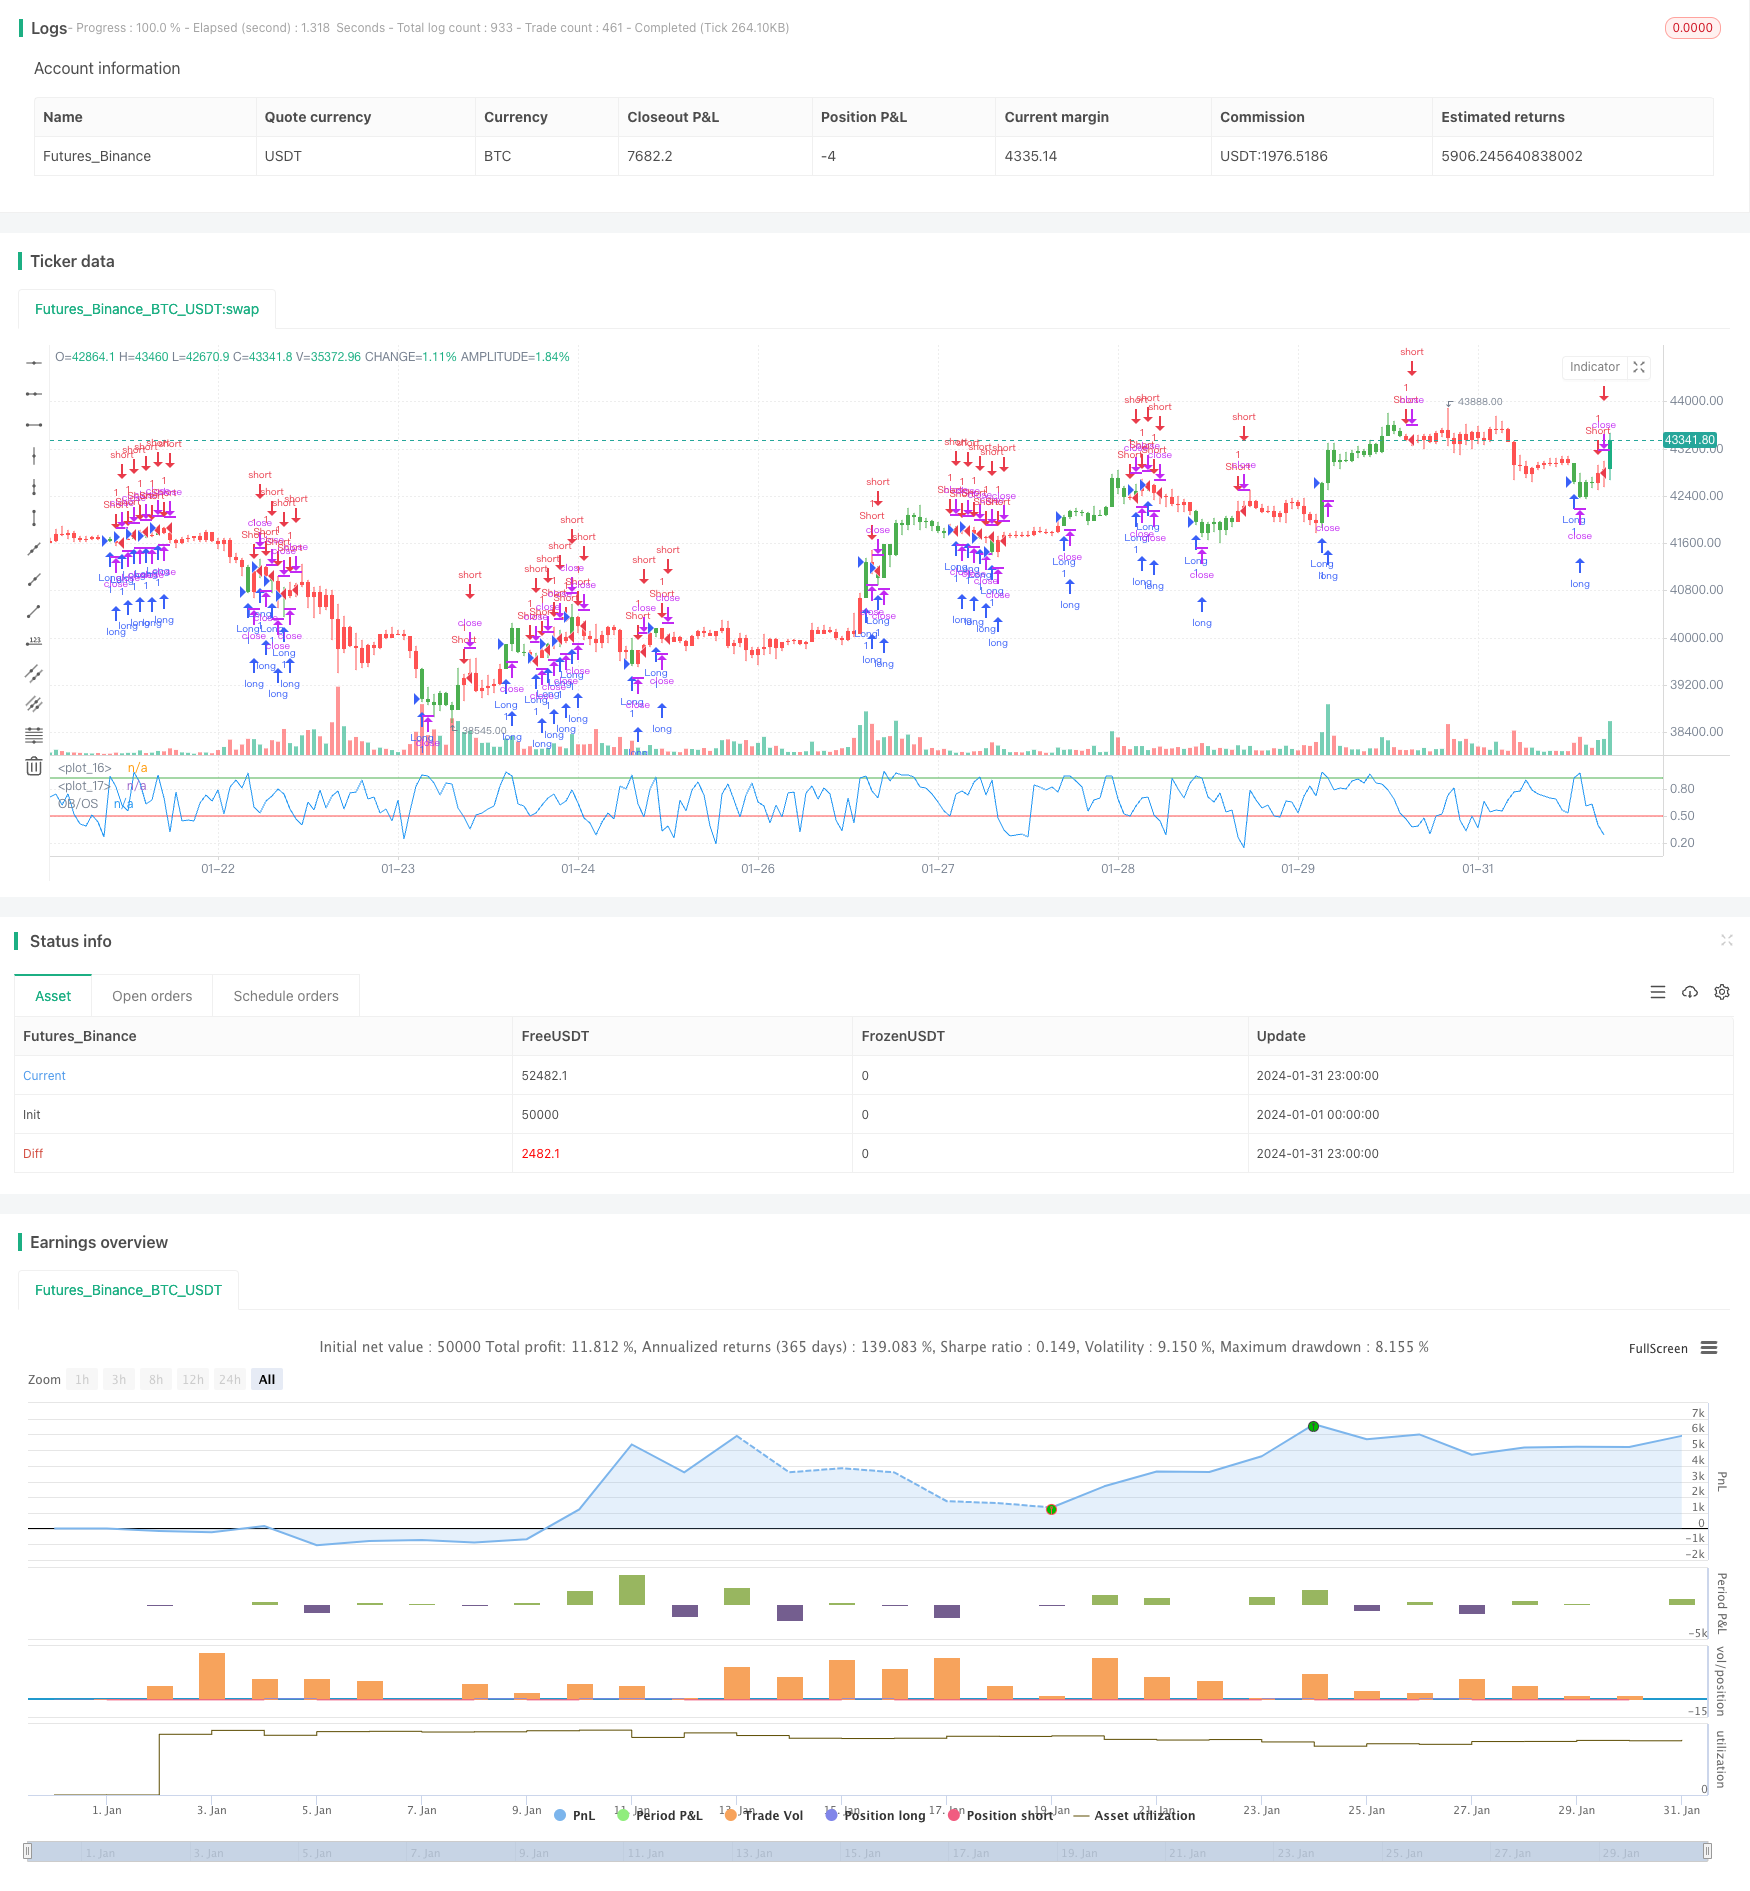
Overview
The Moving Average Indicator strategy is a quantitative trading strategy that judges market trends based on moving averages and conducts long or short position operations. By calculating the average closing price over a period of time, this strategy determines whether the market is overbought or oversold in order to capture price reversal opportunities.
Strategy Principle
The core indicator of this strategy is the Stochastic Oscillator. Its calculation method is:
Low = the lowest low of the most recent N days
High = the highest high of the most recent N days
K value = (Current close – Low)/(High – Low)*100
Where N is the length Length. This indicator roughly reflects the position of the current closing price relative to the price range over the most recent N days.
When the K value is greater than the overbought line (BuyBand), it indicates that the stock may be overbought and a callback will occur. When the K value is less than the oversold line (SellBand), it indicates that the stock may be oversold and a rebound will occur.
According to this judgment rule, the strategy will sell to open a position in the overbought zone and buy to open a position in the oversold zone. The closing condition is that the indicator line re-enters the intermediate zone ((SellBand, BuyBand)).
Advantage Analysis
This strategy has the following advantages:
- Using moving average indicators to determine market trends, good backtesting results, easy to form trading signals
- Flexible to adapt to different cycles and varieties by adjusting parameters
- The strategy idea is simple and clear, easy to understand and optimize
Risk Analysis
The strategy also poses some risks:
- Moving averages are prone to false touches, possibly being "whipsawed"
- Improper parameter settings can lead to frequent trading or unclear signals
- Only one indicator is considered, limited optimization space
These risks can be reduced by appropriately optimizing indicator parameters or adding filter conditions.
Optimization Directions
The main aspects that this strategy can be optimized include:
- Add volume or ATR and other indicators to ensure more reliable trading signals
- Add Stoch indicators of multiple cycles, generate signals through composite operations
- Increase additional judgment indicators such as MACD and KDJ to achieve multi-indicator aggregation
- Traverse and optimize trading varieties, cycles, parameters to find the optimal configuration
Conclusion
The overall idea of the Moving Average Indicator strategy is simple and widely used with relatively stable backtesting results, making it suitable as a beginner's quantitative trading strategy. However, this strategy has limited optimization space as it considers limited factors and is only suitable for short-term operations. Future upgrades can be made through multi-indicator aggregation, machine learning, etc.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | Length |
| v_input_2 | 0.92 | BuyBand |
| v_input_3 | 0.5 | SellBand |
| v_input_4 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 25/09/2017
// Simple Overbought/Oversold indicator
//
// You can change long to short in the Input Settings
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
strategy(title="Overbought/Oversold", shorttitle="OB/OS")
Length = input(10, minval=1)
BuyBand = input(0.92, step = 0.01)
SellBand = input(0.5, step = 0.01)
reverse = input(false, title="Trade reverse")
hline(BuyBand, color=green, linestyle=line)
hline(SellBand, color=red, linestyle=line)
xOBOS = stoch(close, high, low, Length)
nRes = iff(close > close[Length], xOBOS / 100, (100 - xOBOS) / 100)
pos = iff(nRes < SellBand, -1,
	   iff(nRes > BuyBand, 1, nz(pos[1], 0)))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
barcolor(possig == -1 ? red: possig == 1 ? green : blue )
plot(nRes, color=blue, title="OB/OS")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Moving-Average-Indicator-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- Momentum Reversal Trading Strategy 428631Pine Script · Mean reversion · 2h
- Multi Indicator Scoring Trading StrategyPine Script · Mean reversion · 1d
- Multi Indicator Weighted Smart Trading StrategyPine Script · Mean reversion · 2d
- Stochastic Oscillator and Moving Average StrategyPine Script · Mean reversion · 1m
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h