Strategy vault / Mean reversion
Moving Average Range Swallowing Strategy
The Moving Average Range Swallowing Strategy is a trend following strategy based on moving averages. It determines price trends by calculating crossovers between two moving averages and uses range management to track…
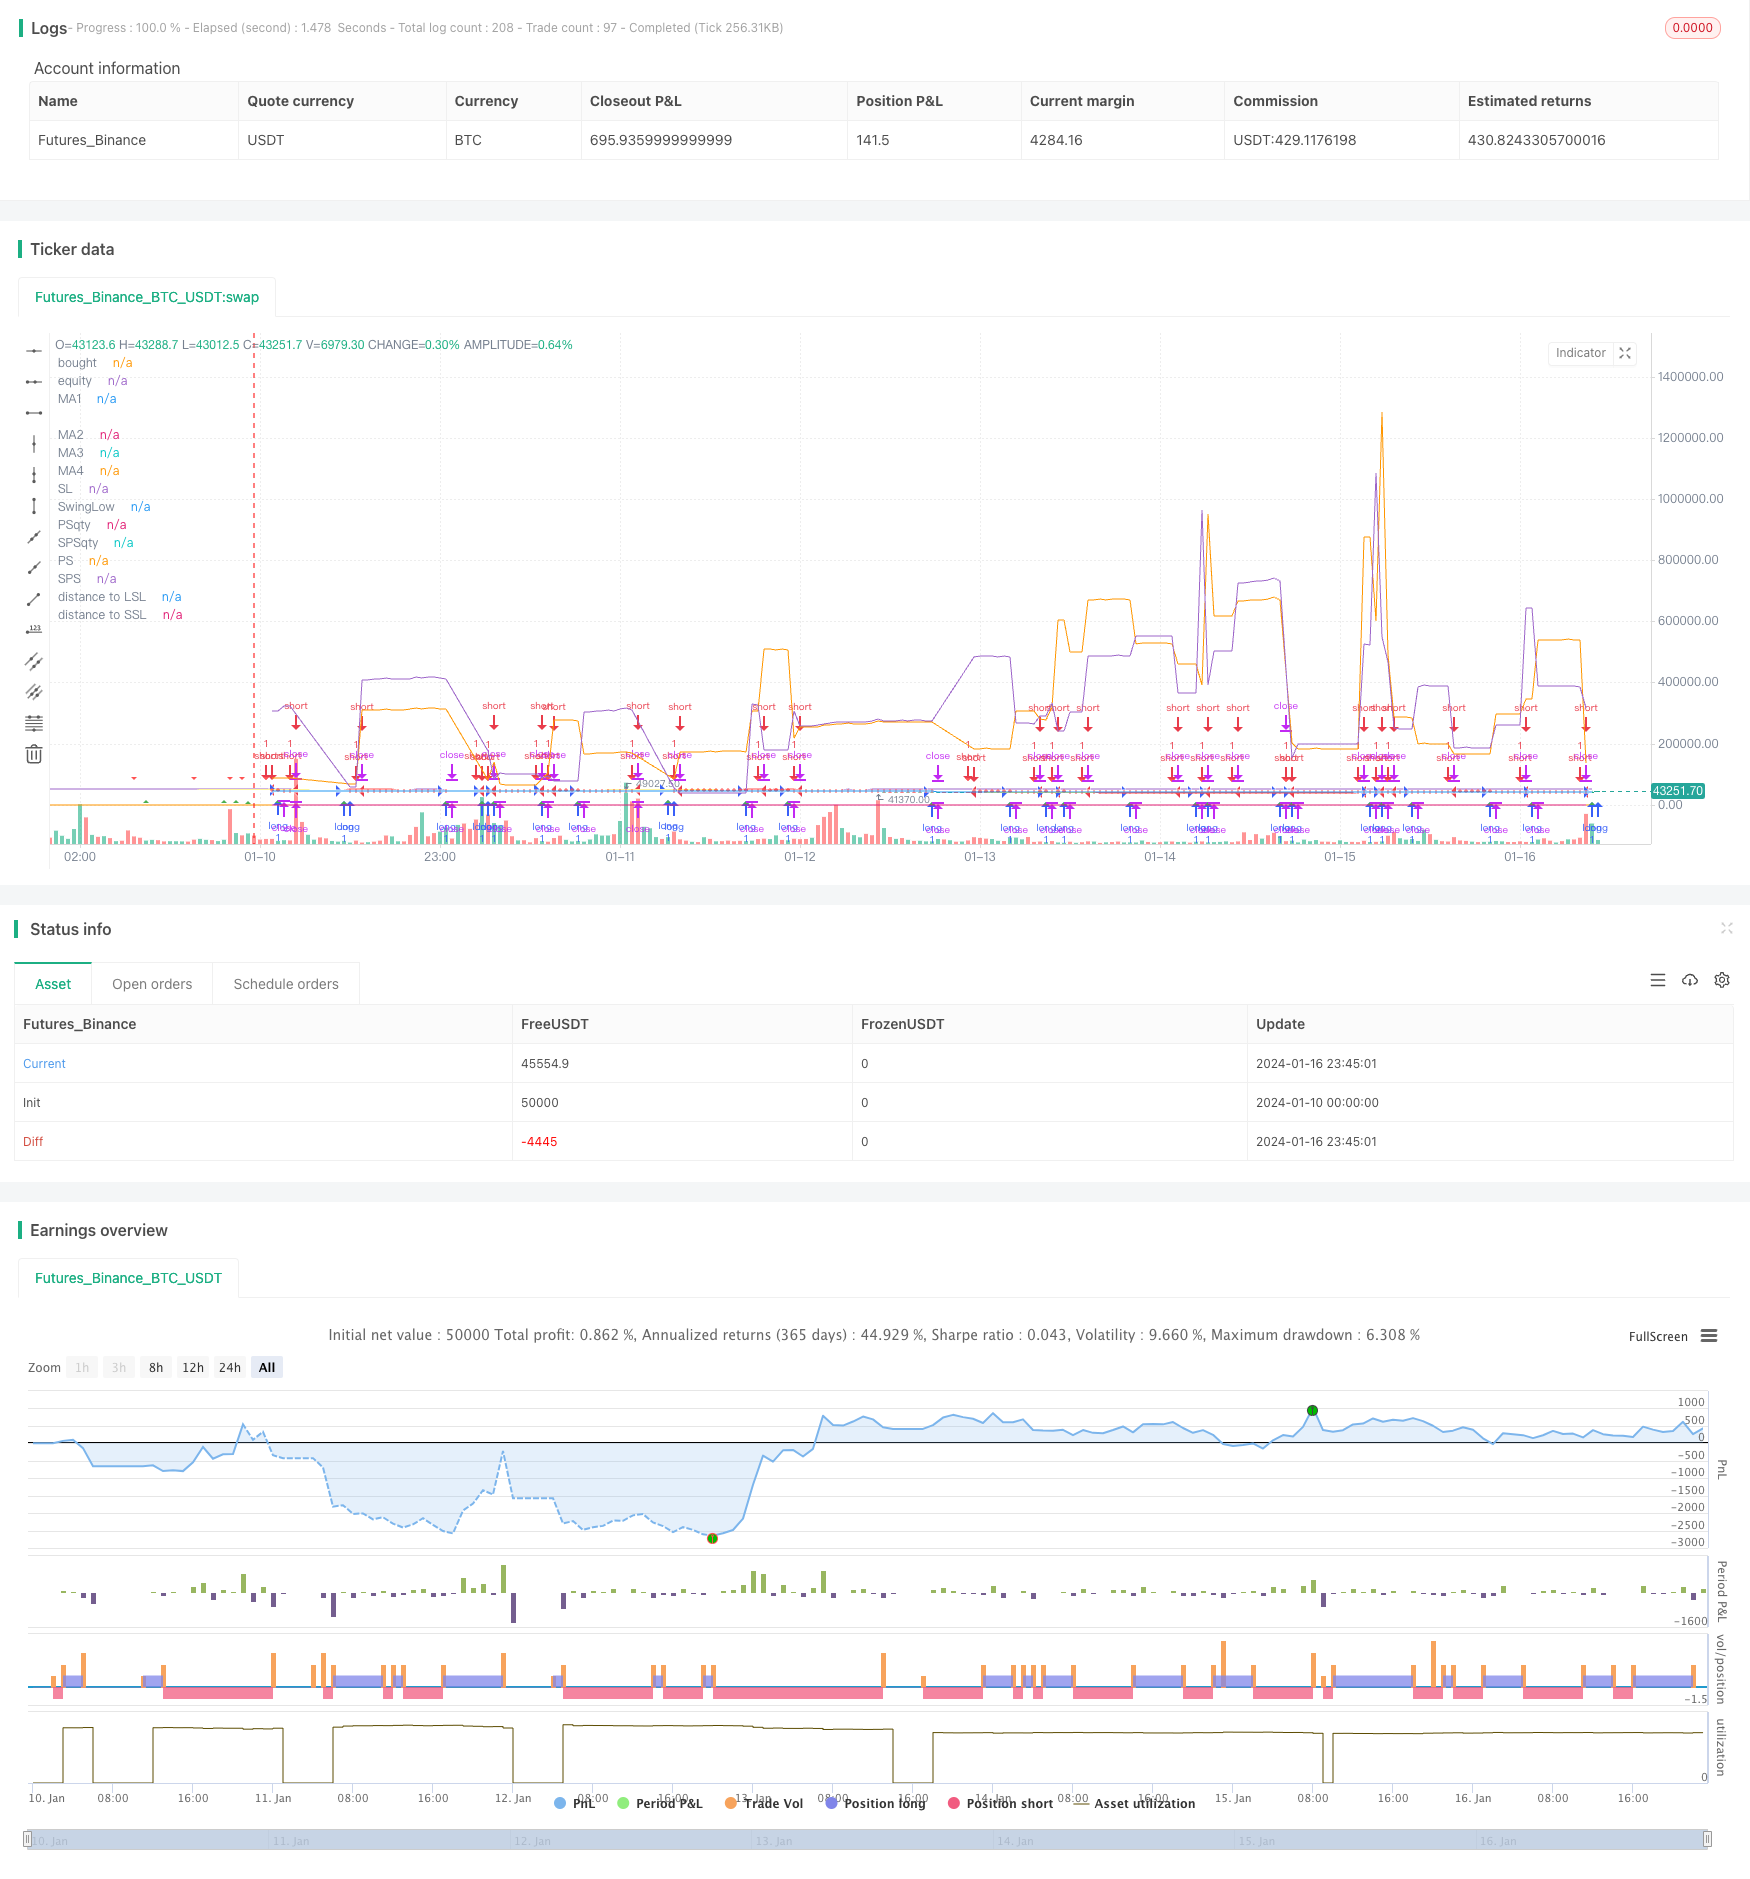
Overview
The Moving Average Range Swallowing Strategy is a trend following strategy based on moving averages. It determines price trends by calculating crossovers between two moving averages and uses range management to track trends for profit.
Strategy Logic
The strategy uses two moving averages: a fast line and a slow line. The fast line has a smaller parameter and is more sensitive to price changes. The slow line has a larger parameter and determines trends more reliably. It goes long when the fast line crosses above the slow line, and goes short when the fast line crosses below the slow line.
It also introduces multiple auxiliary moving averages to judge the main trend direction to avoid mismatches. In addition, it uses the Highest and Lowest functions together with ATR to calculate dynamic stop loss to lock in profits.
For each trade, the strategy can choose to place orders with a fixed quantity or dynamically calculate the position size based on the maximum loss percentage set in parameters. The latter can keep the risk of each trade within a certain range.
Advantage Analysis
- The dual moving average system can effectively track price trends
- Auxiliary moving averages and directional filters reduce noise trades
- Dynamic stop loss and position sizing limit max loss per trade
- Position sizing system enables exponential profit growth while capping drawdowns
Risk Analysis
- Double MA strategies tend to experience consolidation pinch
- Auxiliary MAs and filters may miss some trading opportunities
- Stop loss may be penetrated during extreme volatility leading to large losses
- Excessive position sizes during extreme moves can lead to huge losses
These risks can be reduced by optimizing MA parameters, adjusting weights of auxiliary MAs, modifying stop loss ranges etc. In addition, strict position sizing rules minimize damage from single trade losses.
Optimization Directions
The strategy can be optimized in the following aspects:
- Test more combinations of moving averages to find optimum parameters
- Add trend strength indicators to avoid losses from trend reversals
- Research adaptive stop loss algorithms to make stops more intelligent
- Optimize position sizing schemes to balance profitability and risk
Summary
Overall, the Moving Average Range Swallowing Strategy is a very practical quantitative trading strategy. It combines both trend following and risk control capabilities, suitable for long term holdings. By optimizing parameters and functionality, the strategy can be made more robust and intelligent for sustained profitability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | false | Strategy Direction |
| v_input_2 | false | Position Management |
| v_input_3 | 5 | Risk Per Trade % (for PSMGMT) |
| v_input_4 | true | Use Swing Lo/Hi Stop Loss & Take Profit |
| v_input_5 | 10 | Swing Lo/Hi Lookback |
| v_input_6 | false | SL Expander |
| v_input_7 | false | Use MA4 as Bull / Bear filter |
| v_input_8 | false | ----------------MA Selector----------------- |
| v_input_9 | 9 | MA1 Period |
| v_input_10 | 0 | MA1 Type: EMA | SMA | RMA | WMA | HMA | ALMA |
| v_input_11 | 21 | MA2 Period |
| v_input_12 | 0 | MA2 Type: EMA | SMA | RMA | WMA | HMA | ALMA |
| v_input_13 | 50 | MA3 Period |
| v_input_14 | 0 | MA3 Type: SMA | RMA | EMA | WMA | HMA | ALMA |
| v_input_15 | 100 | MA4 Period |
| v_input_16 | 0 | MA4 Type: SMA | RMA | EMA | WMA | HMA | ALMA |
| v_input_17 | 0 | x: close | MA2 | MA3 | MA4 | MA1 |
| v_input_18 | 0 | y: MA1 | MA2 | MA3 | MA4 | close |
Source Pine Script
/*backtest
start: 2024-01-10 00:00:00
end: 2024-01-17 00:00:00
period: 45m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4

// This is a simple crossover Moving Average strategy, good for long term crypto trades.
// It buys when the MA "X" crosses up the MA "Y", viceversa for shorts.
// Both MAs are selectable from the Inputs section in the front panel.
// There is also a Position Management option thats
// sizes positions to have the same USD risk (using leverage) on each trade,
// based on the percentage distance to the stop loss level.
// If you turn this option on you will see how the profit
// grows exponentially while the drawdown percentage almost remains the same.

strategy("4 MA Strat", overlay=true, pyramiding=1,
     default_qty_type=strategy.percent_of_equity,
     default_qty_value=100,
     commission_value = 0.04,
     initial_capital=100,
     process_orders_on_close=false)

direction = input(0, title = "Strategy Direction", type=input.integer, minval=-1, maxval=1)
strategy.risk.allow_entry_in(direction == 0 ? strategy.direction.all : (direction < 0 ? strategy.direction.short : strategy.direction.long))

//Inputs
PSMGMT=input(defval=false, title="Position Management")
risk_per_trade=input(defval=5, title="Risk Per Trade % (for PSMGMT)", step=0.5)*.01

//SL & TP Inputs
i_SL=input(true, title="Use Swing Lo/Hi Stop Loss & Take Profit")
i_SwingLookback=input(10, title="Swing Lo/Hi Lookback")
i_SLExpander=input(defval=0, step=1, title="SL Expander")

i_MAFilter=input(false, title="Use MA4 as Bull / Bear filter")

//MA Type Selector
MAtype = input(false, title="----------------MA Selector-----------------")
MA1Period = input(9, title="MA1 Period")
MA1Type = input(title="MA1 Type", defval="EMA", options=["RMA", "SMA", "EMA", "WMA", "HMA", "ALMA"])
MA2Period = input(21, title="MA2 Period")
MA2Type = input(title="MA2 Type", defval="EMA", options=["RMA", "SMA", "EMA", "WMA", "HMA", "ALMA"])
MA3Period = input(50, title="MA3 Period")
MA3Type = input(title="MA3 Type", defval="SMA", options=["RMA", "SMA", "EMA", "WMA", "HMA", "ALMA"])
MA4Period = input(100, title="MA4 Period")
MA4Type = input(title="MA4 Type", defval="SMA", options=["RMA", "SMA", "EMA", "WMA", "HMA", "ALMA"])

//MA Selector
MA1 = if MA1Type == "SMA"
    sma(close, MA1Period)
else
    if MA1Type == "EMA"
        ema(close, MA1Period)
    else
        if MA1Type == "WMA"
            wma(close, MA1Period)
        else
            if MA1Type == "RMA"
                rma(close, MA1Period)
            else
                if MA1Type == "HMA"
                    hma(close, MA1Period)
                else
                    if MA1Type == "ALMA"
                        alma(close, MA1Period, 0.85, 6)

MA2 = if MA2Type == "SMA"
    sma(close, MA2Period)
else
    if MA2Type == "EMA"
        ema(close, MA2Period)
    else
        if MA2Type == "WMA"
            wma(close, MA2Period)
        else
            if MA2Type == "RMA"
                rma(close, MA2Period)
            else
                if MA2Type == "HMA"
                    hma(close, MA2Period)
                else
                    if MA2Type == "ALMA"
                        alma(close, MA2Period, 0.85, 6)

MA3 = if MA3Type == "SMA"
    sma(close, MA3Period)
else
    if MA3Type == "EMA"
        ema(close, MA3Period)
    else
        if MA3Type == "WMA"
            wma(close, MA3Period)
        else
            if MA3Type == "RMA"
                rma(close, MA3Period)
            else
                if MA3Type == "HMA"
                    hma(close, MA3Period)
                else
                    if MA3Type == "ALMA"
                        alma(close, MA3Period, 0.85, 6)

MA4 = if MA4Type == "SMA"
    sma(close, MA4Period)
else
    if MA4Type == "EMA"
        ema(close, MA4Period)
    else
        if MA4Type == "WMA"
            wma(close, MA4Period)
        else
            if MA4Type == "RMA"
                rma(close, MA4Period)
            else
                if MA4Type == "HMA"
                    hma(close, MA4Period)
                else
                    if MA4Type == "ALMA"
                        alma(close, MA4Period, 0.85, 6)

// X Y Logic
x=input(title="x", defval="close", options=["MA1", "MA2", "MA3", "MA4", "close"])
y=input(title="y", defval="MA1", options=["MA1", "MA2", "MA3", "MA4", "close"])

X = if x == "MA1"
    MA1
else
    if x == "MA2"
        MA2
    else
        if x == "MA3"
            MA3
        else
            if x == "MA4"
                MA4
            else
                if x == "close"
                    close

Y = if y == "MA1"
    MA1
else
    if y == "MA2"
        MA2
    else
        if y == "MA3"
            MA3
        else
            if y == "MA4"
                MA4
            else
                if y == "close"
                    close

//SL & TP Calculations
SwingLow=lowest(i_SwingLookback)
SwingHigh=highest(i_SwingLookback)
bought=strategy.position_size != strategy.position_size[1]
LSL=valuewhen(bought, SwingLow, 0)-((valuewhen(bought, atr(14), 0)/5)*i_SLExpander)
SSL=valuewhen(bought, SwingHigh, 0)+((valuewhen(bought, atr(14), 0)/5)*i_SLExpander)
islong=strategy.position_size > 0
isshort=strategy.position_size < 0
SL= islong ? LSL : isshort ? SSL : na

//Position Management Calculations
capital=strategy.equity
distance_to_long_stop_loss=1-(LSL/strategy.position_avg_price)
distance_to_short_stop_loss=(SSL/strategy.position_avg_price)-1
PS=(capital*risk_per_trade)/distance_to_long_stop_loss
SPS=(capital*risk_per_trade)/distance_to_short_stop_loss
PSqty=PS/close
SPSqty=SPS/close

//Strategy Calculations
MAFilter=close > MA4
BUY = crossover(X , Y)
SELL = crossunder(X , Y)
BUY2 = crossover(X , Y) and MAFilter
SELL2 = crossunder(X , Y) and not MAFilter

//Entries
strategy.entry("long", true, qty=PSMGMT ? PSqty : na, when=not i_MAFilter ? BUY : BUY2)
strategy.entry("short", false, qty=PSMGMT ? SPSqty : na, when=not i_MAFilter ? SELL : SELL2)

//Exits
if i_SL //and SL != na
    strategy.exit("longexit", "long", stop=LSL)
    strategy.exit("shortexit", "short", stop=SSL)
if i_MAFilter
    strategy.close("long", when=SELL)
    strategy.close("short", when=BUY)


//Plots
plot(i_SL ? SL : na, color=color.red, style=plot.style_cross, title="SL")
plot(MA1, color=color.green, linewidth=1, title="MA1")
plot(MA2, color=color.yellow, linewidth=2, title="MA2")
plot(MA3, color=color.red, linewidth=3, title="MA3")
plot(MA4, color=color.white, linewidth=3, title="MA4")
plotshape(BUY ? 1 : na, style=shape.triangleup, location=location.belowbar, color=color.green, title="Bullish Setup")
plotshape(SELL ? 1 : na, style=shape.triangledown, location=location.abovebar, color=color.red, title="Bearish Setup")


//Debugging Plots
plot(LSL, transp=100, title="SwingLow")
plot(bought ? 1:0, transp=100, title="bought")
plot(PSqty, title="PSqty", transp=100)
plot(SPSqty, title="SPSqty", transp=100)
plot(PS, title="PS", transp=100)
plot(SPS, title="SPS", transp=100)
plot(distance_to_long_stop_loss, title="distance to LSL", transp=100)
plot(distance_to_short_stop_loss, title="distance to SSL", transp=100)
plot(capital, title="equity", transp=100)Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Moving-Average-Range-Swallowing-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trend Following and Cloud Reversal Composite Trading StrategyPine Script · Mean reversion · 1d
- Bidirectional Moving Average Reversion Trading StrategyPine Script · Mean reversion · 1h
- Comprehensive Strategy of Multiple Candlestick PatternsPine Script · Mean reversion · 1h
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d