Strategy vault / Multi-timeframe
MTF RSI STOCH Strategy
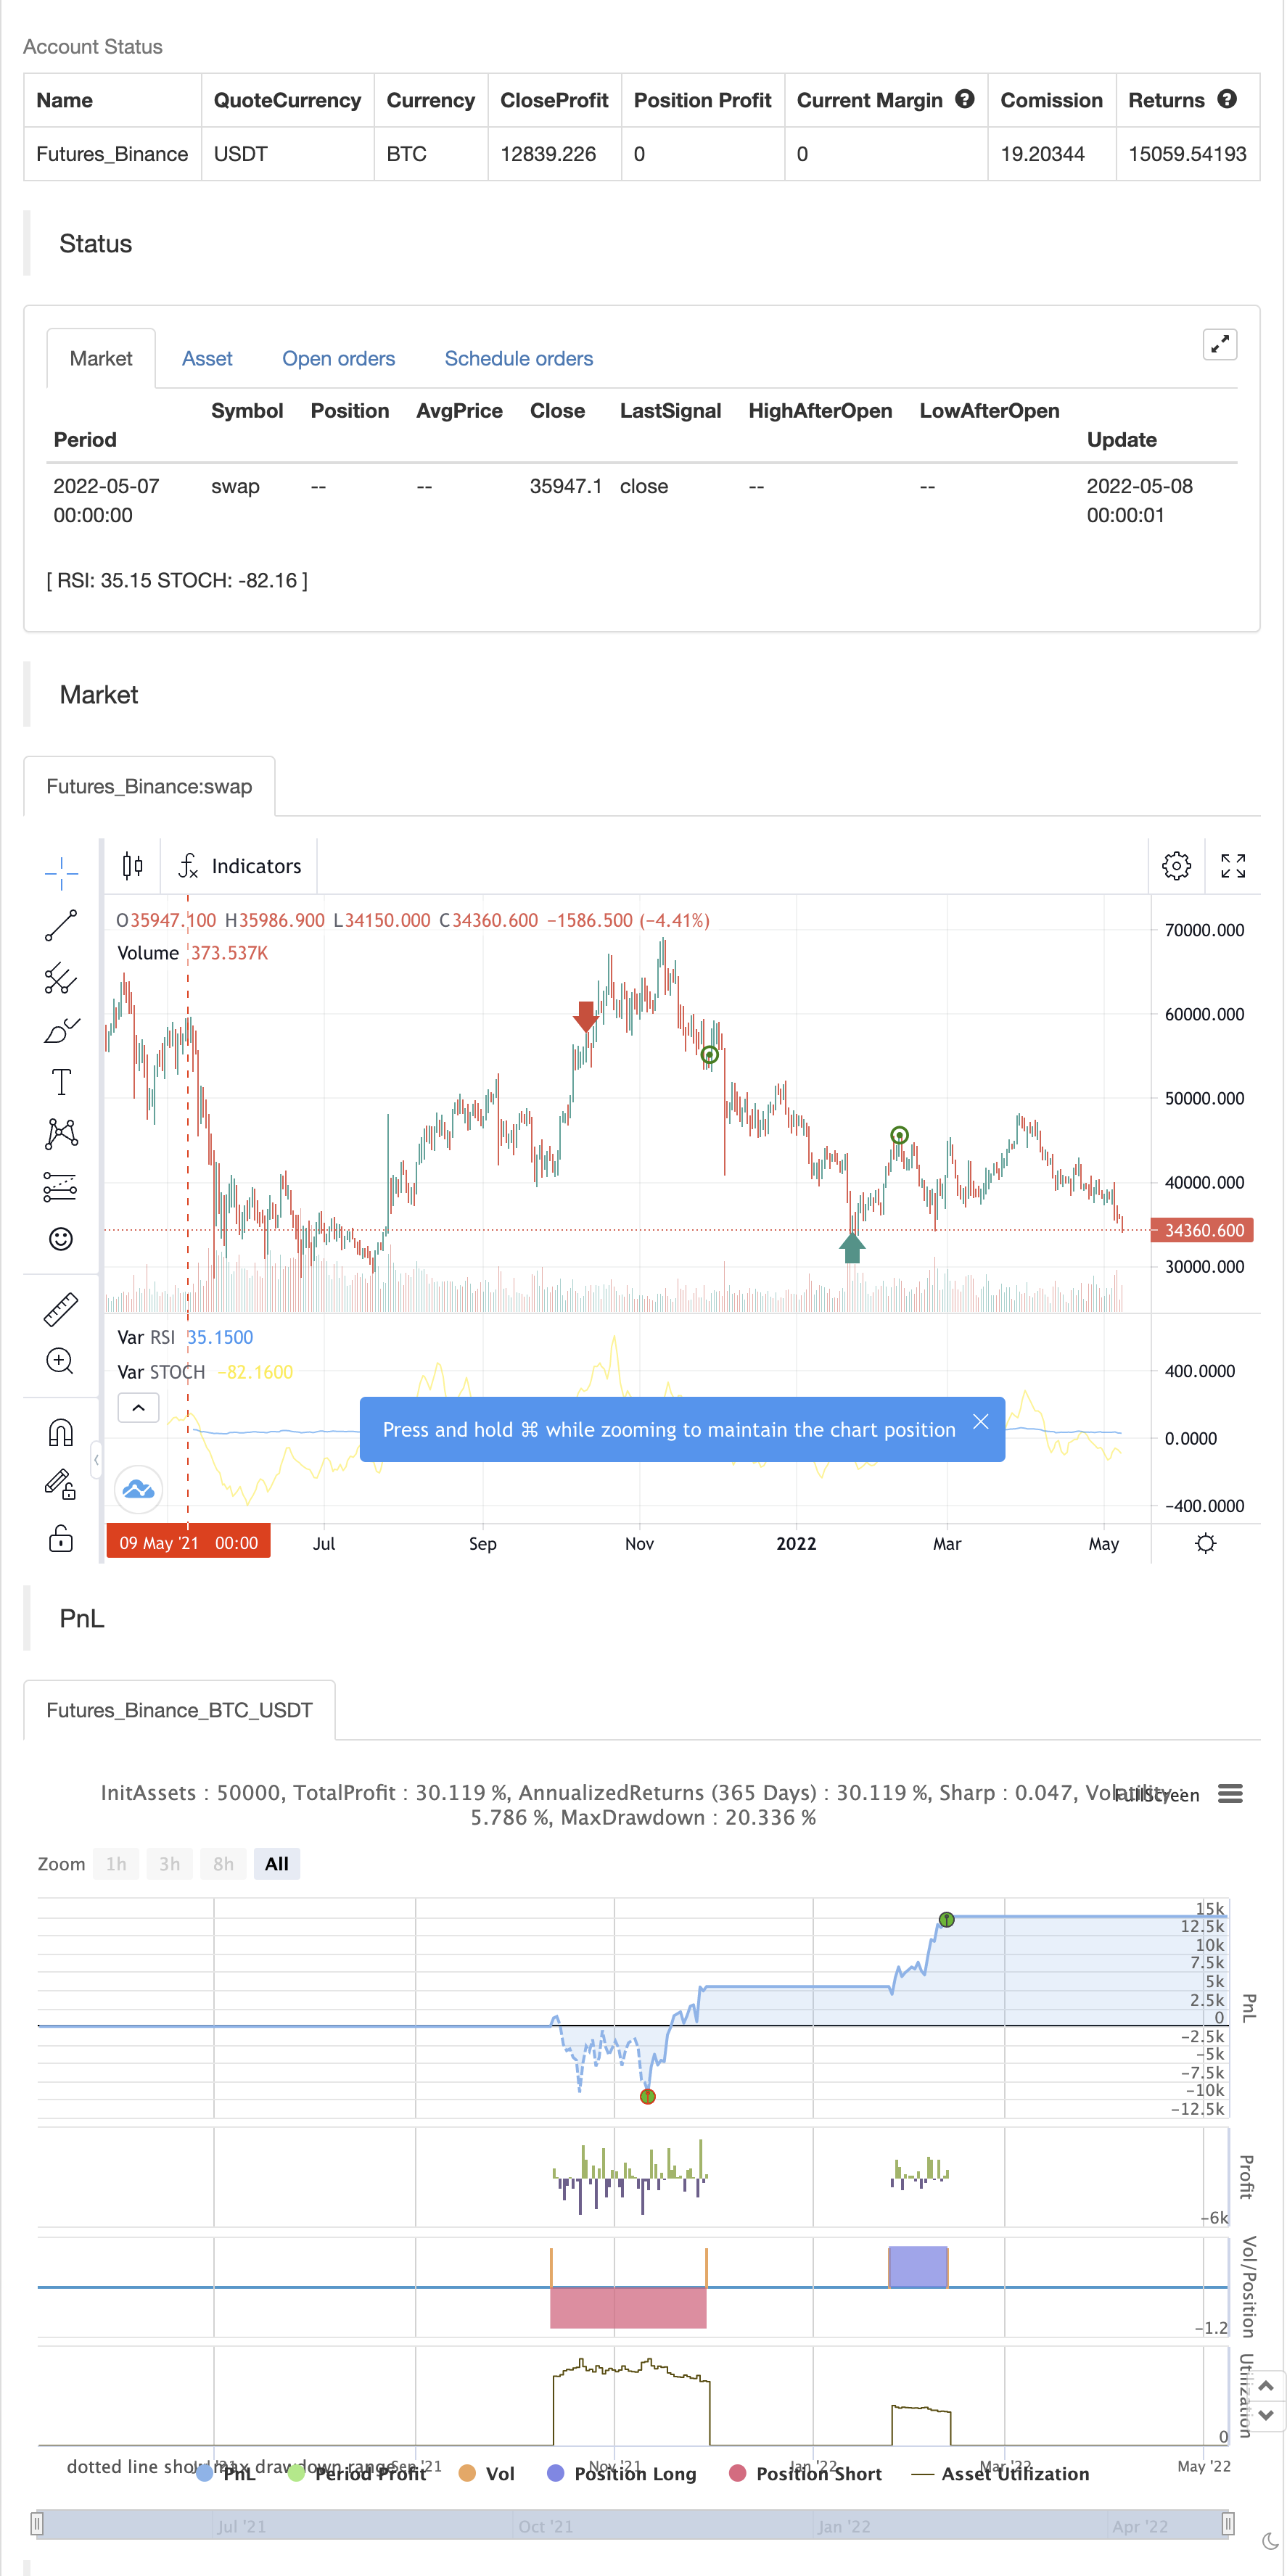
This sharing is an indicator where you can see the average of different time frames. The RSI is the blue line The Stock is the yellow line You can manage the timeframe in the parameters. The strategy is to take…
This sharing is an indicator where you can see the average of different time frames.
The RSI is the blue line The Stock is the yellow line
You can manage the timeframe in the parameters.
The strategy is to take position when the two lines get overbought or oversold and close when the stoch and RSI goes to the middle.
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 80 | (?GRP1)Overbought Level |
| v_input_int_2 | 20 | Oversold Level |
| v_input_timeframe_1 | W | (?GRP2)Timeframe 1 |
| v_input_timeframe_2 | D | Timeframe 2 |
| v_input_timeframe_3 | 240 | Timeframe 3 |
| v_input_timeframe_4 | 60 | Timeframe 4 |
| v_input_int_3 | 14 | (?GRP3)RSI length |
| v_input_1_close | 0 | RSI Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_int_4 | 70 | RSI Overbought Level |
| v_input_int_5 | 30 | RSI Oversold Level |
| v_input_int_6 | 14 | (?GRP4)%K length |
| v_input_int_7 | 3 | Smooth K |
| v_input_2_close | 0 | Stochastic Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_int_8 | 70 | Stochastic Overbought Level |
| v_input_int_9 | 30 | Stochastic Oversold Level |
Source Pine Script
/*backtest
start: 2021-05-09 00:00:00
end: 2022-05-08 23:59:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

////////////////////////////////////////// MTF Stochastic & RSI Strategy ©️ bykzis /////////////////////////////////////////
//

// *** Inspired by "Binance CHOP Dashboard" from @Cazimiro and "RSI MTF Table" from @mobester16 *** and LOT OF COPY of Indicator-Jones MTF Scanner
//
////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////

//@version=5
//strategy('MTF RSI & STOCH Strategy', overlay=false,initial_capital=100, currency=currency.USD, commission_value=0.01, commission_type=strategy.commission.percent)


// Pair list
var string GRP1       = '══════════    General    ══════════'
overbought = input.int(80, 'Overbought Level', minval=1, group=GRP1)
oversold = input.int(20, 'Oversold Level', minval=1, group=GRP1)


/// Timeframes
var string GRP2       = '══════════   Timeframes   ══════════'
timeframe1 = input.timeframe(title="Timeframe 1", defval="W", group=GRP2)
timeframe2 = input.timeframe(title="Timeframe 2", defval="D", group=GRP2)
timeframe3 = input.timeframe(title="Timeframe 3", defval="240", group=GRP2)
timeframe4 = input.timeframe(title="Timeframe 4", defval="60", group=GRP2)

// RSI settings
var string GRP3       = '══════════   RSI settings   ══════════'
rsiLength = input.int(14, minval=1, title='RSI length', group=GRP3)
rsiSource = input(close, 'RSI Source', group=GRP3)
rsioverbought = input.int(70, 'RSI Overbought Level', minval=1, group=GRP3)
rsioversold = input.int(30, 'RSI Oversold Level', minval=1, group=GRP3)


/// Get RSI values of each timeframe /////////////////////////////////////////////////////
rsi = ta.rsi(rsiSource, rsiLength)
callRSI(id,timeframe) =>
    rsiValue = request.security(id, str.tostring(timeframe), rsi, gaps=barmerge.gaps_off)
    rsiValue

RSI_TF1 = callRSI(syminfo.tickerid, timeframe1)
RSI_TF2 = callRSI(syminfo.tickerid, timeframe2)
RSI_TF3 = callRSI(syminfo.tickerid, timeframe3)
RSI_TF4 = callRSI(syminfo.tickerid, timeframe4)


/////// Calculate Averages /////////////////////////////////////////////////////////////////
calcAVG(valueTF1, valueTF2, valueTF3, valueTF4) =>
    math.round((valueTF1 + valueTF2 + valueTF3 + valueTF4) / 4, 2)

AVG=calcAVG(RSI_TF1, RSI_TF2, RSI_TF3, RSI_TF4)


// Stochastic settings
var string GRP4       = '══════════   Stochastic settings   ══════════'
periodK = input.int(14, '%K length', minval=1, group=GRP4)
smoothK = input.int(3, 'Smooth K', minval=1, group=GRP4)
stochSource = input(close, 'Stochastic Source', group=GRP4)
stochoverbought = input.int(70, 'Stochastic Overbought Level', minval=1, group=GRP4)
stochoversold = input.int(30, 'Stochastic Oversold Level', minval=1, group=GRP4)


/// Get Stochastic values of each timeframe ////////////////////////////////////////////////
stoch = ta.sma(ta.stoch(stochSource, high, low, periodK), smoothK)
getStochastic(id,timeframe) =>
    stochValue = request.security(id, str.tostring(timeframe), stoch, gaps=barmerge.gaps_off)
    stochValue

Stoch_TF1 = getStochastic(syminfo.tickerid, timeframe1)
Stoch_TF2 = getStochastic(syminfo.tickerid, timeframe2)
Stoch_TF3 = getStochastic(syminfo.tickerid, timeframe3)
Stoch_TF4 = getStochastic(syminfo.tickerid, timeframe4)


AVG_STOCH=calcAVG(Stoch_TF1, Stoch_TF2, Stoch_TF3, Stoch_TF4)


plot(AVG, color = color.blue, title='RSI')
plot(AVG_STOCH, color = color.yellow,title='STOCH')
hline(rsioverbought,color=color.red)
hline(rsioversold, color=color.lime)
hline(50, color=color.white)

//============ signal Generator ==================================//

if AVG <= rsioversold and AVG_STOCH <=stochoversold
    strategy.entry('Buy_Long', strategy.long)


strategy.close("Buy_Long",when=(AVG_STOCH >=70 and AVG >=50 and close >=strategy.position_avg_price),comment="Long_OK")

if AVG >=rsioverbought and AVG_STOCH >=stochoverbought
    strategy.entry('Buy_Short', strategy.short)


strategy.close("Buy_Short",when=(AVG_STOCH <=30 and AVG <=50 and close <=strategy.position_avg_price),comment="Short_OK")


///////////////////////////////////////////////////////////////////////////////////////////
Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-10. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MTF-RSI-STOCH-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Low Pyramid Risk Tracking StrategyPine Script · Multi-timeframe · 1d
- Multi Timeframe RSI SRSI Trading StrategyPine Script · Multi-timeframe · 1d
- Multi timeframe RSI and Moving Average Trading StrategyPine Script · Multi-timeframe · 1h
- Aggregated Multi timeframe MACD RSI CCI StochRSI MA Linear Trading StrategyPine Script · Multi-timeframe · 1m
- Multi Timeframe MACD StochRSI Combo StrategyPine Script · Multi-timeframe · 1h
- Multi Timeframe RSI and Stochastics StrategyPine Script · Multi-timeframe · 1h