Strategy vault / Trend following
Multi EMA Bullish Trend Strategy
The Multi-EMA Bullish Trend Strategy is a trend following strategy based on multiple exponential moving averages (EMA) of different periods for trend determination. It goes long when price breaks above 10-day EMA and…
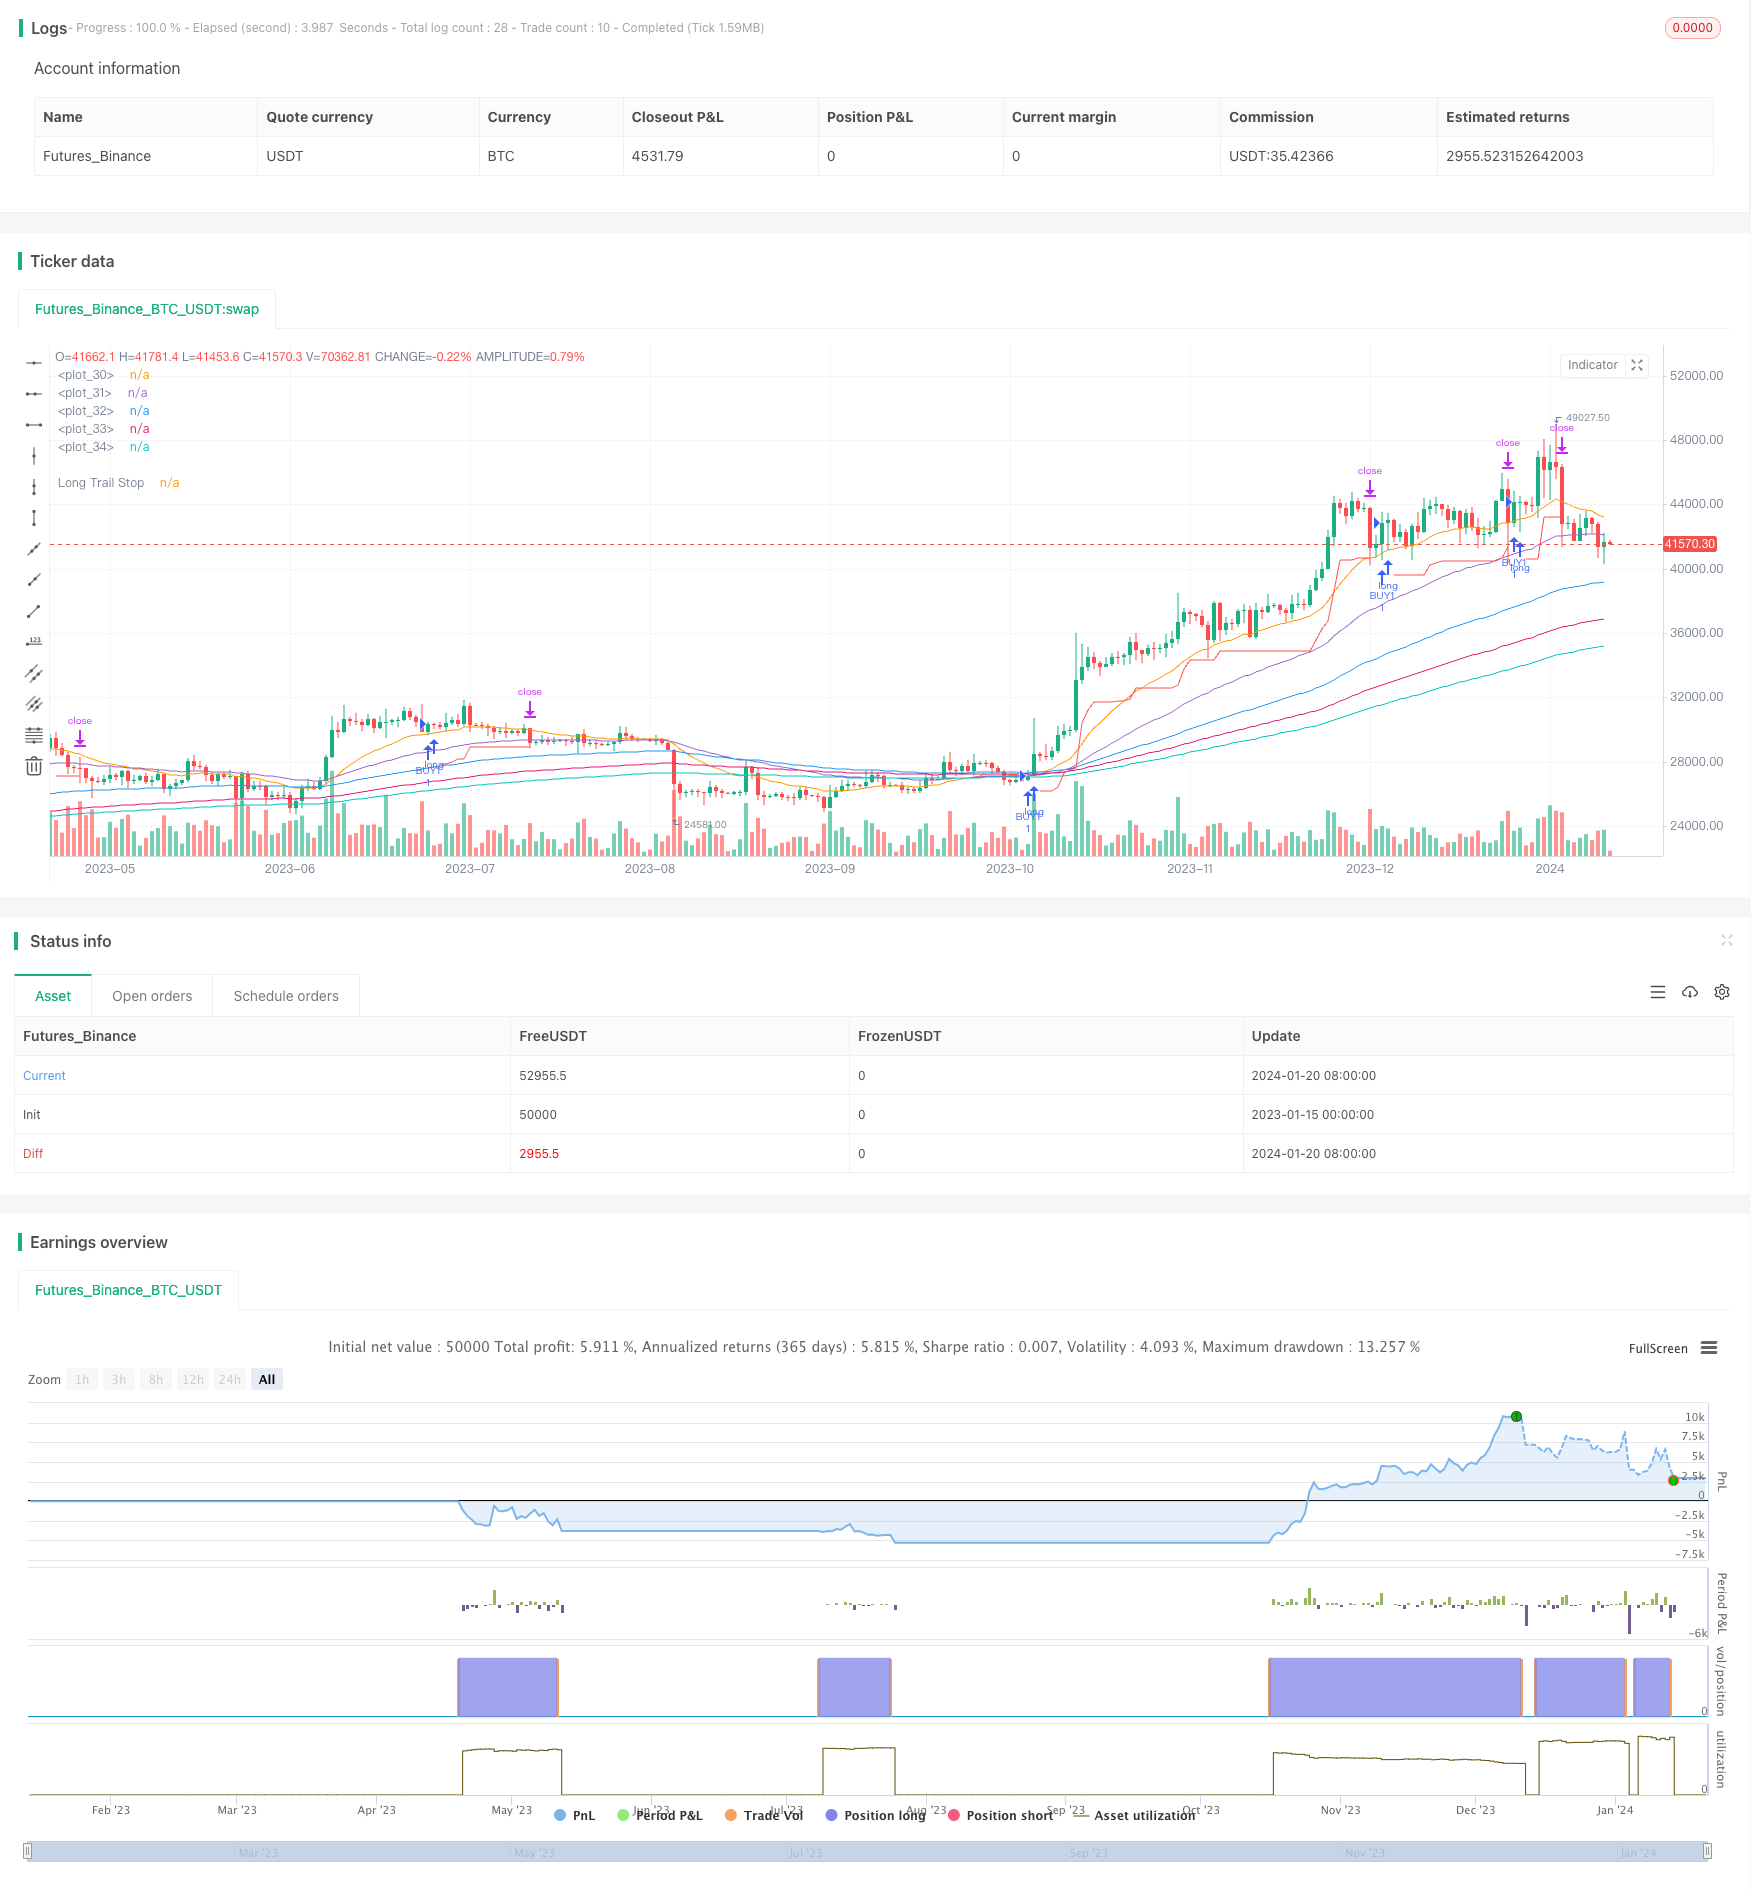
Overview
The Multi-EMA Bullish Trend Strategy is a trend following strategy based on multiple exponential moving averages (EMA) of different periods for trend determination. It goes long when price breaks above 10-day EMA and other longer period EMAs are in bullish alignment; and uses 8% trailing stop loss to lock in profits.
Strategy Logic
The strategy employs 6 EMAs of periods 10, 20, 50, 100, 150 and 200 days. These EMAs are used to determine the current cyclical stage of the market. When shorter period EMAs (e.g. 10-day) cross over longer period ones (e.g. 20-, 50-day), it signals the market has entered the markup phase of a bull trend.
Specifically, the strategy will go long when the following conditions are met:
- 10-day EMA is higher than 20-day EMA
- 20-day EMA is higher than 50-day EMA
- 100-day EMA is higher than 150-day EMA
- 150-day EMA is higher than 200-day EMA
- Close price crosses over 10-day EMA
After opening long position, an 8% trailing stop loss is used to lock in profits. That means the position will be kept open as long as the price does not fall more than 8% from the entry price. Once the drawdown exceeds 8%, the position will be closed to stop loss.
In summary, the key idea of this strategy is to enter bull trend when confirmed by multiple EMA alignment, and use trailing stop loss to lock in profits.
Advantage Analysis
The Multi-EMA bull trend strategy has the following major strengths:
- It can effectively filter false breakouts and ensure catching the markup cycles, reducing unnecessary trades.
- The multiple EMA filters lower the chance of stop loss being hit, allowing safer holding of positions.
- The 8% trailing stop loss is neither too tight nor too loose, balancing profit-taking and loss-stopping.
- The strategy allows flexible parameter tuning for optimization across different products.
Risk Analysis
There are also some risks to note for this strategy:
- EMA sequence cannot guarantee trend direction for 100% cases, some whipsaws can still occur.
- The 8% trailing stop may give up some profits during huge trends.
- EMA systems have inherent laggingness, turning points confirmation can be slightly delayed.
To address these risks, we can optimize by adjusting EMA periods or incorporating auxiliary indicators for improved judgment.
Optimization Directions
Considering the characteristics of this strategy, future optimizations can focus on the following aspects:
- Test different EMA combinations and period sets to find optimal parameters.
- Add volatility index indicators to gauge trend strength for avoiding unnecessary entries.
- Include more filtering indicators like MACD, KDJ for bullish alignment confirmation.
- Employ machine learning algorithms for dynamic stop loss implementation.
Conclusion
Overall, the Multi-EMA Bull Trend Strategy is a robust and reliable trend following system, balancing trend determination and risk control. There is still great potential for improvement via parameter tuning and algorithm optimization. It is an effective strategy worth trying out and researching on.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2000 | Backtest Start Year |
| v_input_2 | true | Backtest Start Month |
| v_input_3 | true | Backtest Start Day |
| v_input_4 | 2100 | Backtest Stop Year |
| v_input_5 | 12 | Backtest Stop Month |
| v_input_6 | 30 | Backtest Stop Day |
| v_input_float_1 | 8 | Long Trailing Stop (%) |
Source Pine Script
/*backtest
start: 2023-01-15 00:00:00
end: 2024-01-21 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy('SirSeff\'s EMA Rainbow', overlay=true)
// Testing Start dates
testStartYear = input(2000, 'Backtest Start Year')
testStartMonth = input(1, 'Backtest Start Month')
testStartDay = input(1, 'Backtest Start Day')
testPeriodStart = timestamp(testStartYear, testStartMonth, testStartDay, 0, 0)
//Stop date if you want to use a specific range of dates
testStopYear = input(2100, 'Backtest Stop Year')
testStopMonth = input(12, 'Backtest Stop Month')
testStopDay = input(30, 'Backtest Stop Day')
testPeriodStop = timestamp(testStopYear, testStopMonth, testStopDay, 0, 0)

testPeriod() =>
    time >= testPeriodStart and time <= testPeriodStop ? true : false
// Component Code Stop

//TSP
trailStop = input.float(title='Long Trailing Stop (%)', minval=0.0, step=0.1, defval=8) * 0.01

longStopPrice = 0.0
longStopPrice := if strategy.position_size > 0
    stopValue = close * (1 - trailStop)
    math.max(stopValue, longStopPrice[1])
else
    0

//PLOTS
plot(series=strategy.position_size > 0 ? longStopPrice : na, color=color.new(color.red, 0), style=plot.style_linebr, linewidth=1, title='Long Trail Stop', offset=1, title='Long Trail Stop')
plot(ta.ema(close, 20))
plot(ta.ema(close, 50))
plot(ta.ema(close, 100))
plot(ta.ema(close, 150))
plot(ta.ema(close, 200))

//OPEN
longCondition =  ta.ema(close, 10) > ta.ema(close, 20) and ta.ema(close, 20) > ta.ema(close, 50) and ta.ema(close, 100) > ta.ema(close, 150) and ta.ema(close, 150) > ta.ema(close, 200)
if longCondition and ta.crossover(close,ta.ema(close,10)) and testPeriod()
    strategy.entry("BUY1", strategy.long)

if longCondition and ta.crossover(ta.ema(close,10),ta.ema(close,20)) and testPeriod()
    strategy.entry("BUY2'", strategy.long)

//CLOSE @ TSL
if strategy.position_size > 0 and testPeriod()
    strategy.exit(id='TSP', stop=longStopPrice)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-EMA-Bullish-Trend-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- ATR and T3 Moving Average StrategyPine Script · Trend following · 5m